
Stocks vs Mutual Funds: A Complete Guide to Smarter Investing
Choosing where to put your hard-earned money can feel overwhelming when markets move daily. The debate over stocks vs mutual funds is common among new and experienced investors. Both can provide long-term growth, but they work in different ways.
Individual stocks give you direct ownership in specific companies. Mutual funds pool money from many investors and spread it across stocks, bonds, or other securities. This structure can make diversification easier. The U.S. Securities and Exchange Commission (SEC) explains that diversification can help reduce investment risk, although it cannot eliminate market losses.
Your choice also affects the time, research, and risk management required. Direct stock investing demands more involvement. Mutual funds can simplify portfolio construction, especially when they hold many securities.
This guide answers five important questions:
- Is it better to own individual stocks or mutual funds?
- What does the 7% rule actually mean?
- How does an SIP compare with buying stocks directly?
- What has Warren Buffett said about investing?
- How concentrated is stock ownership among wealthy households?

Is it better to own stocks or mutual funds?
There is no universal winner in the stocks vs mutual funds debate. The better fit depends on your knowledge, goals, time horizon, risk tolerance and expected return, and willingness to research investments.
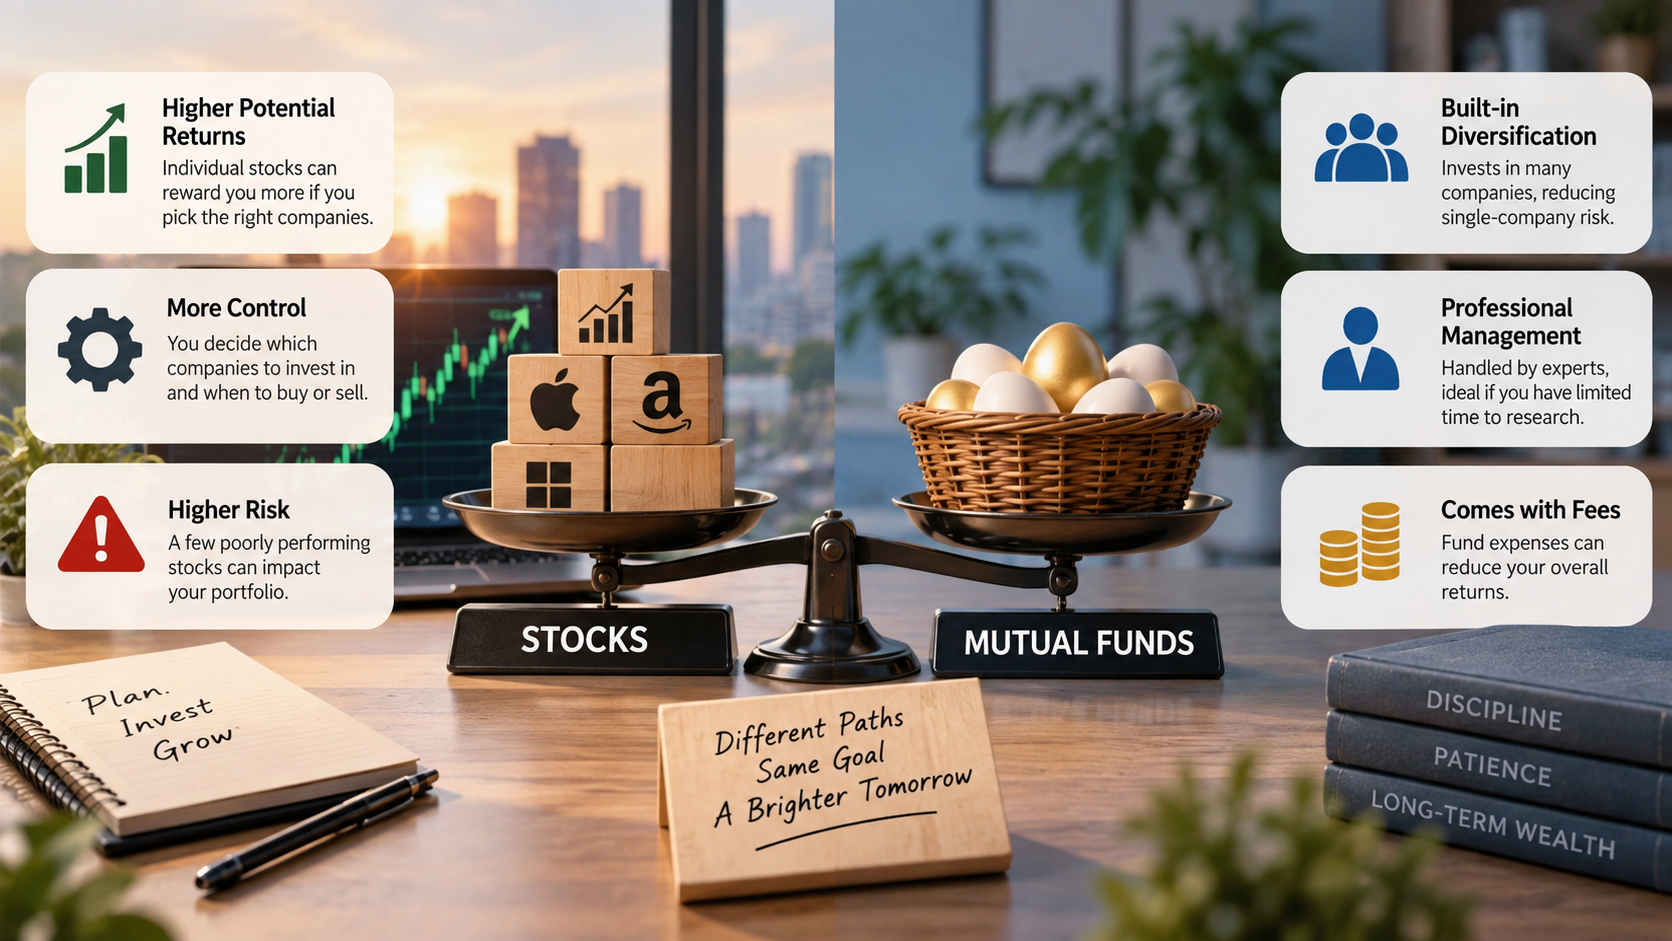
Individual stocks provide direct ownership in specific companies. They also give investors more control over which businesses they own. However, concentration can increase risk. If one company performs poorly, a large position can hurt the entire portfolio. The SEC specifically warns about the risks of investing heavily in individual stocks.
Mutual funds can provide diversification because one fund may hold many securities. Some funds also provide professional management. However, diversification depends on the fund’s strategy. Investors can explore modern asset allocation strategies to understand how different investments can be combined to manage portfolio risk. A narrowly focused fund may still carry significant concentration risk.
For many investors, the key question is not which asset is better. It is which approach they can understand, maintain, and follow consistently.
Balancing Active Control Against Built-In Diversification
Individual stocks give investors greater control over portfolio decisions. You can select specific companies, decide how much to invest, and change holdings whenever you choose. That flexibility can be useful for investors who understand financial statements and company fundamentals.
The trade-off is responsibility. You must research businesses, monitor developments, evaluate valuations, and manage concentration risk. A few poorly chosen stocks can have a large effect on portfolio performance.
Mutual funds take a different approach. They pool investor money and spread it across multiple securities. This can make diversification easier than building a diversified portfolio from individual stocks.
However, mutual funds are not automatically safer. Their risk depends on what they own. A broad equity fund differs significantly from a sector-specific fund.
Costs also matter. Fund expenses reduce returns over time, so investors should review fees before investing and compare FD and mutual fund returns when evaluating different ways to grow their money.
What is the 7% rule in stocks?
The 7% rule in stocks is better understood as a long-term planning assumption than a guaranteed market return. The SEC notes that the stock market has historically produced roughly 10% annual nominal returns over long periods. After accounting for inflation, historical real returns have been closer to 6% or 7%.
This distinction matters because inflation reduces purchasing power. A portfolio can grow substantially in nominal terms while producing a smaller increase in real wealth.
The 7% figure should therefore not be treated as a fixed annual outcome. Markets can produce strong gains, flat periods, or major losses in individual years. Even long-term averages can vary across different periods.
Investors often use the Rule of 72 alongside a 7% assumption. Dividing 72 by 7 gives roughly 10.3 years. This provides a simple estimate for how long it may take money to double at that rate.
However, actual returns will differ. Taxes, fees, inflation, investment selection, and market conditions can all change the outcome.
Which is better, SIP or stocks?
An SIP and direct stock investing are not directly comparable investment products. An SIP, or Systematic Investment Plan, is a method of investing a fixed amount at regular intervals. Investors can also compare SIP vs FD when evaluating regular investing against fixed-income savings options. You can use an SIP to invest in a mutual fund or another eligible investment product.
Direct stock investing works differently. You select individual companies and decide when to buy or sell their shares. This gives you more control, but it also requires greater responsibility for research and diversification.
Regular investing can help reduce the pressure of market timing. When prices fall, the same contribution purchases more units. When prices rise, it purchases fewer units. This approach does not guarantee profits, but it creates a consistent investing habit.
The SEC also notes that consistently adding money over time can help investors avoid putting all their money into the market at one unfavorable point.
For investors comparing SIP vs stocks, the key distinction is method versus asset selection. An SIP provides discipline. Stocks provide direct ownership.
Harnessing Consistency to Defeat Market Volatility
Regular investing can make market volatility easier to manage. Instead of trying to predict every market high and low, investors contribute according to a predetermined schedule.
Suppose an investor contributes ₹5,000 each month to a mutual fund. When prices decline, that ₹5,000 buys more units. When prices rise, it buys fewer units. Over time, the purchase price reflects multiple market levels.
This approach is commonly associated with rupee-cost averaging in India and dollar-cost averaging in the United States. It can reduce dependence on short-term market predictions. However, it does not guarantee better returns than investing a lump sum immediately.
Consistency also helps address behavioral problems. Investors may feel tempted to stop investing during market declines or invest aggressively after strong rallies. A predefined contribution schedule can reduce the influence of those emotions.
Still, investors should review their goals and portfolio periodically. Regular investing does not remove the need for diversification, suitable asset allocation, or risk management. Investors should also consider how to build an emergency fund so unexpected expenses do not force them to sell investments at an unfavorable time. The SEC recommends considering both financial goals and risk tolerance when making investment decisions.
What did Warren Buffett say about stocks?
Warren Buffett has repeatedly emphasized thinking of a stock as ownership in a real business. His approach focuses on understanding businesses rather than reacting to daily price movements.
Buffett has also expressed strong support for low-cost index investing for many individual investors. In Berkshire Hathaway’s 2017 shareholder letter, he described a virtually cost-free S&P 500 index fund as an investment he expected to outperform most investment professionals over time.
That does not mean Buffett argues that every individual stock is unsuitable. Berkshire’s own investment approach has involved owning businesses and publicly traded companies. His broader message emphasizes understanding what you own and avoiding unnecessary costs and activity.
Investors should also separate Buffett’s personal investment record from advice intended for ordinary investors. Managing Berkshire Hathaway involves resources and responsibilities that individual investors do not have.
The practical takeaway is to understand the business or fund before buying it. Avoid treating short-term price movements as the entire investment thesis.
Who owns 90% of the stock market?
The statement that the top 10% owns 90% of the stock market needs more context. Ownership concentration is substantial, but the exact percentage depends on what assets are measured and how ownership groups are defined.
Federal Reserve Distributional Financial Accounts data for 2026 Q2 shows significant differences in holdings of corporate equities and mutual fund shares across U.S. wealth groups. The data reports about $56.9 trillion in these combined holdings across the listed wealth groups, with the top 10% holding a much larger share than the bottom half.
This concentration helps explain why changes in financial asset prices can affect household wealth differently. Wealthier households generally have much greater exposure to corporate equities and mutual fund shares.
However, stock ownership is not limited to wealthy households. People can gain market exposure through retirement accounts, pensions, mutual funds, and other investment vehicles. The Federal Reserve’s data also separates corporate equities from other household assets, so broad claims about “the stock market” should be used carefully.
The more useful lesson is that market participation and market wealth are unevenly distributed. Investors should consider their own exposure rather than assume market ownership is uniform across households.
Frequently Asked Questions
Can you lose all your money in a mutual fund?
It is virtually impossible to lose all your capital in a broad, diversified mutual fund. For a fund to drop to zero, every underlying company would need to go bankrupt simultaneously. However, you can still lose a portion of your principal value if broad market conditions decline or if you sell during a cyclical downturn.
Do mutual funds pay dividends directly to investors?
Yes, mutual funds distribute accumulated dividends and realized capital gains to their shareholders. You can receive these payouts as direct cash deposits into your bank account, or you can automatically reinvest them. Choosing the automatic dividend reinvestment option accelerates long-term compound growth by buying additional fund units without transaction charges.
How many individual stocks should a beginner hold?
A beginner should generally own between 15 and 25 different stocks across separate industries to achieve basic diversification. Holding fewer than 15 shares exposes you to severe single-company volatility. Conversely, holding more than 30 companies makes it difficult to track balance sheets, corporate news, and earnings calls without institutional tools.
Conclusion
Evaluating stocks vs mutual funds shows that both investment options can serve different types of investors and financial goals. Individual stocks may suit investors who have the time, knowledge, and risk tolerance to research and monitor companies, while mutual funds can offer diversification and professional management with less day-to-day involvement. Investors should also understand how assets and liabilities affect personal finances before deciding how much capital to commit to investments. Neither option guarantees returns, so the right choice depends on your financial goals, investment horizon, risk tolerance, and willingness to manage investments.
Understanding principles such as long-term compounding, diversification, and the risks of speculative investing can help you make more informed decisions. Whether you invest through regular mutual fund contributions or build a portfolio of individual stocks, consistency and disciplined decision-making are generally more important than trying to predict short-term market movements.
Before choosing between stocks vs mutual funds, consider your available capital, financial objectives, risk tolerance, and the amount of time you can realistically devote to managing your investments. Select an approach that fits your circumstances, contribute consistently, review your strategy periodically, and give your investments enough time to potentially benefit from long-term compounding.