Category Archives: Finance

This category includes finance related information.

Stocks vs Mutual Funds: Which Investment Is Best?

Stocks vs Mutual Funds: A Complete Guide to Smarter Investing

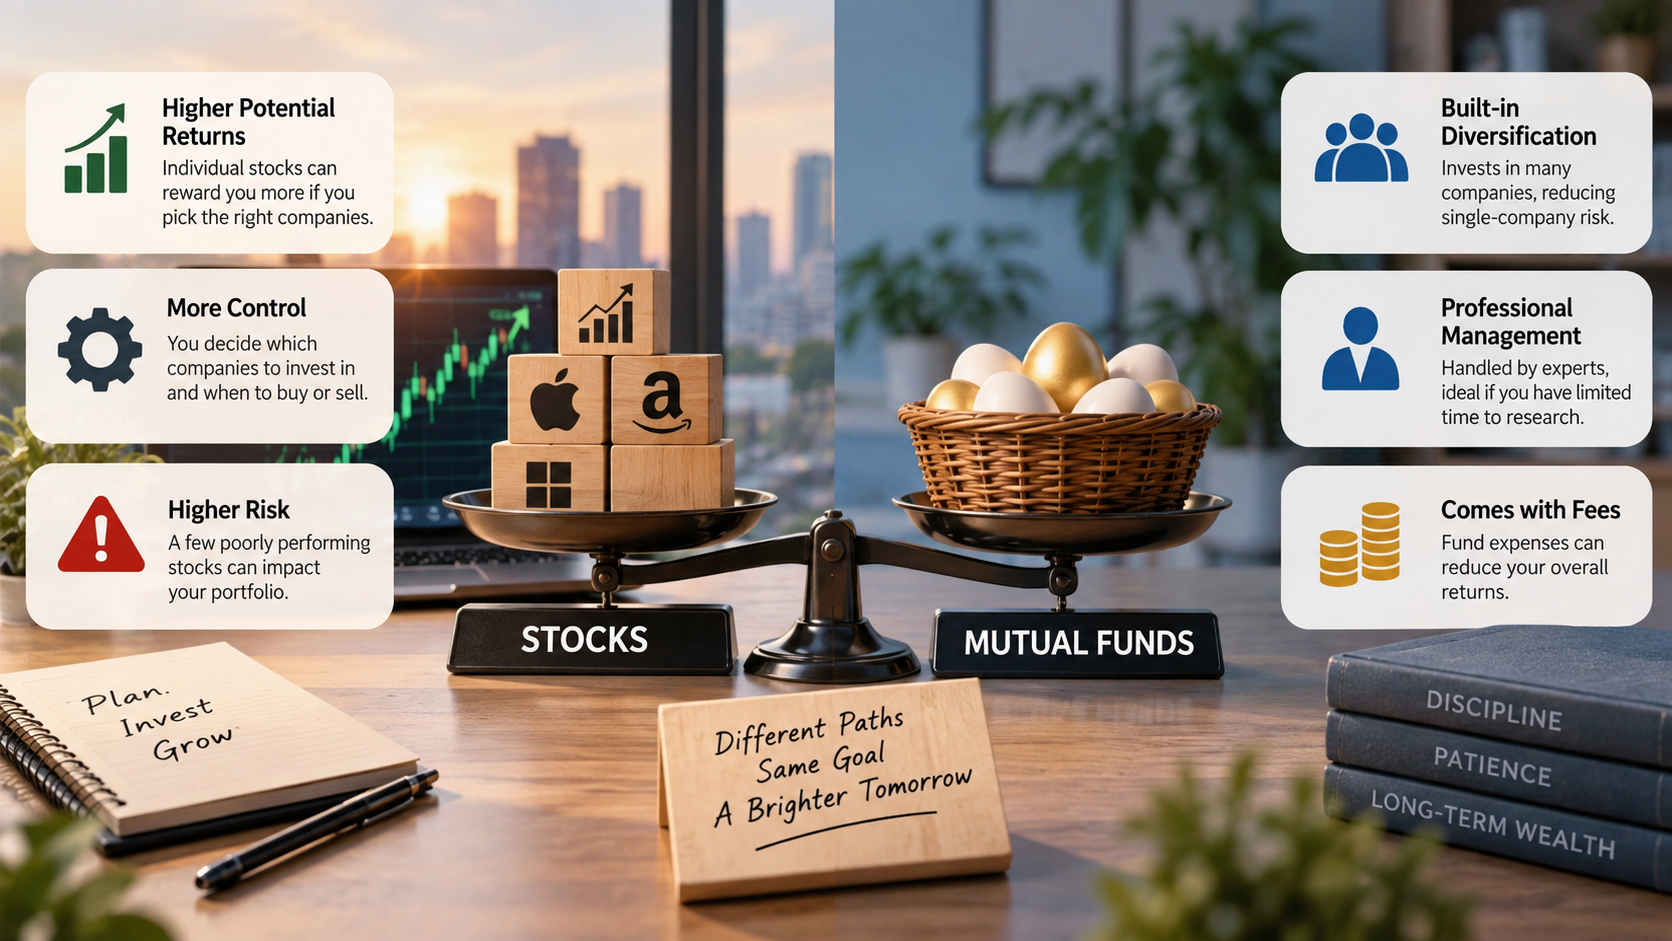
Choosing where to put your hard-earned money can feel overwhelming when markets move daily. The debate over stocks vs mutual funds is common among new and experienced investors. Both can provide long-term growth, but they work in different ways.

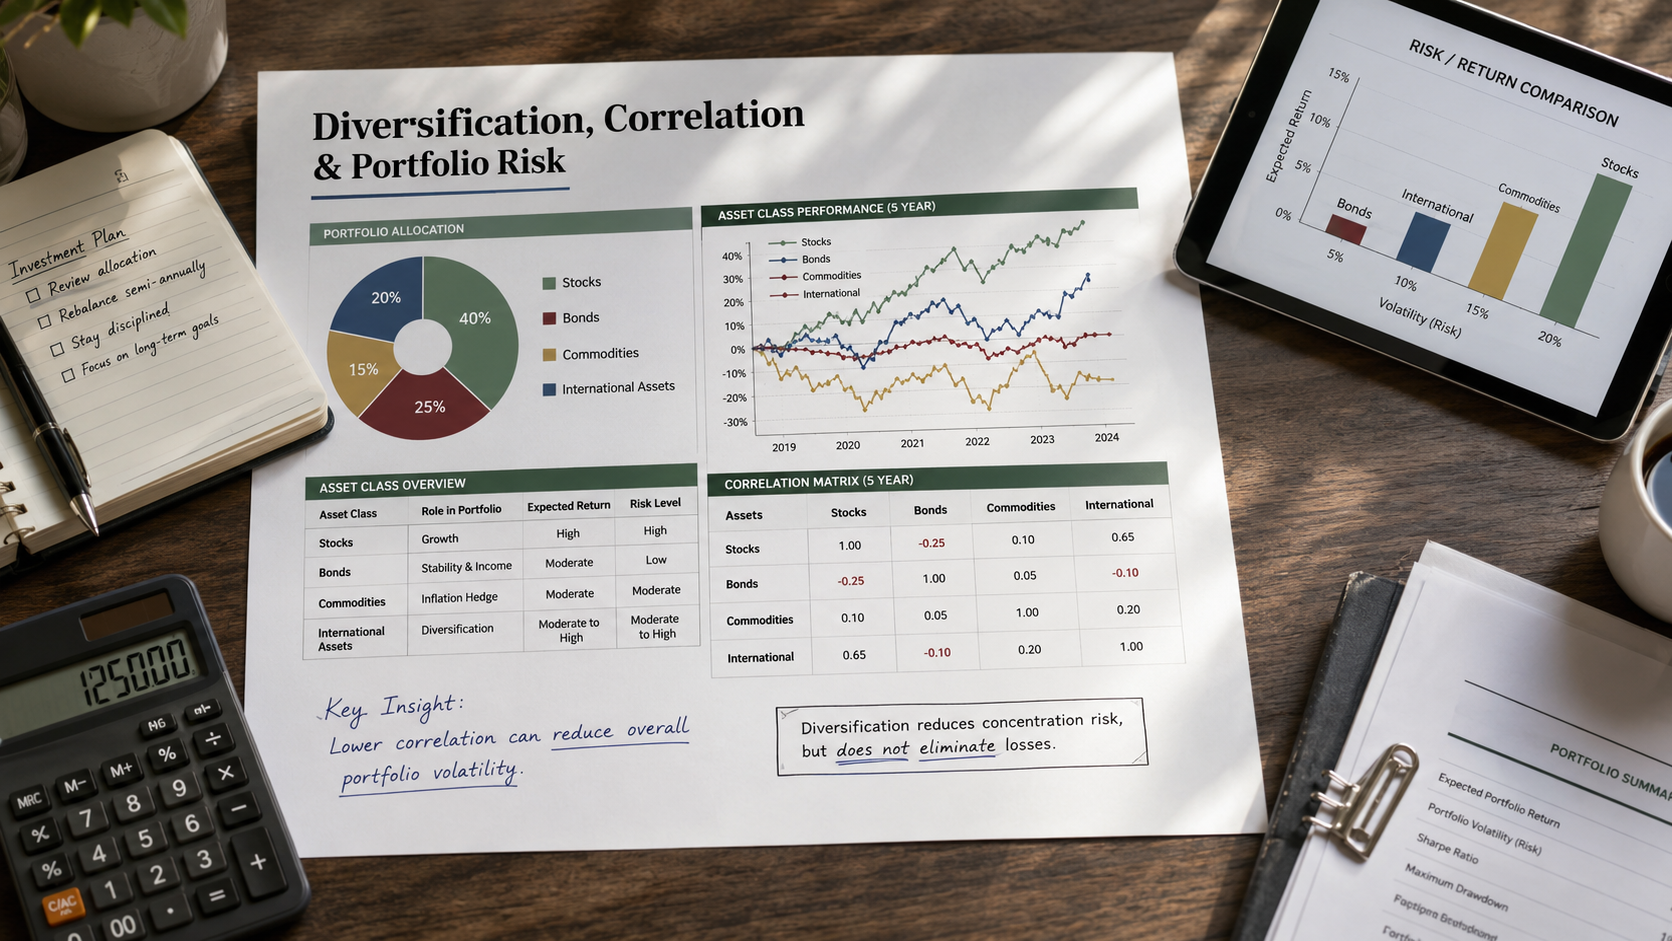
Individual stocks give you direct ownership in specific companies. Mutual funds pool money from many investors and spread it across stocks, bonds, or other securities. This structure can make diversification easier. The U.S. Securities and Exchange Commission (SEC) explains that diversification can help reduce investment risk, although it cannot eliminate market losses.

Your choice also affects the time, research, and risk management required. Direct stock investing demands more involvement. Mutual funds can simplify portfolio construction, especially when they hold many securities.

This guide answers five important questions:

  • Is it better to own individual stocks or mutual funds?
  • What does the 7% rule actually mean?
  • How does an SIP compare with buying stocks directly?
  • What has Warren Buffett said about investing?
  • How concentrated is stock ownership among wealthy households?

Is it better to own stocks or mutual funds?

There is no universal winner in the stocks vs mutual funds debate. The better fit depends on your knowledge, goals, time horizon, risk tolerance and expected return, and willingness to research investments.

Individual stocks provide direct ownership in specific companies. They also give investors more control over which businesses they own. However, concentration can increase risk. If one company performs poorly, a large position can hurt the entire portfolio. The SEC specifically warns about the risks of investing heavily in individual stocks.

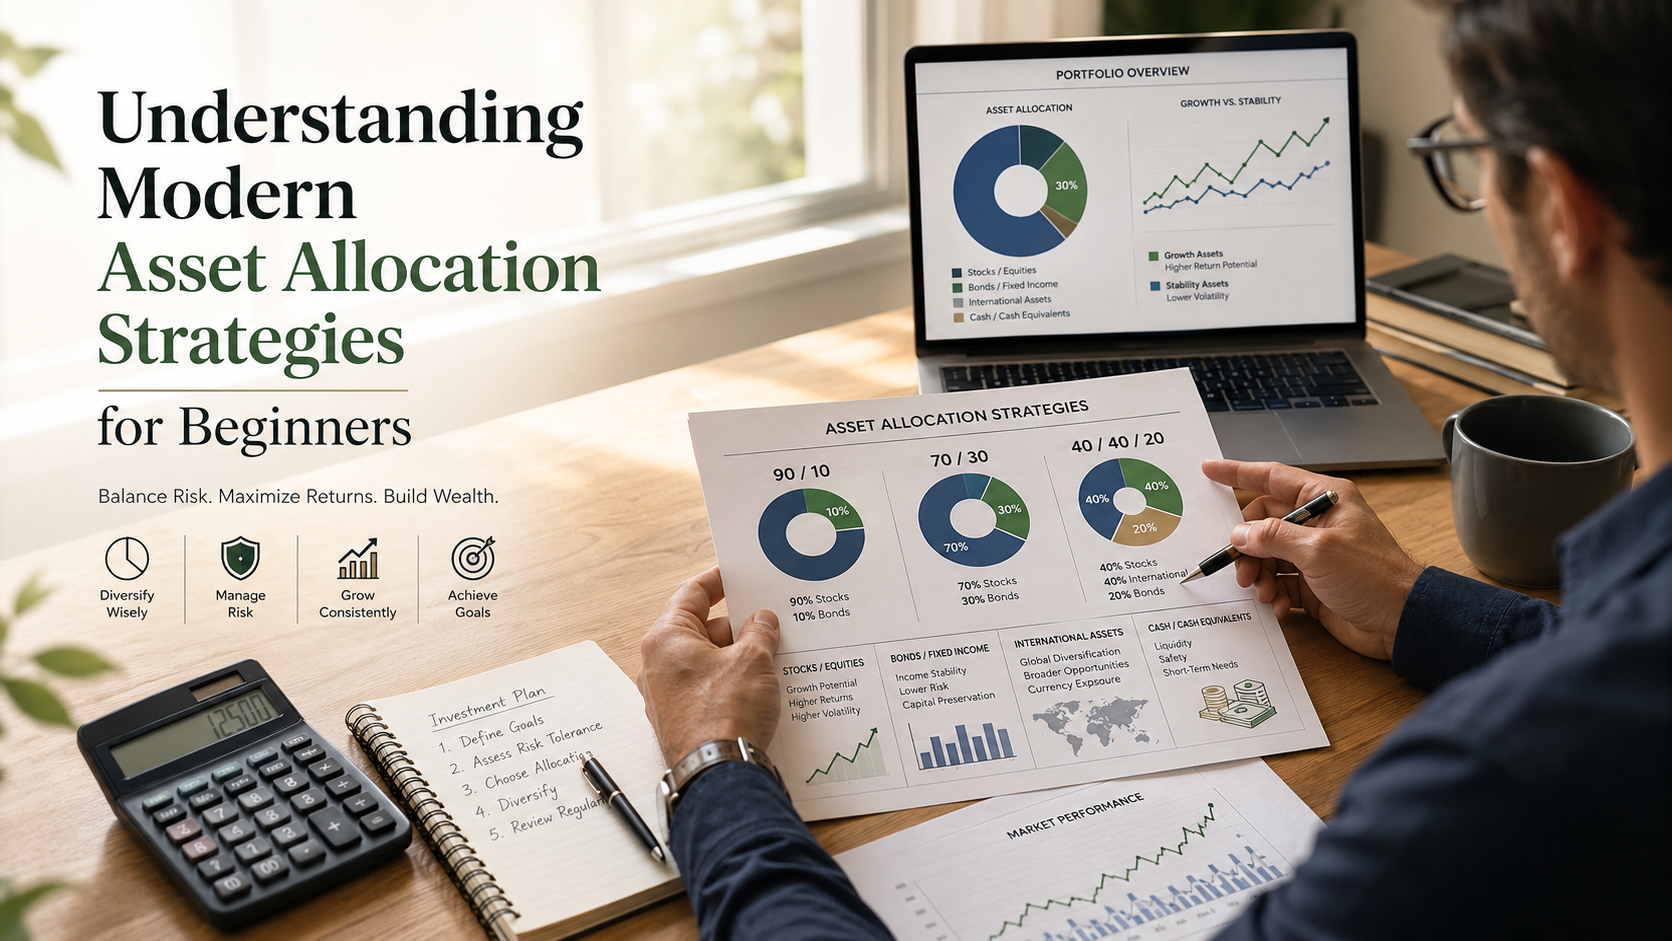
Mutual funds can provide diversification because one fund may hold many securities. Some funds also provide professional management. However, diversification depends on the fund’s strategy. Investors can explore modern asset allocation strategies to understand how different investments can be combined to manage portfolio risk. A narrowly focused fund may still carry significant concentration risk.

For many investors, the key question is not which asset is better. It is which approach they can understand, maintain, and follow consistently.

Balancing Active Control Against Built-In Diversification

Individual stocks give investors greater control over portfolio decisions. You can select specific companies, decide how much to invest, and change holdings whenever you choose. That flexibility can be useful for investors who understand financial statements and company fundamentals.

The trade-off is responsibility. You must research businesses, monitor developments, evaluate valuations, and manage concentration risk. A few poorly chosen stocks can have a large effect on portfolio performance.

Mutual funds take a different approach. They pool investor money and spread it across multiple securities. This can make diversification easier than building a diversified portfolio from individual stocks.

However, mutual funds are not automatically safer. Their risk depends on what they own. A broad equity fund differs significantly from a sector-specific fund.

Costs also matter. Fund expenses reduce returns over time, so investors should review fees before investing and compare FD and mutual fund returns when evaluating different ways to grow their money.

What is the 7% rule in stocks?

The 7% rule in stocks is better understood as a long-term planning assumption than a guaranteed market return. The SEC notes that the stock market has historically produced roughly 10% annual nominal returns over long periods. After accounting for inflation, historical real returns have been closer to 6% or 7%.

This distinction matters because inflation reduces purchasing power. A portfolio can grow substantially in nominal terms while producing a smaller increase in real wealth.

The 7% figure should therefore not be treated as a fixed annual outcome. Markets can produce strong gains, flat periods, or major losses in individual years. Even long-term averages can vary across different periods.

Investors often use the Rule of 72 alongside a 7% assumption. Dividing 72 by 7 gives roughly 10.3 years. This provides a simple estimate for how long it may take money to double at that rate.

However, actual returns will differ. Taxes, fees, inflation, investment selection, and market conditions can all change the outcome.

Which is better, SIP or stocks?

An SIP and direct stock investing are not directly comparable investment products. An SIP, or Systematic Investment Plan, is a method of investing a fixed amount at regular intervals. Investors can also compare SIP vs FD when evaluating regular investing against fixed-income savings options. You can use an SIP to invest in a mutual fund or another eligible investment product.

Direct stock investing works differently. You select individual companies and decide when to buy or sell their shares. This gives you more control, but it also requires greater responsibility for research and diversification.

Regular investing can help reduce the pressure of market timing. When prices fall, the same contribution purchases more units. When prices rise, it purchases fewer units. This approach does not guarantee profits, but it creates a consistent investing habit.

The SEC also notes that consistently adding money over time can help investors avoid putting all their money into the market at one unfavorable point.

For investors comparing SIP vs stocks, the key distinction is method versus asset selection. An SIP provides discipline. Stocks provide direct ownership.

Harnessing Consistency to Defeat Market Volatility

Regular investing can make market volatility easier to manage. Instead of trying to predict every market high and low, investors contribute according to a predetermined schedule.

Suppose an investor contributes ₹5,000 each month to a mutual fund. When prices decline, that ₹5,000 buys more units. When prices rise, it buys fewer units. Over time, the purchase price reflects multiple market levels.

This approach is commonly associated with rupee-cost averaging in India and dollar-cost averaging in the United States. It can reduce dependence on short-term market predictions. However, it does not guarantee better returns than investing a lump sum immediately.

Consistency also helps address behavioral problems. Investors may feel tempted to stop investing during market declines or invest aggressively after strong rallies. A predefined contribution schedule can reduce the influence of those emotions.

Still, investors should review their goals and portfolio periodically. Regular investing does not remove the need for diversification, suitable asset allocation, or risk management. Investors should also consider how to build an emergency fund so unexpected expenses do not force them to sell investments at an unfavorable time. The SEC recommends considering both financial goals and risk tolerance when making investment decisions.

What did Warren Buffett say about stocks?

Warren Buffett has repeatedly emphasized thinking of a stock as ownership in a real business. His approach focuses on understanding businesses rather than reacting to daily price movements.

Buffett has also expressed strong support for low-cost index investing for many individual investors. In Berkshire Hathaway’s 2017 shareholder letter, he described a virtually cost-free S&P 500 index fund as an investment he expected to outperform most investment professionals over time.

That does not mean Buffett argues that every individual stock is unsuitable. Berkshire’s own investment approach has involved owning businesses and publicly traded companies. His broader message emphasizes understanding what you own and avoiding unnecessary costs and activity.

Investors should also separate Buffett’s personal investment record from advice intended for ordinary investors. Managing Berkshire Hathaway involves resources and responsibilities that individual investors do not have.

The practical takeaway is to understand the business or fund before buying it. Avoid treating short-term price movements as the entire investment thesis.

Who owns 90% of the stock market?

The statement that the top 10% owns 90% of the stock market needs more context. Ownership concentration is substantial, but the exact percentage depends on what assets are measured and how ownership groups are defined.

Federal Reserve Distributional Financial Accounts data for 2026 Q2 shows significant differences in holdings of corporate equities and mutual fund shares across U.S. wealth groups. The data reports about $56.9 trillion in these combined holdings across the listed wealth groups, with the top 10% holding a much larger share than the bottom half.

This concentration helps explain why changes in financial asset prices can affect household wealth differently. Wealthier households generally have much greater exposure to corporate equities and mutual fund shares.

However, stock ownership is not limited to wealthy households. People can gain market exposure through retirement accounts, pensions, mutual funds, and other investment vehicles. The Federal Reserve’s data also separates corporate equities from other household assets, so broad claims about “the stock market” should be used carefully.

The more useful lesson is that market participation and market wealth are unevenly distributed. Investors should consider their own exposure rather than assume market ownership is uniform across households.

Frequently Asked Questions

Can you lose all your money in a mutual fund?

It is virtually impossible to lose all your capital in a broad, diversified mutual fund. For a fund to drop to zero, every underlying company would need to go bankrupt simultaneously. However, you can still lose a portion of your principal value if broad market conditions decline or if you sell during a cyclical downturn.

Do mutual funds pay dividends directly to investors?

Yes, mutual funds distribute accumulated dividends and realized capital gains to their shareholders. You can receive these payouts as direct cash deposits into your bank account, or you can automatically reinvest them. Choosing the automatic dividend reinvestment option accelerates long-term compound growth by buying additional fund units without transaction charges.

How many individual stocks should a beginner hold?

A beginner should generally own between 15 and 25 different stocks across separate industries to achieve basic diversification. Holding fewer than 15 shares exposes you to severe single-company volatility. Conversely, holding more than 30 companies makes it difficult to track balance sheets, corporate news, and earnings calls without institutional tools.

Conclusion

Evaluating stocks vs mutual funds shows that both investment options can serve different types of investors and financial goals. Individual stocks may suit investors who have the time, knowledge, and risk tolerance to research and monitor companies, while mutual funds can offer diversification and professional management with less day-to-day involvement. Investors should also understand how assets and liabilities affect personal finances before deciding how much capital to commit to investments. Neither option guarantees returns, so the right choice depends on your financial goals, investment horizon, risk tolerance, and willingness to manage investments.

Understanding principles such as long-term compounding, diversification, and the risks of speculative investing can help you make more informed decisions. Whether you invest through regular mutual fund contributions or build a portfolio of individual stocks, consistency and disciplined decision-making are generally more important than trying to predict short-term market movements.

Before choosing between stocks vs mutual funds, consider your available capital, financial objectives, risk tolerance, and the amount of time you can realistically devote to managing your investments. Select an approach that fits your circumstances, contribute consistently, review your strategy periodically, and give your investments enough time to potentially benefit from long-term compounding.

Income-Driven Repayment Plan: The Complete Guide

The Complete Guide to Choosing an Income-Driven Repayment Plan

Managing federal student loan debt can become difficult when standard payments consume too much of your income. An income-driven repayment plan can make federal loans more manageable by connecting your payment to factors such as income and family size. You can review current federal repayment options through Federal Student Aid.

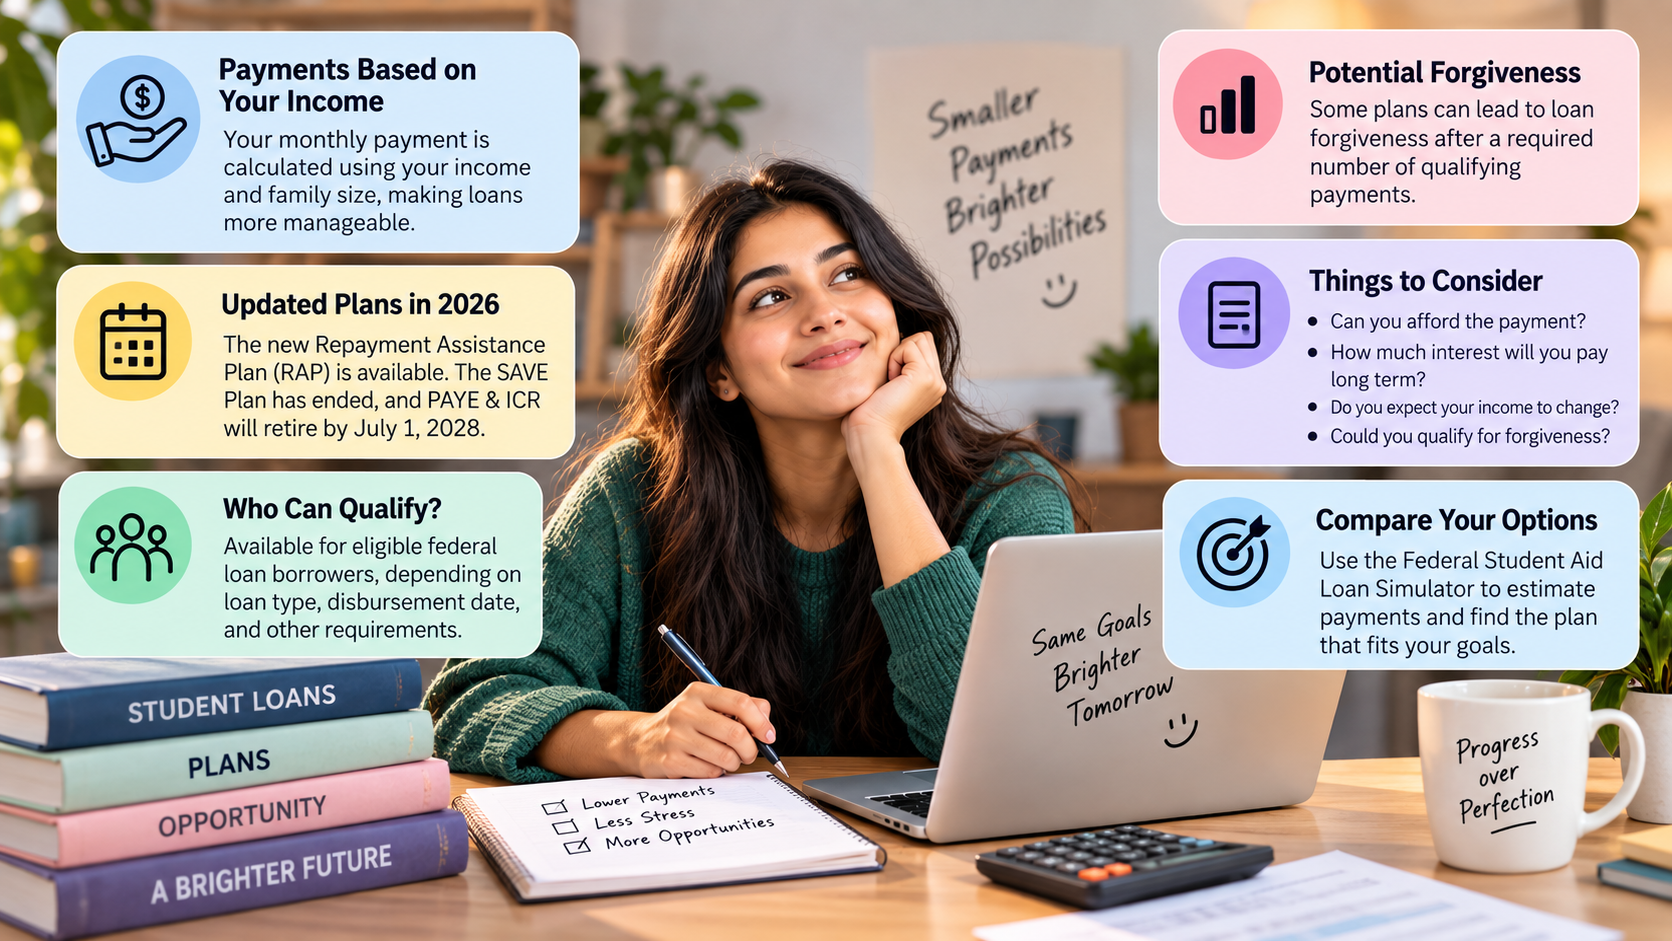
Federal student loan repayment rules have changed significantly in 2026. The available plans now depend on your loan type, disbursement date, and other eligibility requirements. The Repayment Assistance Plan (RAP) is now available, while the SAVE Plan ended in March 2026. PAYE and ICR are also scheduled to retire no later than July 1, 2028. Check the latest Federal Student Aid repayment guidance and Student Loan Guidelines 2026 before choosing a plan.

Understanding these rules matters before choosing a repayment strategy. An IDR plan may lower your monthly obligation and help you avoid delinquency or default. However, a smaller payment can also mean a longer repayment period and higher interest costs.

This guide explains how an income-driven repayment plan works, who may qualify, how forgiveness works, and what to do when payments remain unaffordable. For personalized estimates, borrowers can also use the Federal Student Aid Loan Simulator to compare repayment options.

Is it smart to do an income-driven repayment plan?

Choosing an income-driven repayment plan can make sense when your standard payment does not fit your budget. These plans generally calculate payments using your income, family size, loan type, and applicable federal rules. A lower monthly obligation can free money for housing, food, emergency savings, or other high-priority expenses.

However, a lower payment does not automatically mean a lower total cost. A longer repayment period can allow interest to accumulate for more years. Your best option therefore depends on both your current cash flow and expected future income. Building a clear personal financial plan for wealth can help you balance debt repayment with longer-term financial goals.

Before enrolling, compare the estimated payment and total repayment cost. Also consider whether you may qualify for student loan forgiveness or Public Service Loan Forgiveness.

An IDR plan may be particularly useful when:

  • Your income is relatively low compared with your federal loan balance.
  • Your monthly payment is difficult to afford.
  • You expect your income to change substantially.
  • You are pursuing a qualifying forgiveness program.

Balancing Immediate Savings Against Long-Term Interest

An IDR plan can provide immediate payment relief, but that benefit comes with a potential trade-off. Lower payments may extend the time needed to repay your federal student loans. During that period, interest may continue to increase your overall repayment cost. If you want to reduce your balances more aggressively, paying off debt faster can help shorten the repayment period and limit interest costs.

For example, a borrower with a modest current income may benefit from a lower required payment today. However, someone expecting rapid salary growth may eventually pay substantially more than they would under a faster repayment strategy.

Compare both sides before choosing:

  • Monthly affordability: Can you comfortably make the required payment?
  • Total interest: How much could the loan cost over time?
  • Future income: Is your salary likely to increase?
  • Forgiveness: Could you benefit from qualifying forgiveness?
  • Career plans: Might you qualify for Public Service Loan Forgiveness?

The cheapest plan today is not necessarily the cheapest plan overall. Use the federal repayment calculator to compare your available options before making a decision.

What is an income-driven repayment plan?

An income-driven repayment plan is a federal student loan repayment option that bases your required payment on factors such as income and family size. Instead of relying only on your original balance and a fixed repayment schedule, the calculation considers your financial circumstances.

Your available plans depend on your federal loan types and when those loans were first disbursed. In 2026, eligible borrowers may encounter plans such as Income-Based Repayment (IBR), Pay As You Earn (PAYE), Income-Contingent Repayment (ICR), and the new Repayment Assistance Plan (RAP). Not every borrower qualifies for every option.

You generally must provide updated income information during annual recertification. Your payment can therefore change when your income or family circumstances change.

Some IDR plans can eventually provide forgiveness after a required number of qualifying payments. The exact timeline depends on the plan and borrower circumstances.

Which is the best income-driven repayment plan?

There is no single best income-driven repayment plan for every borrower. Your ideal option depends on your loan types, disbursement dates, income, family size, and long-term repayment goals.

The current federal system includes the Repayment Assistance Plan (RAP) and other IDR options for borrowers who meet specific requirements. IBR remains available for qualifying borrowers. PAYE and ICR may still apply to certain older loans, but both plans are scheduled to end no later than July 1, 2028.

This makes the timing of your loans especially important. A plan that appears attractive today may require you to switch plans later.

When comparing options, consider:

  • Your current monthly payment.
  • Your expected income growth.
  • Your loan balance and interest rate.
  • Your eligibility for forgiveness.
  • Your expected repayment period.
  • Whether your plan is scheduled to end.

Use the federal repayment calculator rather than choosing a plan based solely on its advertised payment percentage.

Are IDR loans forgiven after 20 years?

Some federal student loans can receive forgiveness after 20 or 25 years of qualifying repayment, depending on the applicable income-driven repayment plan and borrower circumstances. The exact forgiveness period is not identical across every plan.

For example, qualifying IBR borrowers may receive forgiveness after 20 years if they meet the definition of a new borrower under the applicable rules. Other IBR borrowers may face a 25-year repayment period. PAYE generally uses a 20-year period, while ICR generally uses 25 years. These older plans are scheduled to be retired no later than July 1, 2028.

RAP has different repayment rules, including a longer potential repayment period.

You must also maintain eligibility and satisfy the requirements for qualifying payments. Annual income recertification remains important for IDR borrowers.

Do not assume that simply making payments for 20 years guarantees forgiveness. Your plan, loan history, qualifying payments, and federal rules determine whether and when a remaining balance can be discharged.

Monitoring Policy Changes Regarding the Forgiveness Tax Bomb

Tax treatment can make student loan forgiveness more complicated than the advertised repayment period suggests. A forgiven balance may potentially create a federal or state tax obligation, depending on the law in effect when the discharge occurs.

That matters because borrowers pursuing IDR forgiveness may be planning over several decades. Tax rules can change during that period, making today’s assumptions unreliable for a future discharge.

Instead of assuming forgiven debt will always be tax-free, monitor official federal and state guidance as your forgiveness date approaches. Keep records of your repayment history and projected balance so you can estimate potential financial consequences.

You should also distinguish IDR forgiveness from Public Service Loan Forgiveness (PSLF). Public Service Loan Forgiveness: Complete Guide explains the separate eligibility requirements and considerations for borrowers pursuing PSLF, which generally provides federal tax-free forgiveness under current federal rules.

If you expect a substantial balance to be forgiven, consider speaking with a qualified tax professional before the discharge occurs. That can help you understand whether you may need to prepare for additional taxes.

What if I can’t afford my IDR student loan payment?

If you cannot afford your current income-driven repayment plan payment, do not simply stop paying. Contact your federal loan servicer and request a review of your repayment options. If your financial circumstances have changed, you may be able to update your income information rather than waiting for your normal annual recertification. Reviewing good financial habits that build wealth can also help you adjust your broader money-management strategy when payments become difficult.

A job loss, salary reduction, or change in family circumstances can affect your payment calculation. Depending on your plan and circumstances, providing updated information may result in a lower required payment.

Keep documentation of your income and household changes. Respond promptly to communications from your servicer so you do not accidentally miss important deadlines.

If you are already struggling to make payments, review whether another eligible repayment plan provides better protection. You may also need to consider whether deferment or forbearance is appropriate.

Do not assume that an unaffordable bill will automatically become a zero-dollar payment. The result depends on your plan, income, loan type, and applicable federal rules.

Requesting Temporary Forbearance While Recalculating Payments

Forbearance can temporarily pause or reduce required federal student loan payments when you meet applicable requirements. It can be useful when you need short-term relief, but it should not automatically be your first choice.

Interest may continue to accrue during a forbearance period. That can increase your outstanding balance and raise your long-term repayment cost. For this reason, forbearance is generally better viewed as temporary financial relief rather than a permanent repayment strategy.

If your income has fallen, first determine whether updating your IDR information could produce a more sustainable monthly payment. Ask your servicer what documentation is required and whether your request can be processed before your next payment deadline.

Keep written records of your request and any confirmation you receive. Do not assume that submitting an application automatically stops your payment obligation.

If a temporary pause is necessary, understand its start and end dates. Resume payments or change plans promptly when the forbearance period ends.

Which loans are not eligible for IDR?

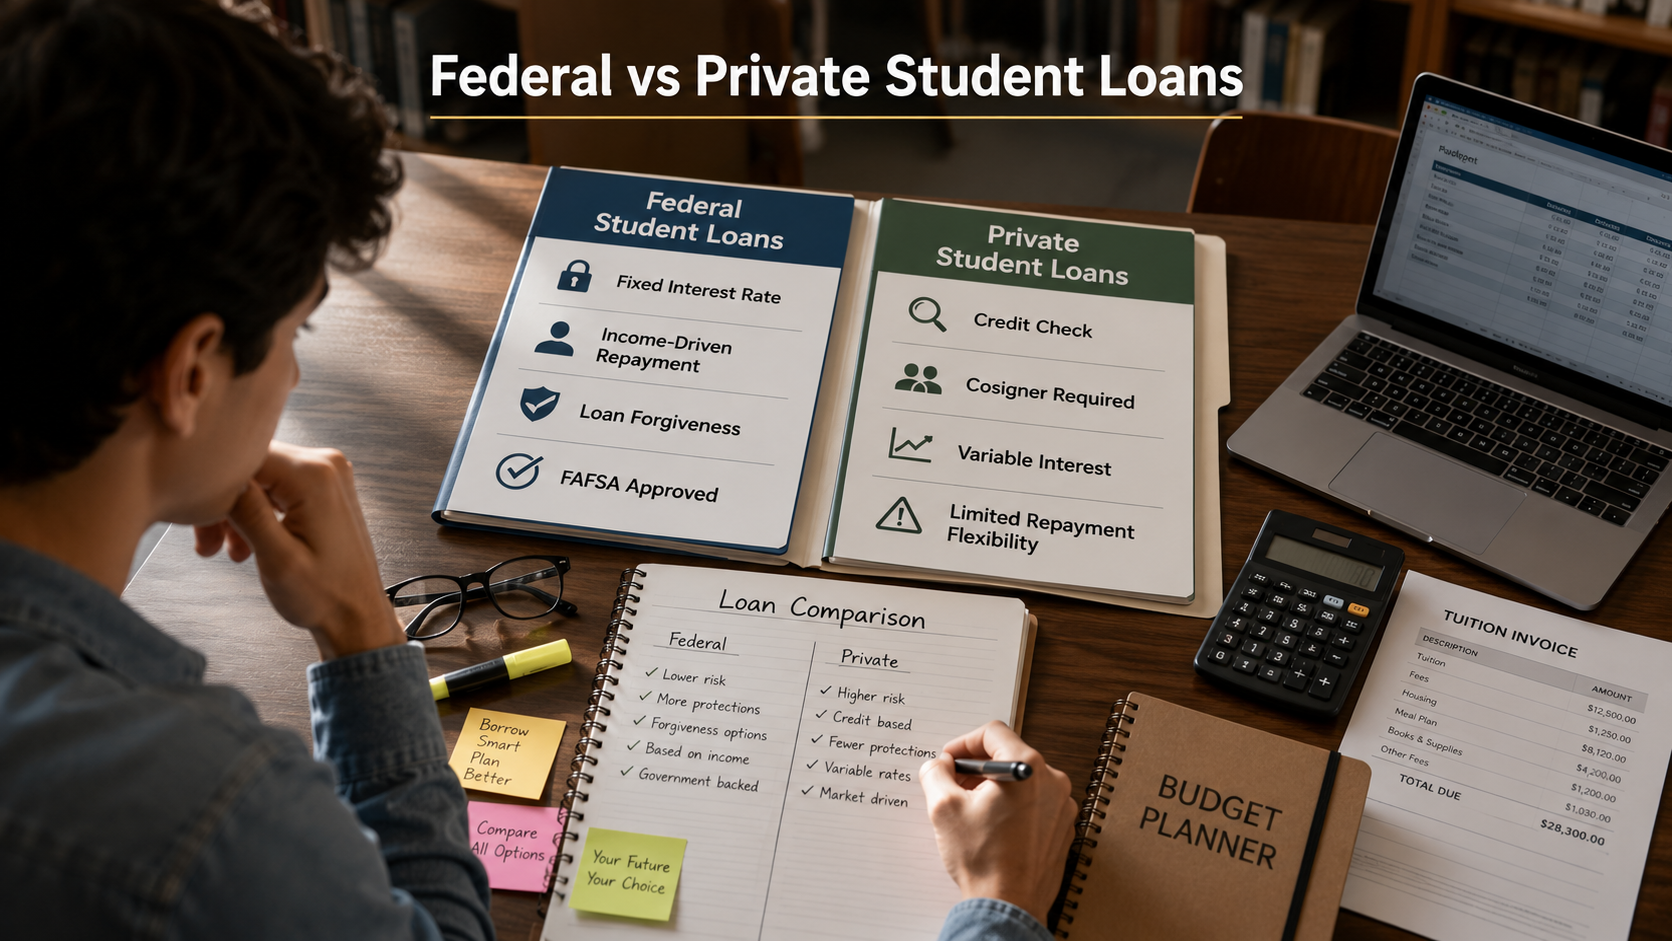
Not every student loan qualifies for an income-driven repayment plan. Private student loans are not eligible for federal IDR programs because they are issued by private lenders rather than the federal government.

Parent PLUS Loans also have significant restrictions. A Parent PLUS Loan cannot be directly repaid under the federal IDR plans. Certain older federal loans may require consolidation into a Direct Consolidation Loan before becoming eligible for specific repayment options.

Loan eligibility also depends on when the loan was disbursed. Federal rules changed substantially on July 1, 2026, so borrowers with older and newer loans may have different options.

Default status can also affect your ability to enroll in an IDR plan. You may need to resolve the default through an eligible federal process before accessing certain repayment options.

Because eligibility rules are complex, check your exact loan types through your StudentAid.gov account before consolidating or changing plans. Consolidation can affect interest, payment counts, and future repayment options.

Unlocking Access Through the Federal Direct Consolidation Process

Federal consolidation can sometimes make an otherwise ineligible loan eligible for a particular repayment option. However, consolidation is not a universal solution, and borrowers should understand the consequences before proceeding.

For example, certain older FFEL Program loans may need to be consolidated into a Direct Consolidation Loan to access specific IDR plans. Parent PLUS borrowers also face special rules, and consolidation does not automatically make every repayment plan available.

Timing matters as well. Federal rules changed on July 1, 2026, including restrictions affecting Parent PLUS loans and certain consolidation loans. A consolidation strategy that worked under older rules may no longer produce the same result.

Before consolidating, compare:

  • Your current interest rates.
  • Your existing qualifying payment history.
  • Your forgiveness eligibility.
  • The repayment plans available after consolidation.
  • Any capitalization or other financial consequences.

Check the federal consolidation and repayment tools before submitting an application. If forgiveness or PSLF is part of your strategy, verify how consolidation could affect your qualifying payment history.

Frequently Asked Questions

How often do I need to recertify my income-driven repayment plan?

You must recertify your income and family size every twelve months. Your loan servicer will notify you before the deadline arrives. Missing your annual recertification deadline can cause your monthly payments to jump back up to the standard ten-year repayment amount, and unpaid interest might capitalize onto your loan balance.

Can I switch between different income-driven repayment plans later?

Yes, you can change your repayment plan at any time through the Federal Student Aid portal, provided you qualify for the new program. Switching can help if your income changes significantly or if marriage alters your tax strategy. Check whether unpaid interest will capitalize before finalizing a plan switch.

Do zero-dollar payments count toward loan forgiveness?

Yes, a zero-dollar payment counts as an on-time monthly payment toward your 20- or 25-year cancellation requirement. If your calculated discretionary income yields a zero-dollar obligation, your servicer credits your account with a qualifying payment each month. This benefit keeps low-income borrowers progressing toward debt relief without spending money.

Does enrolling in an income-driven repayment plan hurt my credit score?

Enrolling in an IDR program does not harm your credit rating. Credit bureaus do not view income-adjusted payments negatively on consumer credit reports. In fact, lowering your required monthly payment helps prevent missed payments and delinquencies, which protects and strengthens your credit profile over time.

Conclusion

Managing higher education debt requires selecting a repayment path that reflects your actual earning capacity. Enrolling in an income-driven repayment plan provides strong financial safeguards by aligning monthly payments with discretionary cash flow. Whether your primary goal is finding immediate room in your budget, avoiding default, or pursuing debt forgiveness after two decades of payments, these federal frameworks give borrowers reliable options.

Take time to assess your specific loan types, career prospects, and household goals before committing to a strategy. Remember that you hold the legal right to update your income information whenever financial setbacks occur. Take control of your student loans today by reviewing your account details on the Federal Student Aid platform and finding the repayment structure that best supports your financial future.

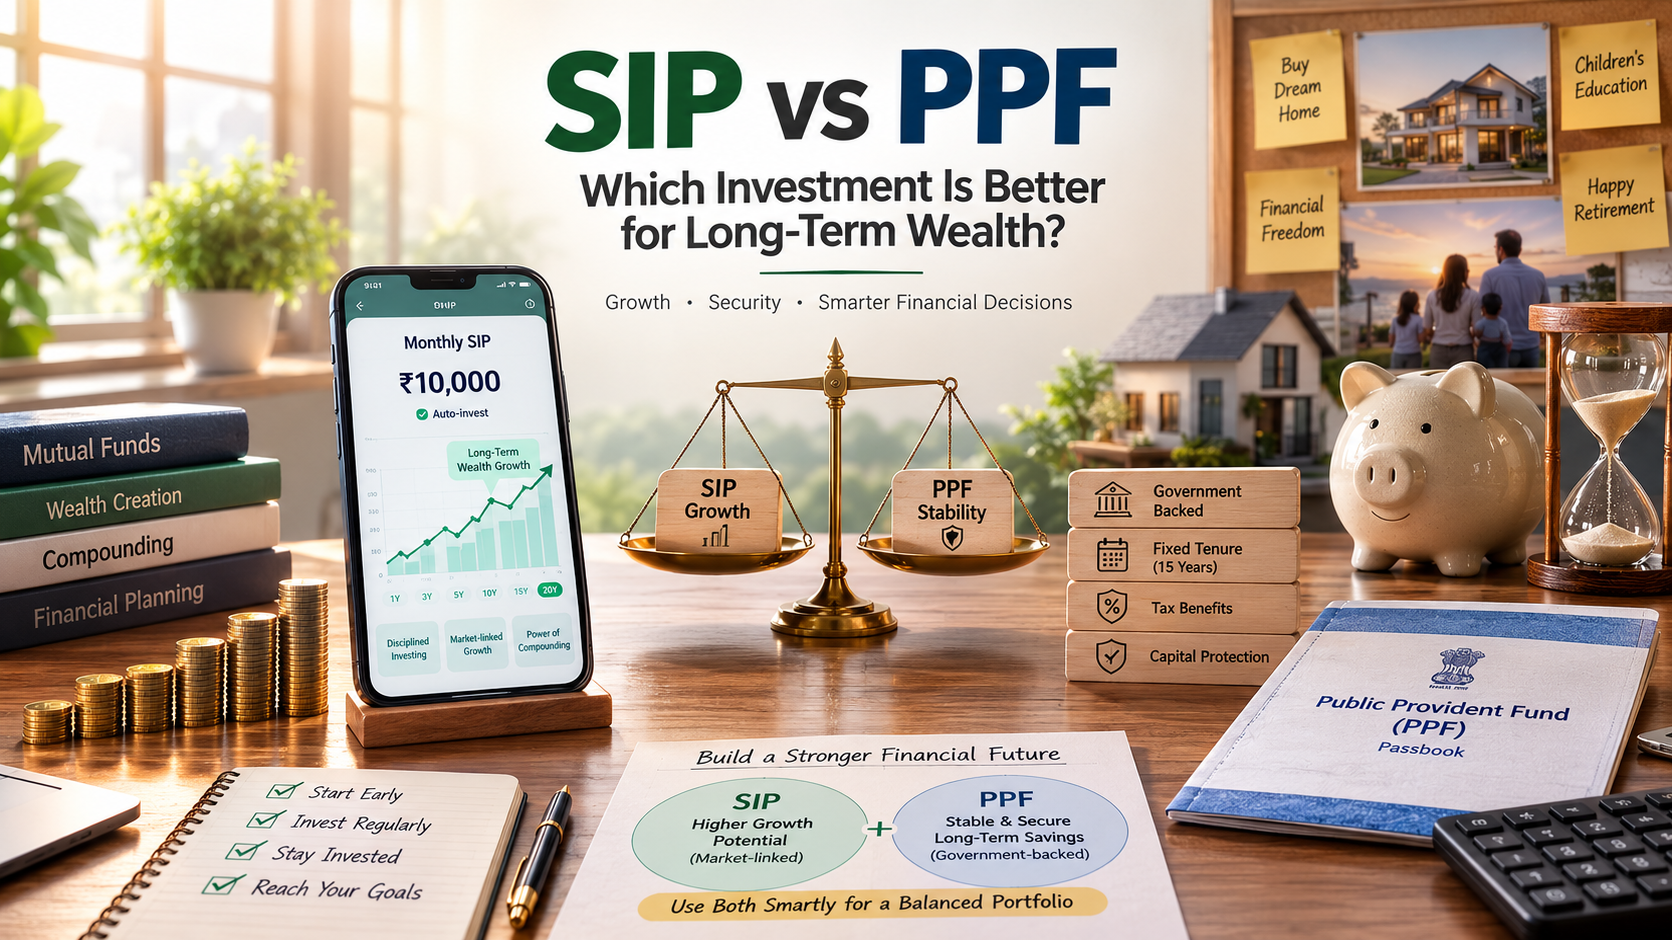
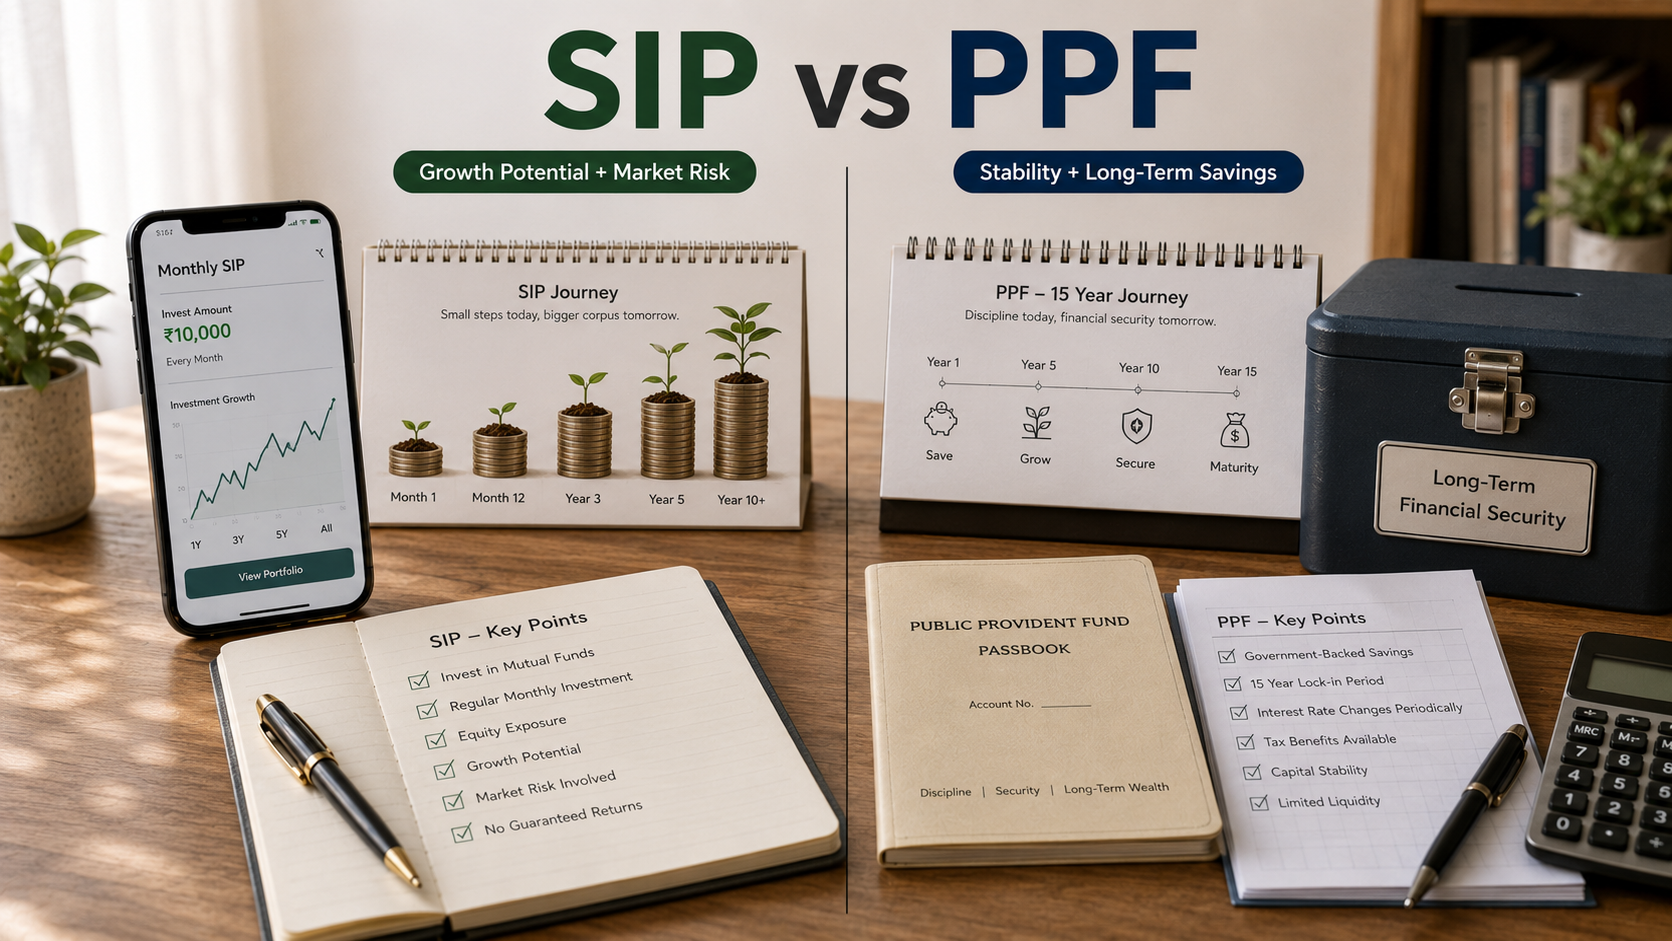
SIP vs PPF: Which Investment is Better for Long-Term Wealth?

SIP vs PPF: Which Investment Is Better for Long-Term Wealth?

Choosing between different investment options can feel difficult when your goal is long-term financial security. SIP vs PPF is a common comparison because the two options serve very different purposes. A Systematic Investment Plan (SIP) gives investors a disciplined way to invest in mutual funds, including equity-oriented funds with higher growth potential. The Securities and Exchange Board of India (SEBI) provides investor education resources on mutual funds and market-linked investments. The Public Provident Fund (PPF), meanwhile, offers government-backed savings with a fixed tenure and interest rate that is notified periodically. You can check the latest small-savings rates through the Department of Economic Affairs.

Neither option is automatically better for every investor. SIPs involve market risk, while PPF focuses on capital protection and tax-efficient savings. Your investment horizon, risk tolerance, financial goals, and need for liquidity should guide the decision. This comparison looks at PPF and SIP calculations, interest rules, investment timelines, and maturity options. It also explains when combining both approaches may make more sense than choosing only one.

How Much Will I Get If I Invest ₹10,000 Monthly in PPF for 15 Years?

Investing ₹10,000 every month in PPF means contributing ₹1.2 lakh each year. This stays within the current PPF annual deposit limit of ₹1.5 lakh. PPF has a 15-year maturity period, and the government currently lists the interest rate at 7.1% per year.

At a constant 7.1% rate, a ₹10,000 monthly contribution can grow to approximately ₹32.55 lakh over 15 years when deposits are made early enough to receive the applicable monthly interest. Your total contributions would be ₹18 lakh, while the remaining amount would come from interest. India Post provides a corresponding calculation for a ₹1,000 monthly contribution, which scales to approximately this amount.

The actual maturity value can differ if the government changes the PPF interest rate during the investment period. Therefore, ₹32.55 lakh should be treated as an illustration rather than a guaranteed 15-year projection.

Understanding PPF Interest Calculation

PPF interest is calculated each month using the lowest balance between the close of the fifth day and the end of that month. The interest is then credited to the account at the end of the financial year. This makes the timing of your deposits important.

If you invest your monthly contribution before the fifth day, that amount can generally qualify for interest for that month. Depositing later can reduce the interest earned for that month.

For a long-term PPF investor, this simple timing habit can improve the overall outcome. However, the interest rate itself is not permanently fixed for all 15 years. The government notifies small-savings interest rates periodically, so future returns may differ from a calculation using 7.1% throughout.

Which Type of Investment Is Best for the Long Term?

There is no single investment that is best for every long-term investor. The right choice depends on your financial goals, risk tolerance, investment horizon, and inflation expectations. SIPs can provide exposure to equity mutual funds, which may offer stronger long-term growth but also carry market risk. PPF provides a government-backed savings route with interest rates notified periodically. A useful comparison is risk vs return in investing, especially when deciding how much volatility you can accept.

For goals several decades away, equity investments can play an important role because they offer greater growth potential. However, returns are not guaranteed, and short-term market declines can be significant. PPF can provide stability and tax-efficient accumulation, but its fixed-income nature may offer less growth potential than equities over long periods.

A balanced approach can therefore be more practical for many investors. You might use PPF for the stable portion of your portfolio while using equity mutual fund SIPs for long-term growth. The right mix should reflect your ability to tolerate market fluctuations.

Balancing Risk and Inflation

Inflation gradually reduces the purchasing power of money. This makes inflation-adjusted returns and risk vs return in investing important when comparing PPF with equity-oriented mutual funds.

PPF offers stability and government-backed interest, but its future rate is subject to periodic government notifications. Equity investments can potentially deliver higher long-term returns, but they can also lose value during market downturns. There is no guaranteed return from an equity mutual fund SIP.

Consider the purpose of the money before choosing an investment. PPF may suit investors who value capital stability and predictable long-term saving. Equity SIPs may suit investors who can tolerate volatility and remain invested for many years.

Using both can reduce concentration risk. PPF can provide a stable component, while an equity SIP can target higher long-term growth. Your allocation should depend on your goal and risk capacity rather than simply choosing whichever option has the higher projected return.

How Much Is a ₹50,000 Monthly SIP for 5 Years?

Investing ₹50,000 per month in an SIP for five years means contributing ₹30 lakh in total. The final value depends entirely on the performance of the mutual fund and therefore cannot be guaranteed in advance.

For illustration, assuming an annualized return of 12% and monthly compounding, the investment could grow to approximately ₹40.8 lakh after 60 monthly investments. That would represent an estimated gain of about ₹10.8 lakh over the ₹30 lakh invested. The actual value could be considerably higher or lower because mutual fund returns fluctuate with market conditions.

Five years is also relatively short for an equity-focused investment. A major market correction near the end of the period could significantly reduce the final value. Investors should therefore avoid treating a 12% assumption as a promised SIP return.

Before choosing a fund, consider its investment strategy, risk level, costs, and suitability for your financial goal.

The Role of Rupee Cost Averaging

A monthly SIP automatically invests a fixed amount at regular intervals. When prices are lower, the same contribution purchases more mutual fund units. When prices are higher, it purchases fewer units.

This process is commonly associated with rupee cost averaging. It can reduce the pressure of trying to predict the perfect time to invest. However, it does not guarantee profits or protect investors from market losses.

SIP works best as a disciplined investing method rather than a return guarantee. The investor remains exposed to the performance of the underlying mutual fund. A poorly performing fund can still produce disappointing results despite regular investments.

For long-term investors, consistency can be more practical than attempting to predict short-term market movements. However, the investment should still be reviewed periodically. Changes may be necessary if the fund no longer matches your goals, risk tolerance, or asset-allocation strategy.

What Happens After 20 Years of a PPF Account?

A PPF account does not automatically have a 20-year maturity period. The standard PPF tenure lasts 15 years, after which you can close the account or extend it in five-year blocks. An investor can therefore continue the account beyond 15 years and reach a 20-year investment period through an extension.

After the initial maturity, you can withdraw the full balance and close the account. You can also keep the account open without making additional deposits. In that case, your existing balance continues to earn interest at the applicable PPF rate, and you can make one withdrawal during each financial year.

If you want to continue making contributions, you can extend the account for another five-year block by submitting Form-4 within one year of maturity. The extended account follows specific withdrawal rules, including a 60% limit during the five-year extension period.

Extension Options Without Fresh Deposits

After PPF maturity, you can retain the account without making additional contributions. The existing balance continues earning interest at the applicable PPF rate. You can also make one withdrawal in each financial year, subject to the rules governing the account.

This option can suit investors who want to preserve their accumulated PPF corpus while gradually accessing the money. It can also provide flexibility after retirement or when a major financial goal approaches.

There is an important distinction between continuing without deposits and extending with deposits. If you want to keep contributing after maturity, you must choose the contribution-based extension within the prescribed one-year period. The current PPF Scheme uses Form-4 for this extension.

If you continue the account without deposits for more than one year, you cannot later switch back to the contribution-based extension option. Therefore, investors should understand the consequences before choosing their post-maturity route.

Which Is Better, SIP or PPF?

The answer to SIP vs PPF depends on what you want the investment to accomplish. SIP is a method of investing in mutual funds and can provide equity exposure with higher long-term growth potential. PPF is a government-backed savings scheme designed for long-term, relatively stable accumulation. For another perspective, see this guide on SIP vs FD and which option is better.

For investors with a long horizon and higher risk tolerance, an equity-oriented SIP may offer greater wealth-creation potential. However, market returns are not guaranteed. PPF may be more suitable for investors who prioritize stability, tax-efficient savings, and government-backed interest.

PPF also has a 15-year initial tenure, while SIP investments generally offer greater flexibility because investors can change or stop contributions according to the mutual fund’s rules. However, SIP investors must accept market fluctuations and potential losses.

Rather than treating the choice as an either-or decision, many investors can use both. PPF can provide a stable foundation, while SIPs can provide growth exposure. The appropriate allocation depends on your financial goals, risk profile, and investment horizon.

Aligning Investments With Life Goals

The most useful way to compare SIP and PPF is to start with the financial goal, not the investment product. Different goals require different levels of growth, stability, and liquidity. Before deciding where to place your money, it can also help to review the best places to keep your savings safely.

For long-term wealth creation, an equity-oriented SIP may be suitable for investors who can tolerate market volatility. It can be useful for goals such as retirement or long-term wealth accumulation. PPF may work better for investors who want a government-backed component within their long-term savings.

Your time horizon also matters. Money needed in the near future should generally not depend heavily on volatile equity markets. Long-term money can tolerate more fluctuations because the investor has more time to recover from temporary declines.

A combination can therefore be useful. You could use PPF for stable, long-term savings and SIPs for potential growth. Review the allocation as your goals, income, and risk tolerance change.

Ultimately, the better choice in SIP vs PPF is the one that matches your financial objective rather than the one with the highest projected return.

Frequently Asked Questions

Can I Withdraw Money From a PPF Account Before the 15-Year Maturity?

Yes, PPF allows partial withdrawals from the seventh financial year, subject to the withdrawal limits and conditions prescribed under the PPF rules. The withdrawal amount is restricted based on the eligible balance in the account. Before the seventh year, investors may also use the loan facility against their PPF balance. This makes PPF useful for long-term savings with limited liquidity.

Are SIP Returns Guaranteed by the Government or Financial Institutions?

No. SIP returns are not guaranteed because an SIP is simply a method of investing regularly in mutual funds. The value of your investment depends on the underlying securities and market conditions. This is an important distinction in any SIP vs PPF comparison. Unlike PPF, mutual fund investments can rise or fall, and investors can experience losses.

Can I Invest in Both SIP and PPF Simultaneously?

Yes, you can invest in both SIP and PPF at the same time. They serve different purposes within a financial plan. An equity mutual fund SIP can provide long-term growth potential, while PPF can add stability and government-backed savings. In an SIP vs PPF strategy, combining both can help diversify your investments instead of depending entirely on one option.

What Tax Benefits Do SIP and PPF Offer Investors?

PPF contributions qualify for a deduction under Section 80C, subject to the applicable overall limit. PPF interest and eligible maturity proceeds are generally tax-exempt under current rules. A regular mutual fund SIP does not receive a Section 80C deduction. However, SIP investments in ELSS mutual funds can qualify for Section 80C benefits. Mutual fund gains remain subject to applicable capital gains tax rules.

Conclusion

The SIP vs PPF decision should depend on your financial goals, investment horizon, and ability to handle risk. SIPs can provide greater long-term growth potential through market-linked mutual funds, but market performance determines your returns. PPF offers government-backed savings and greater stability, although it may deliver lower long-term growth than equity investments.

For investors comfortable with market fluctuations, an equity SIP can support long-term wealth creation and retirement planning. PPF can complement that strategy by providing a stable, tax-efficient component. Rather than asking which option is universally better, consider SIP vs FD and which is better for your overall savings and investment goals.

The right SIP vs PPF strategy may involve using both. SIP can target growth, while PPF can provide stability and disciplined long-term savings. Review your investments periodically as your income, goals, and risk tolerance change. Always consider current tax rules and scheme regulations before making investment decisions.

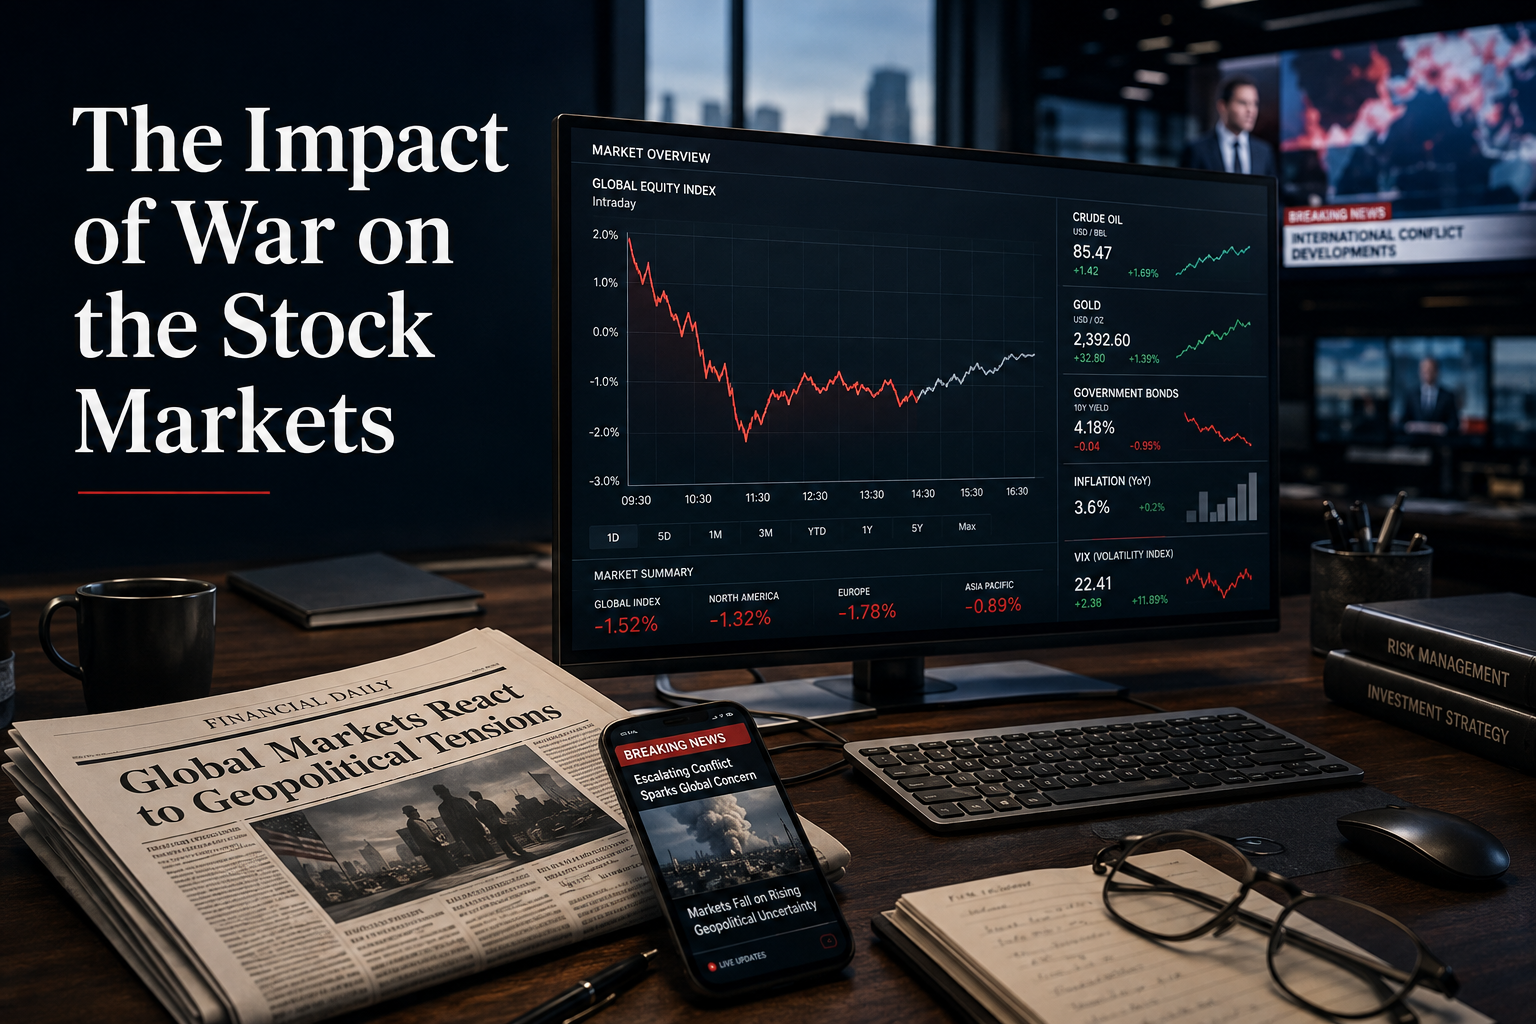
The Impact of War on the Stock Markets & Investor Guide

The Impact of War on the Stock Markets—What Investors Need To Know

Geopolitical conflicts can send shockwaves through the global financial system. Understanding the impact of war on the stock markets helps investors prepare for sudden volatility and changing economic conditions. Markets often react quickly to military escalations because investors must reassess risk, growth prospects, inflation, and corporate earnings.

During periods of conflict, investors may move capital toward perceived safe-haven assets. These can include gold, the U.S. dollar, and government bonds. Equity prices can therefore move sharply within hours of major developments. For historical information about market stability and investor protection during crises, investors can review resources from the U.S. Securities and Exchange Commission.

This article explains what happens to the stock market during war, which sectors may be most vulnerable, and why some stocks can rise. It also examines whether markets always fall and how investors can understand these movements without reacting emotionally.

What will happen to the stock market if a war happens?

When a war begins, stock markets often experience an immediate rise in volatility. Investors face uncertainty about economic growth, inflation, interest rates, trade, and corporate profits. That uncertainty can trigger rapid selling, particularly when the conflict is unexpected.

Investors may also shift money toward assets they consider safer. Gold, government bonds, and major currencies can attract additional demand. At the same time, major stock indexes may fall as investors reduce exposure to riskier assets.

The initial reaction does not always predict the market’s longer-term direction. Once investors understand the scale and economic consequences of a conflict, attention often returns to earnings and economic data.

Several factors can influence the market response:

  • Conflict duration: Longer wars can create deeper economic disruption.
  • Geographic exposure: Markets react differently when conflict affects major economies.
  • Commodity supplies: Disruptions can push energy and food prices higher.
  • Government policy: Fiscal and monetary responses can influence recovery.
  • Corporate exposure: Companies dependent on affected regions may face greater risks.

Initial Market Reactions and Panic Selling

Initial market declines are often driven by fear and uncertainty rather than confirmed changes in corporate fundamentals. Portfolio managers may reduce risk quickly when military developments create an unpredictable environment. This can produce sharp movements in major indexes and individual stocks.

Consumer discretionary and technology companies can face selling pressure because investors often become more cautious about future spending and economic growth. Companies with high valuations may also become vulnerable when investors suddenly prioritize stability over growth.

However, panic selling does not necessarily continue indefinitely. After the first shock, markets often begin evaluating the conflict through economic data rather than headlines alone. Investors may assess corporate earnings, inflation, interest rates, commodity prices, and consumer demand.

The key point is that war does not create one predictable stock-market outcome. The severity and duration of the market reaction depend on the conflict’s economic consequences. A contained conflict may produce a short-lived decline, while a prolonged conflict can create sustained pressure on earnings and valuations.

What are the stocks affected by war?

The stocks most affected by war are usually those with direct exposure to disrupted supply chains, higher commodity prices, weaker consumer demand, or affected geographic markets. The impact can differ significantly between companies, even within the same industry.

Airlines, shipping companies, and travel businesses may face immediate pressure when fuel costs rise or airspace and trade routes become restricted. Higher operating expenses can reduce margins when companies cannot quickly increase prices.

Consumer discretionary businesses may also struggle when inflation reduces household purchasing power. Consumers often delay spending on non-essential products when economic uncertainty increases.

Automotive manufacturers can face additional challenges when conflicts disrupt supplies of metals, semiconductors, energy, or specialized components. These disruptions can delay production and increase manufacturing costs.

Investors should therefore examine a company’s specific exposure rather than assuming an entire sector will move in one direction. Important factors include:

  • Supply-chain dependence
  • Energy and raw-material costs
  • International revenue exposure
  • Pricing power
  • Debt levels
  • Inventory and production flexibility

Supply Chain Disruptions and Sector Vulnerability

War can disrupt global supply chains when ports, trade routes, production facilities, or transportation networks become unavailable. Companies that depend heavily on a small number of suppliers can become especially vulnerable. Investors can also learn more about how supply chain disruptions affect local grocery prices to understand how these disruptions can reach consumers.

Manufacturers may struggle to obtain critical raw materials or components. Depending on the conflict, shortages can affect commodities such as crude oil, natural gas, industrial metals, and agricultural products. Some specialized materials can also become harder to source when production is concentrated in affected regions.

Higher input costs can reduce corporate profit margins. Companies with strong pricing power may pass some costs to customers, but weaker businesses may have limited options. Investors may then lower their expectations for future earnings. Understanding modern asset allocation strategies for beginners can also help investors consider how to spread exposure across different asset classes during uncertain market conditions.

Supply-chain exposure is therefore an important factor when evaluating stocks affected by war. A company with diversified suppliers and multiple production locations may withstand disruption better than a company dependent on one region.

The effect also depends on how long the disruption lasts. Temporary shortages may create short-term volatility, while prolonged disruptions can force companies to redesign supply chains and make costly investments.

Do stock markets drop during war?

Stock markets often fall when a war begins, but they do not automatically decline throughout the entire conflict. The initial reaction usually reflects uncertainty and changing expectations about economic growth, inflation, interest rates, and corporate earnings.

Investors may sell stocks when they fear a recession or major disruption to global trade. Companies exposed to affected regions can experience larger declines. Growth stocks may also face pressure when investors move toward assets perceived as safer.

However, the historical response to wars varies considerably. Some conflicts produce sharp but temporary declines, while others have broader economic consequences. The market response depends on the conflict’s location, duration, scale, and effect on energy supplies and financial conditions.

Investors should also distinguish between a short-term market shock and a prolonged bear market. A sudden decline does not necessarily mean that stock prices will continue falling for months or years. Understanding risk vs return in investing can help investors evaluate whether short-term volatility is consistent with their overall investment strategy.

Instead, investors should monitor:

  • Corporate earnings
  • Inflation and interest rates
  • Commodity prices
  • Consumer spending
  • Economic growth
  • Government intervention

Historical Context of Market Corrections

Historical market behavior shows that stock prices can recover after an initial geopolitical shock. However, recovery is not guaranteed, and timing varies significantly between conflicts. Investors looking for ways to protect capital during uncertain periods can also review the best places to keep your savings safely.

Markets often begin looking beyond immediate headlines once investors can estimate the economic consequences more clearly. If companies continue generating earnings and financial conditions remain stable, equity prices can stabilize even while a conflict continues.

The opposite can also occur. A prolonged war may create persistent inflation, energy shortages, weaker trade, reduced investment, or recession. These effects can keep pressure on corporate profits and valuations for much longer.

This distinction matters when evaluating the impact of war on the stock markets. Investors should not assume that every military conflict will produce the same market pattern.

The broader economic environment also matters. A war occurring during an already fragile economy may create a larger market response than the same event during strong economic growth.

Therefore, historical examples provide useful context, but they should not be treated as precise forecasts. Each conflict has different economic and financial conditions.

Do stock prices go up during war?

Although broad stock indexes can decline when war begins, some individual stocks and sectors may rise. Markets do not treat every company equally because different businesses respond differently to higher demand, commodity prices, and government spending.

Defense companies can benefit when governments increase military budgets. Cybersecurity businesses may also receive additional demand as governments and companies strengthen digital defenses against cyberattacks.

Energy producers can benefit when conflicts threaten oil and gas supplies. Higher commodity prices can increase revenue and, in some cases, improve profit margins for producers.

However, rising share prices are not guaranteed. Investors may already anticipate higher defense or energy demand before a conflict begins. If expectations become excessive, stock prices can fall even when company fundamentals remain strong.

The key is to distinguish between short-term market momentum and sustainable earnings growth. A company may experience a temporary rally based on headlines, while its long-term performance depends on contracts, production capacity, costs, debt, and future demand.

War can therefore create both winners and losers in the stock market. The outcome depends on each company’s business model and exposure.

The Role of Increased Defense Spending

Governments often increase defense spending when national security risks rise. This can create additional contracts for aerospace, defense, technology, logistics, and cybersecurity companies.

Defense contractors with established government relationships may benefit from increased procurement. However, investors should not assume that every defense company will experience the same gains. Contract timing, production capacity, costs, and government budgets can all influence financial results.

Cybersecurity companies can also attract attention during conflicts. Modern warfare increasingly involves digital attacks against government systems, businesses, communications networks, and critical infrastructure. This can increase demand for security software and related services.

Still, higher government spending does not immediately translate into higher profits. Companies must convert contracts into revenue while managing labor, materials, manufacturing capacity, and other costs.

Investors should therefore examine actual financial performance rather than relying solely on headlines. Important indicators include order backlogs, revenue growth, operating margins, cash flow, and contract awards.

The broader lesson is simple: war can increase demand for certain products, but demand alone does not guarantee strong shareholder returns.

What stocks go up when war happens?

Certain industries can benefit when geopolitical conflict increases demand for defense products or pushes commodity prices higher. Defense contractors are often among the most closely watched stocks because governments may increase military procurement.

Energy companies can also benefit when conflicts threaten oil and natural gas supplies. Higher commodity prices can increase revenue for producers, although the effect varies by company and production costs.

Agricultural businesses may gain when conflicts disrupt grain production or exports. Higher food commodity prices can increase revenue for some producers and agribusiness companies. However, higher input costs can offset those benefits for other businesses. Investors can also explore climate-smart agriculture to understand approaches that aim to strengthen agricultural resilience under changing environmental conditions.

Precious metals can also attract investors during periods of geopolitical uncertainty. Gold-related companies may benefit when gold prices rise, although mining stocks remain exposed to operating costs and broader market conditions.

Potential beneficiaries can therefore include:

  • Defense and aerospace companies
  • Cybersecurity firms
  • Oil and natural gas producers
  • Agribusiness companies
  • Commodity producers
  • Precious metal miners

These sectors should not be treated as automatic winners. Valuations, existing expectations, production costs, government policy, and the conflict’s actual economic impact can all change the outcome.

Energy and Commodity Stock Surges

Energy markets can react quickly when a conflict threatens major production areas, pipelines, shipping routes, or export infrastructure. Even the risk of supply disruption can push oil and natural gas prices higher.

Energy producers may benefit from stronger commodity prices because higher selling prices can increase revenue and operating profits. However, not every energy company benefits equally. Producers with high costs, heavy debt, or limited production capacity may see smaller gains.

Agricultural commodities can respond similarly. Conflicts affecting major farming regions or export routes can reduce available supplies and increase global food prices. Agribusiness companies may benefit from stronger commodity prices, but higher fertilizer, fuel, and transportation costs can reduce those gains. These pressures also highlight the importance of understanding climate change food security, impacts and solutions when considering risks to agricultural supply.

Investors should therefore avoid assuming that war automatically makes energy or commodity stocks profitable investments. Commodity prices can reverse quickly when supply fears ease or demand weakens.

A better approach is to examine the company’s underlying financial position. Revenue exposure, production costs, debt, cash flow, dividends, and valuation all matter when assessing potential beneficiaries of geopolitical disruption.

Frequently Asked Questions

How long does it usually take for stock markets to recover after a war starts?

There is no fixed recovery period because every conflict creates different economic conditions. The Impact of War on the Stock Markets can range from a brief correction to a prolonged downturn. Markets may stabilize within weeks or months if economic damage remains limited. Recovery can take much longer when war causes sustained inflation, recession, energy shortages, or major supply-chain disruptions.

Should I sell all my stocks when a war breaks out?

Selling all your stocks during a sudden market decline can turn temporary losses into permanent ones. The Impact of War on the Stock Markets can create sharp short-term volatility, but timing the exact market bottom is extremely difficult. Instead, investors should review their risk tolerance, diversification, investment horizon, and individual holdings. A disciplined strategy is usually more reliable than making emotional decisions based on breaking news.
Are gold and bonds always safe investments during a wartime crisis?

Gold and government bonds are often viewed as defensive assets during geopolitical crises, but neither is guaranteed to rise. The Impact of War on the Stock Markets can also influence interest rates, inflation, currency values, and investor demand for bonds. Gold may benefit from uncertainty and inflation concerns, while bonds can face pressure when interest rates or inflation expectations increase. Their performance depends on the broader economic environment.

How does inflation during wartime impact my existing stock portfolio?

Wartime inflation can increase the cost of energy, raw materials, transportation, and labor. These higher expenses can reduce corporate profit margins, especially when companies lack pricing power. The Impact of War on the Stock Markets may therefore be stronger for businesses with high operating costs or fragile supply chains. Companies in energy, commodities, or defense may benefit from higher demand, but diversification remains important because sector performance can vary.

Conclusion

Understanding the impact of war on the stock markets helps investors respond to uncertainty without making rushed decisions. Conflicts can cause sharp declines, higher inflation, and major sector shifts. However, markets can also recover as investors adjust to new conditions. A diversified portfolio, realistic risk assessment, and long-term focus can help investors manage volatility while avoiding emotionally driven decisions during geopolitical crises.

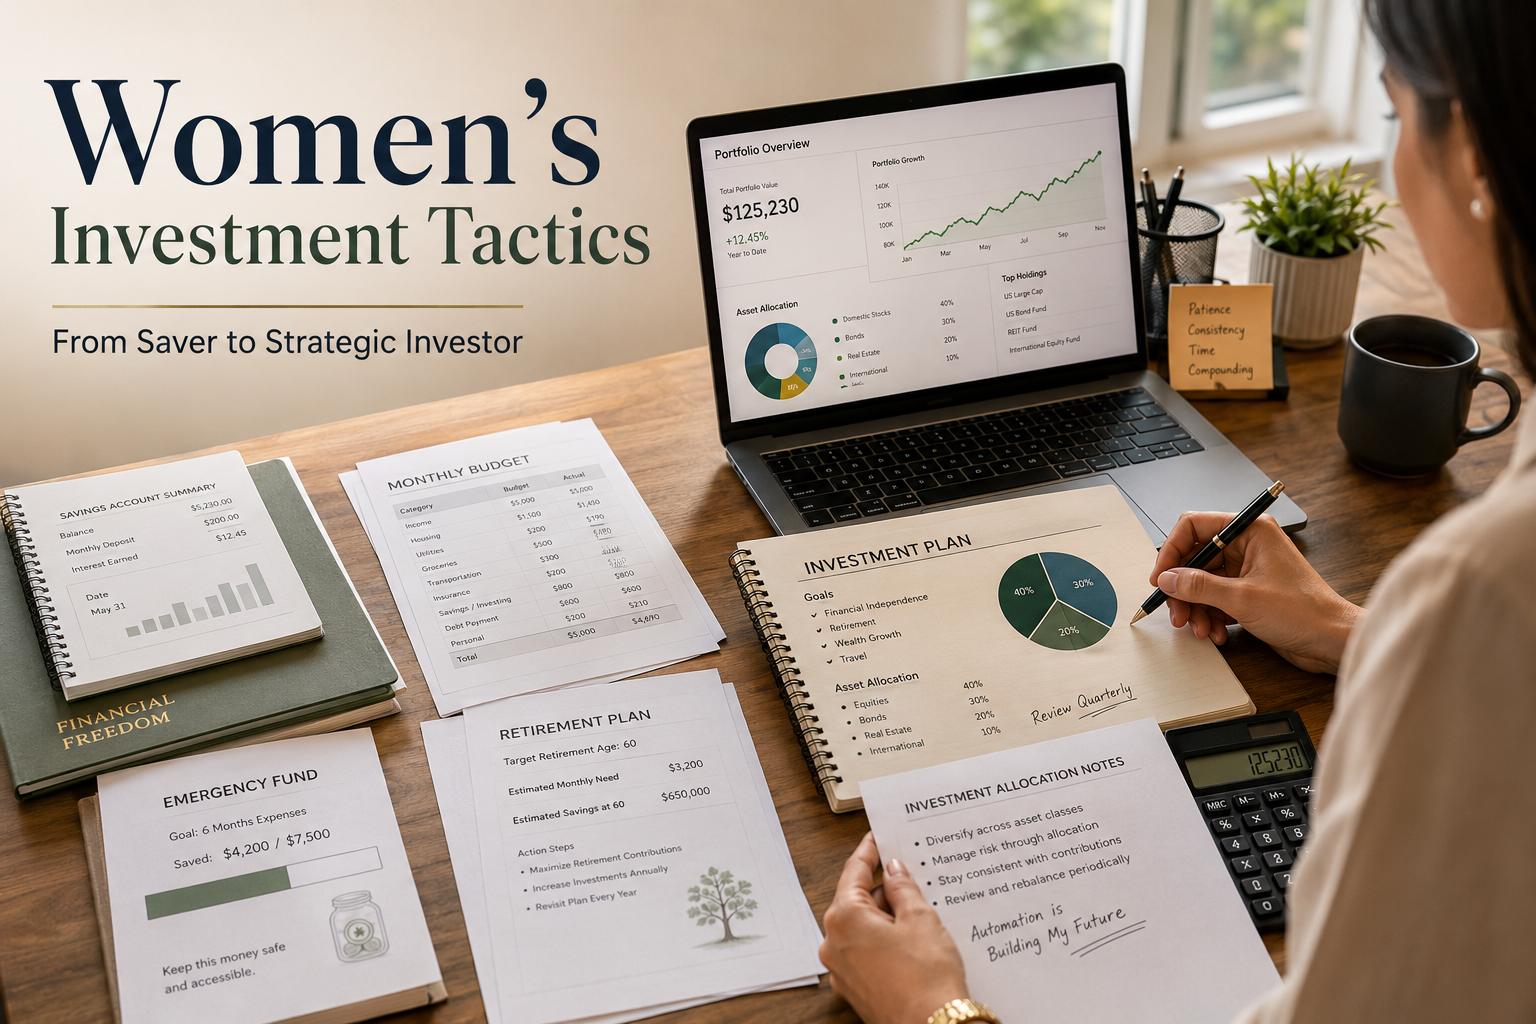
Women’s Investment Tactics: Saver to Strategic Investor

Women’s Investment Tactics: From Saver to Strategic Investor

As financial landscapes evolve, mastering women’s investment tactics can support long-term wealth building and financial independence, with organizations like Bank of America offering research that highlights how structured planning closes persistent wealth gaps. Many women are disciplined savers, yet traditional savings accounts may struggle to keep pace with inflation. Moving from saving alone to strategic investing can put idle cash to work and create opportunities for long-term growth.

Financial planning can help investors close wealth gaps, manage risk, and prepare for future goals. This guide explores practical frameworks, investment principles, and money-management strategies. It also answers common questions about budgeting rules, successful female investors, and financial advisors.

The goal is not to follow every rule blindly. Instead, use these ideas as starting points for creating an investment strategy that matches your income, goals, time horizon, and risk tolerance.

What is the 7 7 7 rule for money?

The 7 7 7 rule for money is not a universally standardized financial rule. Different financial educators may use the term to describe different approaches to saving, investing, or long-term planning. Therefore, investors should confirm which version a particular source means before applying it to their finances.

One useful way to interpret the concept is as a framework for balancing financial priorities across different time horizons. Emergency savings can protect against unexpected expenses. Medium-term savings can support goals such as buying property, starting a business, or funding education. Long-term investments can support retirement and wealth accumulation. For a broader framework, investment ideas and tips for financial success can help investors evaluate different ways to put these priorities into practice.

For women developing effective women’s investment tactics, separating these goals can make financial decisions clearer. It also reduces the risk of investing money needed for short-term expenses.

The key principle is simple: match each dollar to its purpose and time horizon. This approach can provide structure without treating one formula as suitable for everyone.

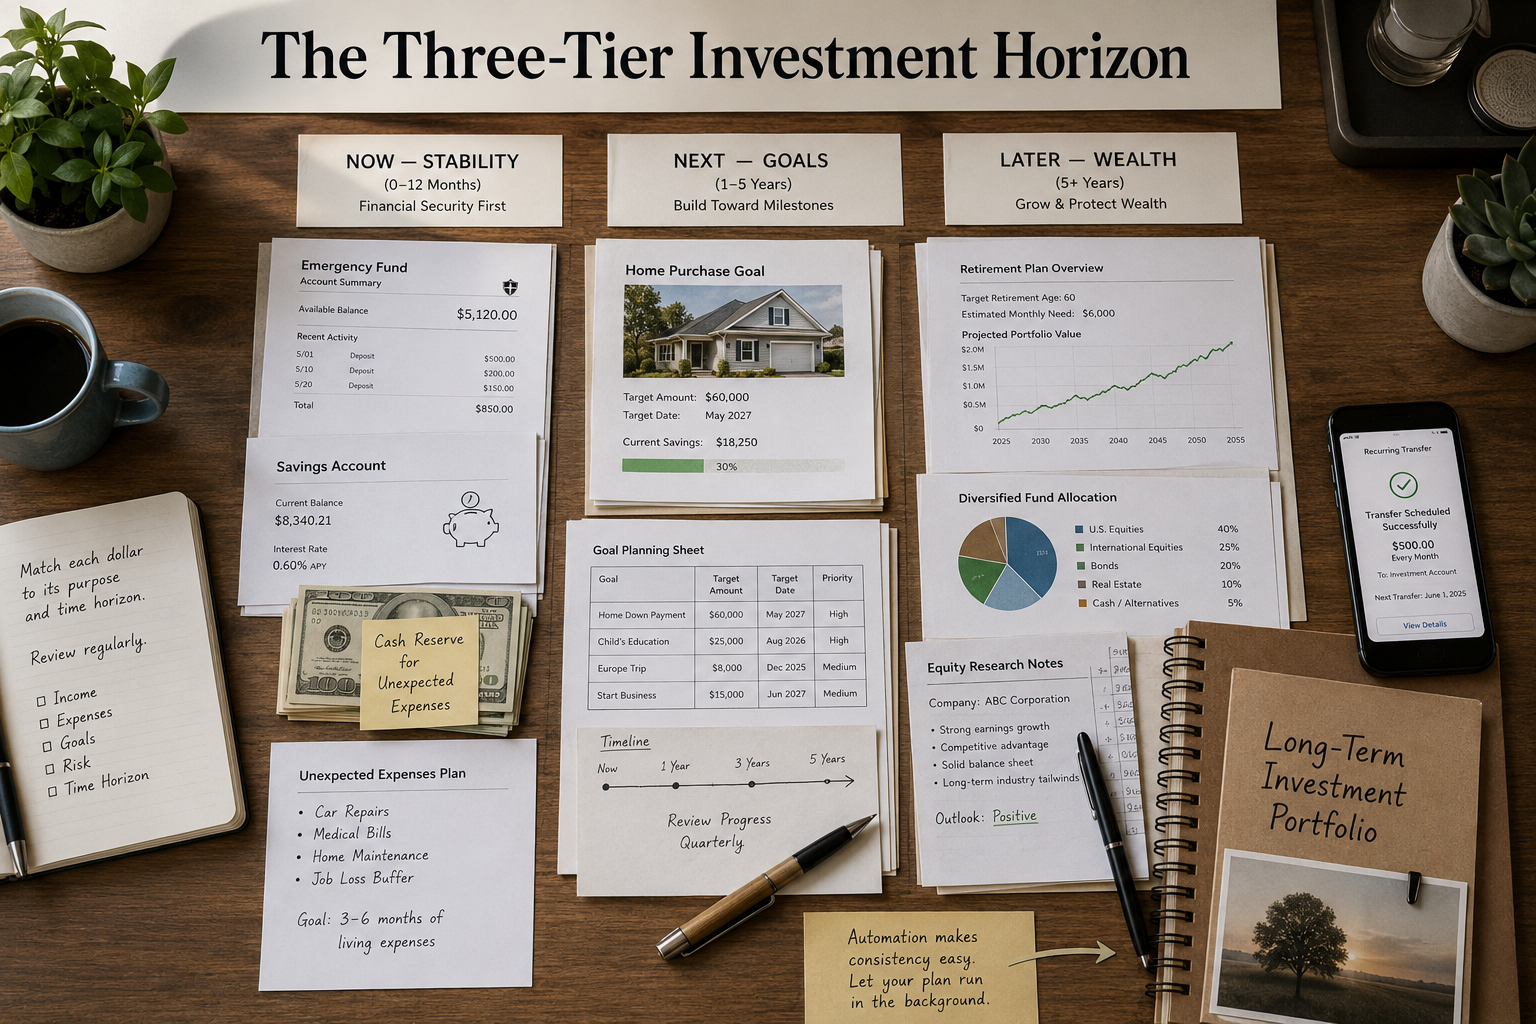
Applying the Three-Tier Horizon Framework

A three-tier horizon framework can help investors organize money according to when they expect to need it.

The first tier focuses on financial stability. Build an emergency reserve before taking unnecessary investment risks. Keep this money accessible and separate from long-term investments. Choosing where to hold this reserve can also be informed by the best places to keep your savings safely.

The second tier covers medium-term objectives. These may include a home purchase, education, travel, or a business venture. The appropriate investments depend on the goal’s timeline and risk level.

The third tier focuses on long-term wealth creation. Retirement accounts, diversified funds, equities, and other suitable long-term assets can play a role here.

Automation can make this structure easier to maintain. Set recurring transfers after receiving income instead of relying on motivation each month.

Most importantly, review the framework regularly. Income, expenses, family responsibilities, and financial goals can change over time. Effective women’s investment tactics should therefore remain flexible rather than becoming rigid rules that no longer fit your circumstances.

What are the 5 P’s of investing?

The 5 P’s of investing are not a universally defined investment standard. Different financial educators use different versions of this mnemonic. One practical interpretation includes Planning, Patience, Persistence, Portfolio diversification, and Professional guidance.

Planning means defining financial goals before choosing investments. Clear objectives can help determine how much to invest and how long the money can remain invested. Patience helps investors avoid emotional decisions during normal market volatility. Understanding risk versus return in investing can also help beginners evaluate whether a potential investment matches their objectives and tolerance for uncertainty.

Persistence means continuing suitable contributions over time. Regular investing can reduce the temptation to make decisions based on short-term market movements. Portfolio diversification spreads exposure across different assets, sectors, regions, or investment types.

Professional guidance can also help when financial decisions become complicated. An adviser may assist with taxes, retirement planning, estate considerations, or portfolio construction.

However, professional advice is not automatically necessary for every investor. The most suitable approach depends on financial complexity, knowledge, costs, and personal circumstances. These principles can support women’s investment tactics, but they should complement, not replace, proper financial planning and risk assessment.

Mastering Patience and Diversification

Patience is one of the hardest investing principles to maintain because markets can change sharply over short periods. A temporary decline does not automatically mean that a long-term investment strategy has failed. Selling purely because of fear can turn temporary losses into permanent ones.
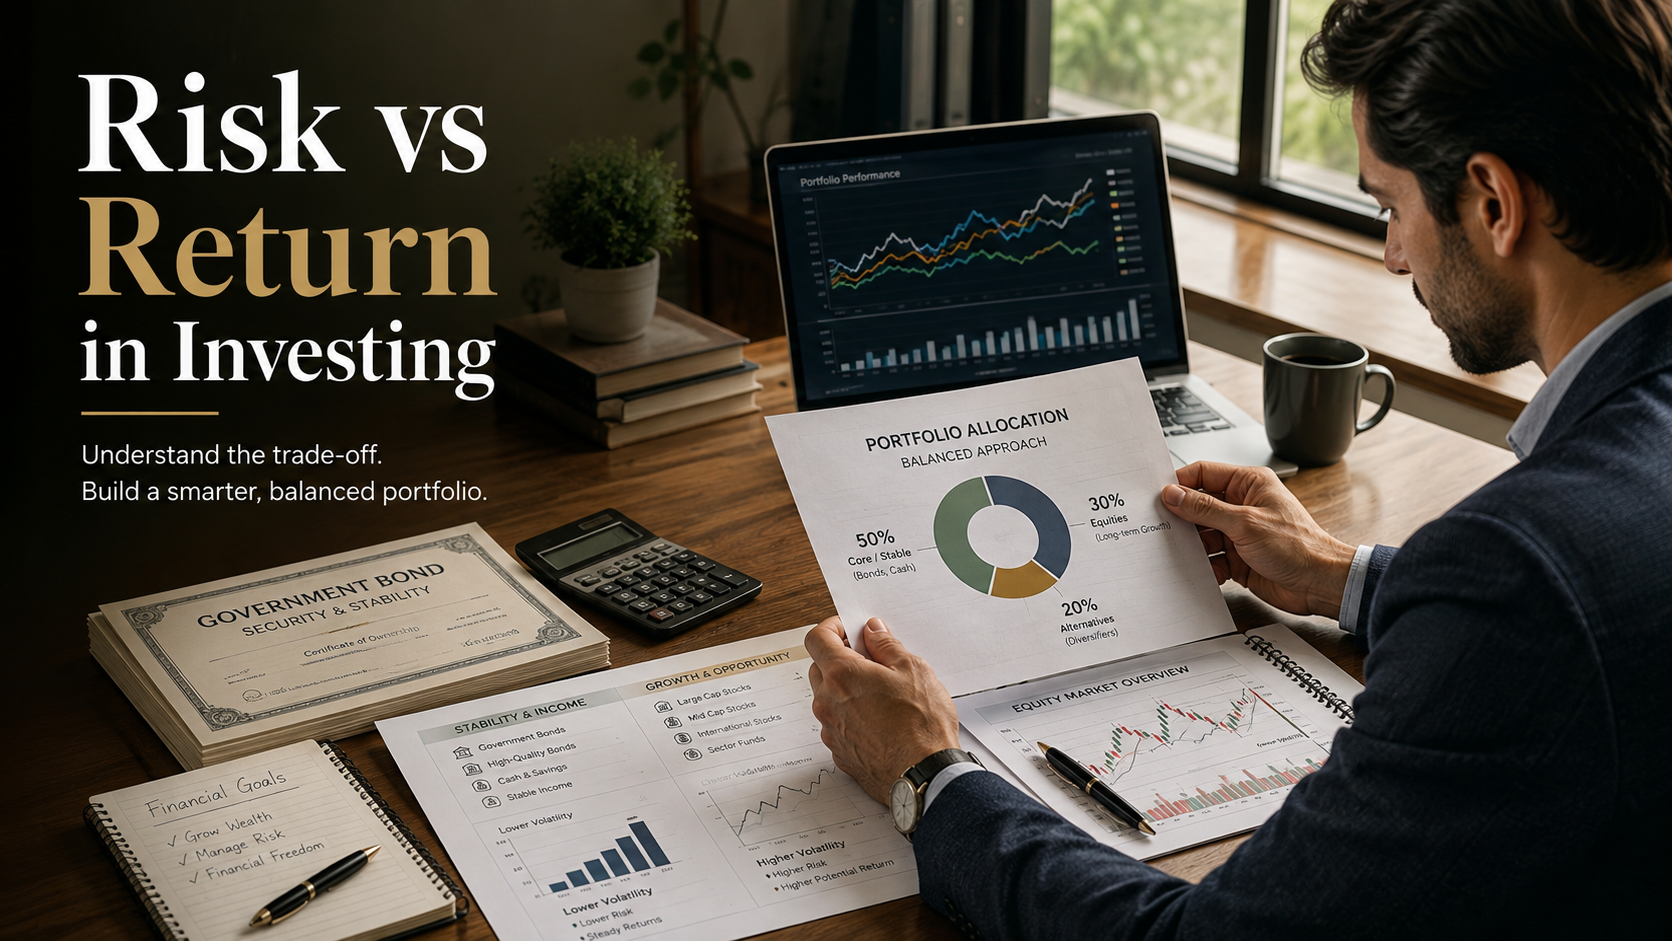
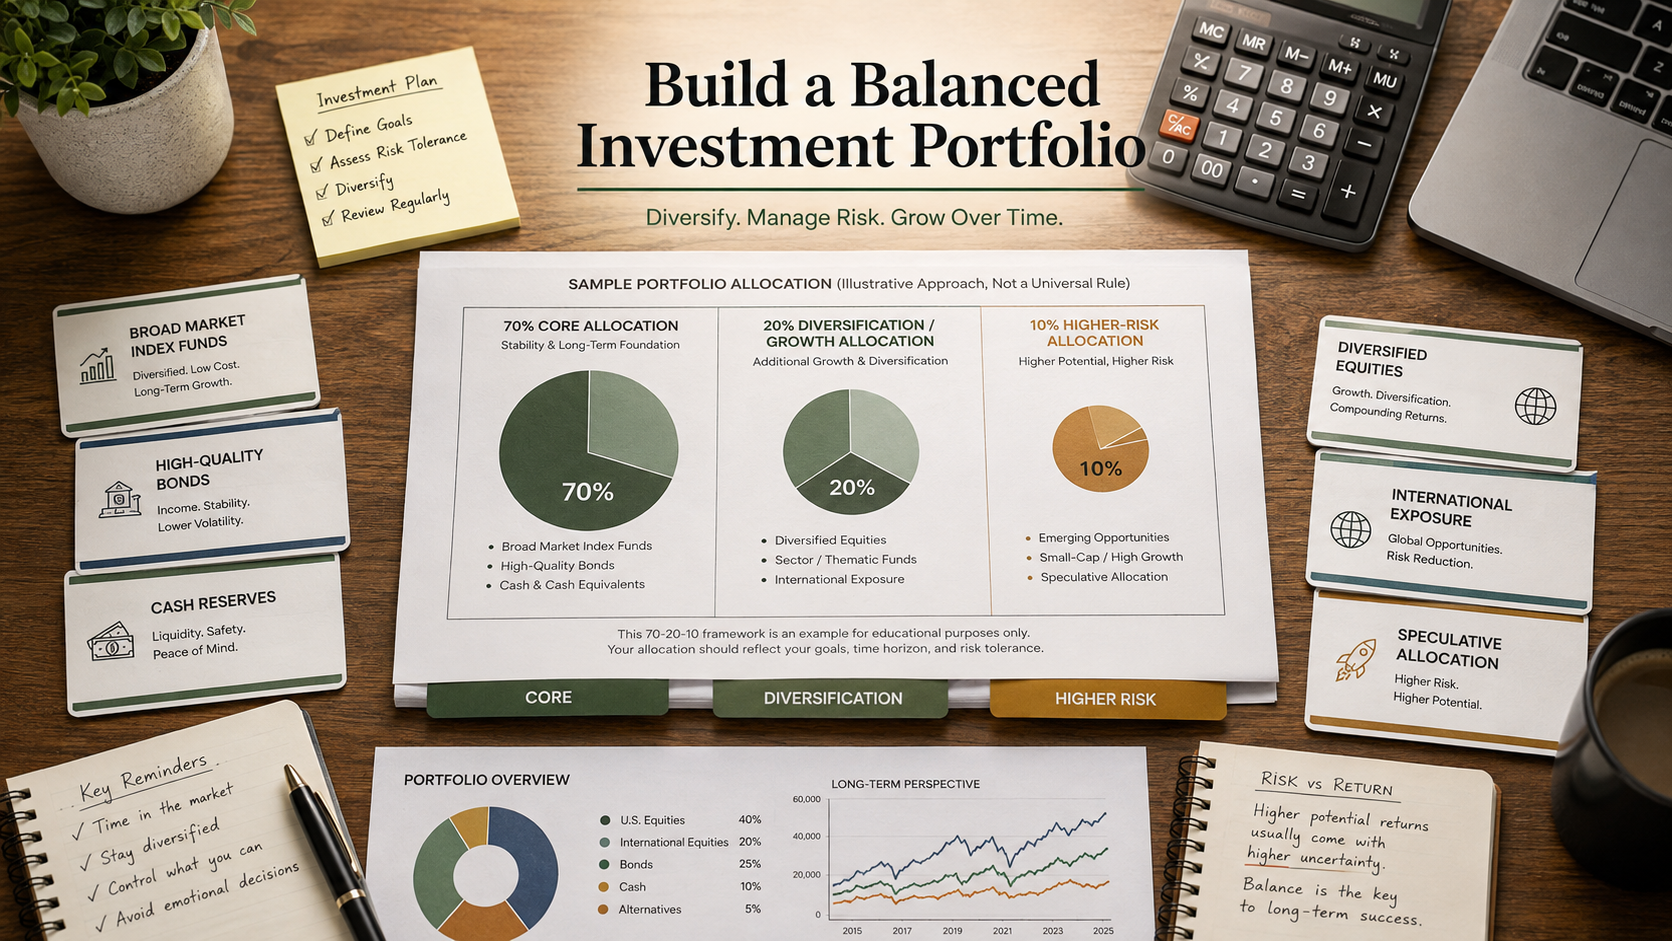
Diversification provides another important layer of risk management. Instead of concentrating wealth in one company or sector, investors can consider exposure across different assets and markets. Depending on individual circumstances, these may include equities, bonds, property-related investments, and other diversified vehicles. Investors can also explore modern asset allocation strategies for beginners when deciding how to distribute investments across asset classes.

Diversification does not eliminate risk. It also cannot guarantee profits or prevent losses during a broad market decline. Its purpose is to reduce dependence on one particular investment or economic outcome.

For women developing women’s investment tactics, combining patience with sensible diversification can create a more resilient approach. Investors should also review their portfolio periodically. Rebalancing may be appropriate when asset allocations move significantly away from their intended levels or financial goals change.

Who is the most successful female investor?

There is no objective answer to the question of who is the most successful female investor. Success can be measured through different factors, including investment returns, assets managed, business impact, longevity, or influence on financial markets.

Cathie Wood, founder and CEO of ARK Invest, is one prominent example. She became widely known for focusing on disruptive innovation and companies involved in areas such as artificial intelligence, robotics, and genomic technologies. Her investment approach has attracted substantial attention, especially during periods when growth-oriented technology stocks performed strongly.

However, her strategy also illustrates why investors should distinguish between conviction and concentration. High-growth themes can experience significant volatility and substantial declines. Past performance does not guarantee future results.
The broader lesson is more useful than identifying one winner. Successful investing requires research, a clear thesis, risk management, and the ability to tolerate uncertainty. These principles can strengthen women’s investment tactics without requiring investors to copy a famous money manager.

Learning from Disruptive Innovation Focus

Cathie Wood’s investment approach highlights the potential and risks of investing in emerging technologies. Her focus on disruptive innovation demonstrates how investors can build a portfolio around long-term economic themes rather than only established industries.
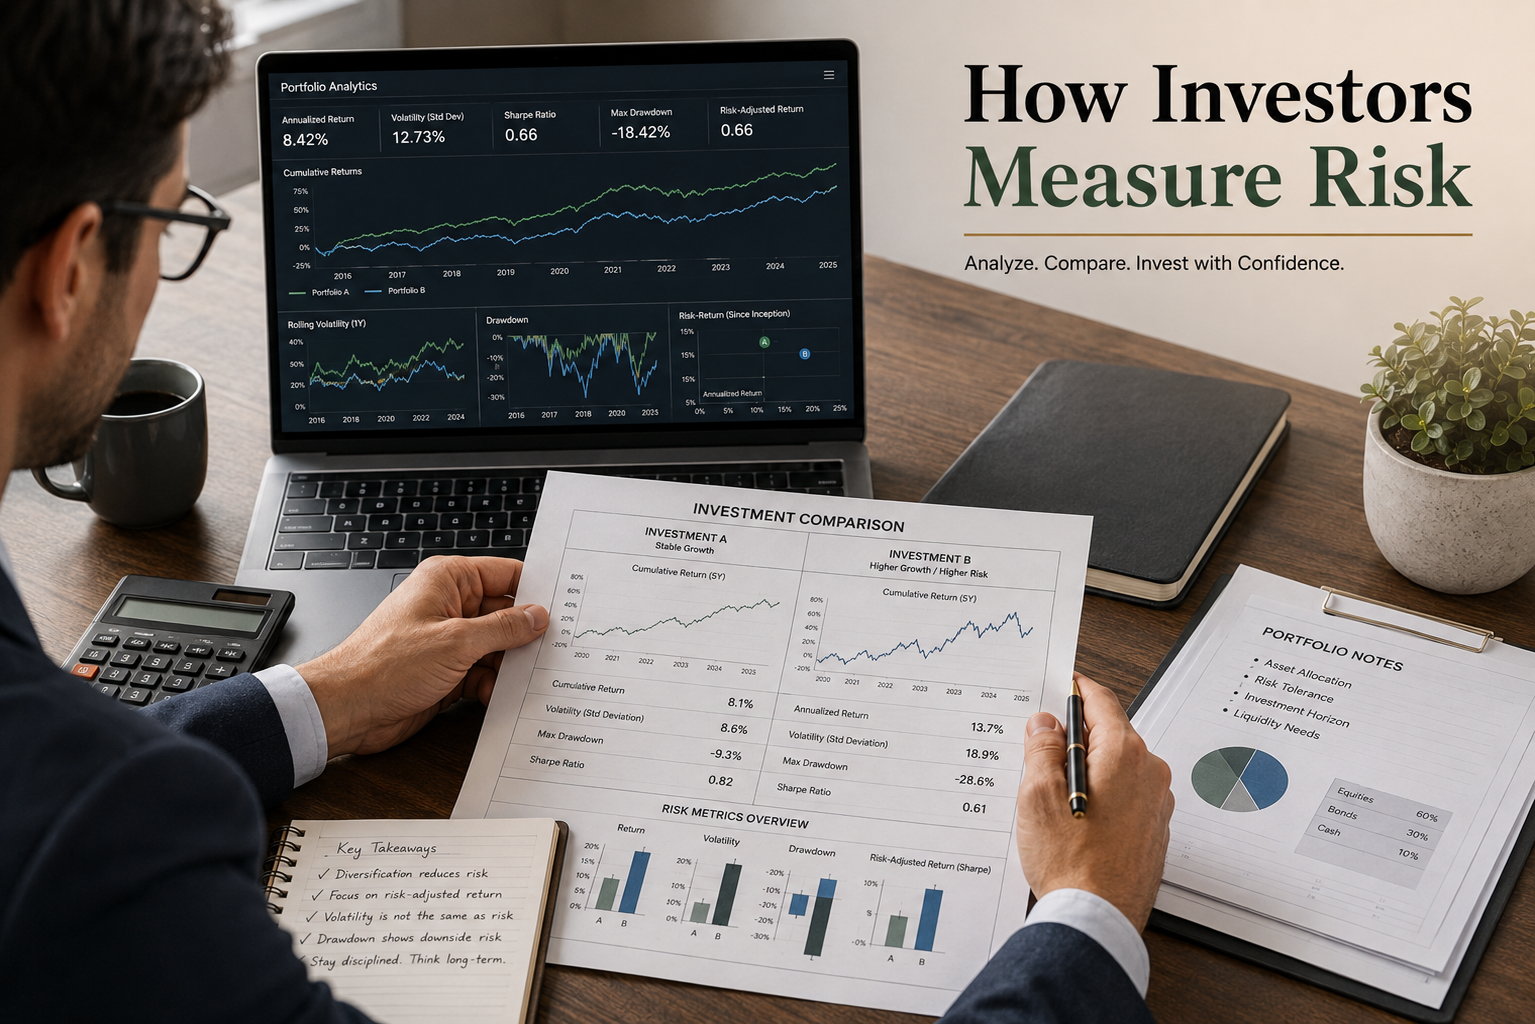
However, thematic investing requires careful research. Emerging technologies can face intense competition, regulatory changes, high valuations, and uncertain commercial outcomes. A compelling technological trend does not guarantee that every company involved will become profitable.
Investors who want exposure to disruptive sectors should consider how much risk they can realistically tolerate. A smaller allocation may be more appropriate than concentrating an entire portfolio in speculative themes.

Research should cover the underlying companies, valuations, competitive advantages, financial health, and broader market conditions. Investors should also understand the difference between investing in a promising industry and selecting a financially strong company.

For women’s investment tactics, the key lesson is not to imitate a celebrity investor. Instead, develop independent research habits, maintain diversification, and size higher-risk positions appropriately. Strong conviction should always exist alongside disciplined risk management.

What is the 70-10-10-10 rule for money?

The 70-10-10-10 rule for money is a budgeting framework that divides net income into four categories. A common version allocates 70 percent to living expenses, 10 percent to savings, 10 percent to investing, and 10 percent to giving.

This structure can provide a simple starting point for managing monthly cash flow. However, it is not a universal financial formula. Housing costs, debt, income levels, family responsibilities, taxes, and financial goals vary widely.

For someone moving from saving to investing, dedicating a defined portion of income to investments can encourage consistency. The percentage should still be adjusted when necessary. Someone with expensive high-interest debt, for example, may need to prioritize debt repayment before increasing investment contributions. Learning how to pay off debt faster can help create more room for consistent investing over time.

The framework works best as a guideline rather than a strict rule. Review your budget regularly and adjust the percentages as circumstances change.

When used thoughtfully, this approach can support women’s investment tactics by creating a repeatable system for balancing everyday spending, saving, investing, and personal priorities.

Automating Your Monthly Income Splits

Automation can make a budgeting and investing system easier to maintain. Instead of waiting until the end of the month to see what remains, schedule transfers soon after receiving income.

You can direct predetermined amounts toward an emergency fund, investment account, debt repayment, or other financial goals. This approach reduces the chance of spending money that was intended for long-term priorities.

Automation also supports consistency. Regular contributions can help investors avoid making every investment decision based on market headlines or short-term emotions. However, automatic investing does not remove investment risk. The assets selected still need to match your goals and risk tolerance.

Review your automated transfers whenever your income or expenses change. A system that worked last year may no longer suit your current financial position.

For investors developing women’s investment tactics, automation should support a broader financial plan. It should not replace budgeting, emergency savings, debt management, or portfolio reviews. The objective is to create a system that makes good financial habits easier to maintain over time.

Who is the famous female financial advisor?

Suze Orman is one of the most widely recognized female personal-finance educators and financial personalities. Through books, television programs, podcasts, and other media, she has helped bring personal-finance topics to a broad audience.

Her advice has often focused on building financial security before pursuing more aggressive wealth-building strategies. Common themes include managing debt, maintaining emergency savings, understanding spending habits, and developing confidence around financial decisions.

Her public influence makes her a useful example of how financial education can change people’s approach to money. However, investors should distinguish between general financial education and personalized financial advice. A strategy that works for one person may not suit another person’s income, goals, taxes, or risk tolerance.

For anyone exploring women’s investment tactics, the broader lesson is the importance of financial literacy. Understanding how investments work can help you evaluate recommendations and avoid decisions based solely on fear or hype.

Financial independence begins with control over your financial choices. Education, planning, and consistent action can help turn that control into long-term progress.

Embracing Financial Independence and Control

Financial independence requires more than choosing investments. It starts with understanding your income, expenses, debts, savings, and long-term goals. Without this foundation, even a sophisticated portfolio can become difficult to manage. Creating a personal financial plan for wealth can provide a structured way to bring these elements together.

Learning how different investments work can improve decision-making. Investors should understand potential returns, fees, liquidity, taxes, volatility, and the risks associated with each asset. This knowledge can make financial conversations less intimidating and more productive.

It is also important to review your financial plan as circumstances change. Career changes, new financial responsibilities, major purchases, and shifting goals can all affect the right investment strategy.

For women, developing women’s investment tactics should ultimately be about building greater financial control. That does not mean taking excessive risks or trying to predict every market move. It means creating a plan, investing consistently, managing risk, and making decisions based on clear objectives.

The strongest strategy is one you can understand and maintain. With disciplined saving, informed investing, diversification, and regular reviews, moving from saver to strategic investor becomes a practical long-term process.

FAQ SECTION

How much of my income should I invest as a beginner?

Beginners should aim to invest at least 10 to 15 percent of their net income consistently. If that feels overwhelming at first, start with a smaller percentage like 5 percent and increase it by 1 percent every few months. Automating these transfers ensures steady portfolio growth without requiring constant active management or triggering decision fatigue.

What are the best low-risk investments for women starting out?

Index funds, exchange-traded funds (ETFs), and government bonds are excellent low-risk starting points. They offer instant diversification across hundreds of companies, reducing the impact of individual stock volatility. These instruments provide stable, historical compounding returns, making them ideal core holdings for long-term wealth accumulation strategies.

How do I overcome the fear of losing money in the stock market?

Overcoming investment fear starts with education, a long-term mindset, and investing only money you do not need immediately. Diversifying your portfolio across stable asset classes cushions against market dips. Remember that historical market data shows equities recover and trend upward over extended multi-year holding periods.

Can I start investing with a small amount of money?

Yes, modern brokerage platforms allow you to start investing with as little as five or ten dollars. Fractional shares make it possible to own portions of high-value stocks or index funds. Consistency matters far more than your initial starting capital when building long-term investment habits.

Conclusion

Transitioning from a cautious saver to a confident, strategic investor is one of the most empowering choices you can make. By implementing proven women’s investment tactics, leveraging rules like the 7-7-7 and 70-10-10-10 frameworks, and following guidance from industry icons, you build an unstoppable foundation for wealth. Financial independence is not about luck; it is about structured planning, patience, and consistent action. Take what you have learned today, automate your contributions, and start putting your money to work for your future.

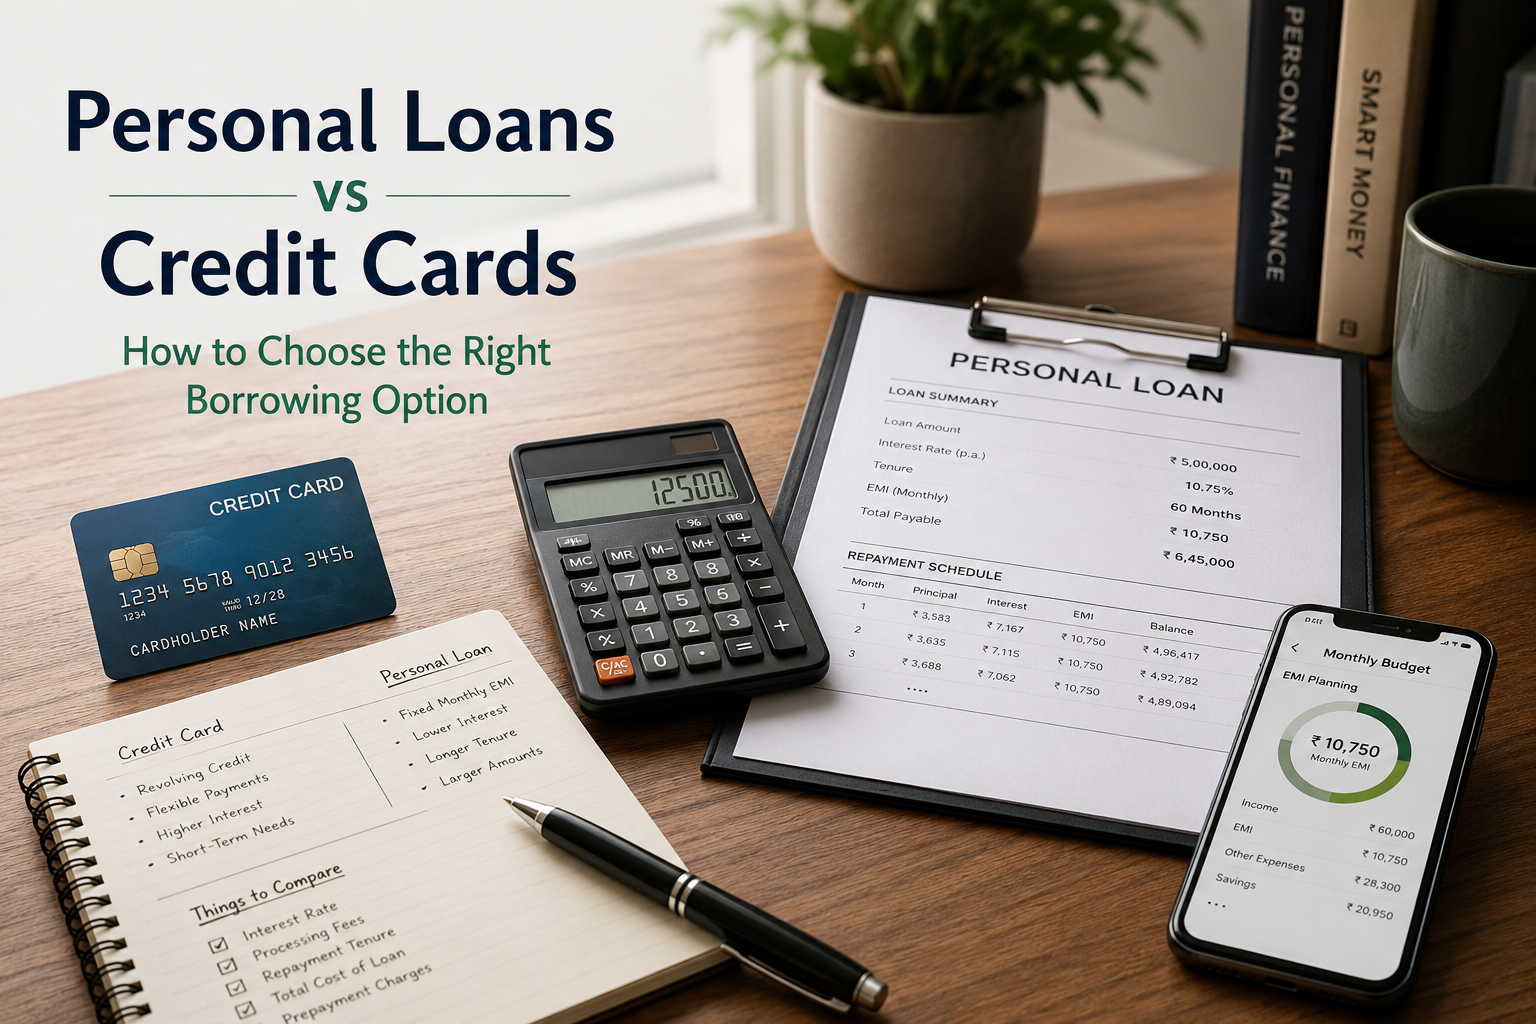
Personal Loans vs Credit Cards: Which Option Is Better?

Personal Loans vs Credit Cards: How to Choose the Right Borrowing Option

Choosing between personal loans vs credit cards often comes down to your immediate cash requirements and your repayment discipline. According to consumer guidelines from the Consumer Financial Protection Bureau, understanding the true cost of credit helps borrowers avoid long-term debt traps. Both products provide access to borrowed funds, but they function differently in practice.

A personal loan offers a lump sum of money with a fixed repayment period and predictable monthly installments. In contrast, a credit card provides a revolving line of credit that you can draw from repeatedly. Using the wrong financing tool can lead to excessive interest charges or damaged credit scores.

This guide breaks down everything you need to know about these two common borrowing options. We answer essential questions about whether credit card loans beat installment loans, which option builds your credit profile faster, the hidden disadvantages of personal borrowing, and which product is simpler to obtain. You will also discover whether credit card EMIs or standard personal loans offer better value for your wallet.

Is a credit card loan better than a personal loan?

A credit card loan is not automatically better than a personal loan. The better option depends on the amount borrowed, repayment period, and total borrowing cost. Credit card borrowing can be convenient when you need funds quickly for a smaller expense. Some cards also offer pre-approved borrowing or instant access to funds.

However, convenience can come with higher interest costs. A personal loan may be more suitable when you need a larger amount or several months or years to repay it. Personal loans commonly offer fixed interest rates and predictable monthly payments, depending on the lender and product.

Consider a credit card when you can repay the balance quickly and avoid expensive revolving interest. Consider a personal loan when you need structured repayment for a larger planned expense. It is also useful to understand the difference between good debt and bad debt before taking on new borrowing.

Before choosing, compare the annual interest rate, processing fees, repayment period, and total amount payable. The lowest monthly payment is not always the cheapest option.

Total Cost and Interest Rate Comparison

Interest rates can make a major difference when comparing personal loans and credit card borrowing. Personal loans often have lower interest rates than standard credit card balances, especially for borrowers with strong credit profiles. They also usually provide a fixed repayment schedule, which makes the total cost easier to estimate.

Credit card borrowing can become expensive when you carry a balance from month to month. Interest may continue accumulating until the balance is repaid. Cash advances can also have separate fees and interest rules, depending on the card issuer.

A useful comparison should include more than the advertised interest rate. Check:

  • Interest rate and effective borrowing cost
  • Processing or origination fees
  • Late-payment charges
  • Prepayment or foreclosure charges
  • Repayment tenure
  • Total interest payable

If you need several years to repay a large balance, a personal loan may cost less overall. If you can repay quickly, a credit card may be more convenient. Always compare the complete cost before borrowing, especially if you are already working to pay off debt faster and reduce your outstanding balances.

Are credit cards or personal loans better for credit?

Neither credit cards nor personal loans is automatically better for your credit profile. Their impact depends mainly on how you manage the account. On-time payments are important for both types of borrowing and can support a healthy credit history. For more ways to strengthen your credit profile, see this guide to improving your credit score fast.

Credit cards can also affect your credit utilization ratio. This measures how much of your available revolving credit you are using. High utilization can negatively affect credit scores, while lower utilization is generally viewed more favorably.

Personal loans work differently because they are installment accounts. Regular payments can demonstrate responsible management of fixed-term debt. They may also contribute to your overall credit mix, although credit mix is only one part of a credit score.

Opening either account can temporarily affect your credit because lenders may perform a hard inquiry. Taking on debt you cannot comfortably repay can cause more serious problems.

For that reason, the best choice is the product you can manage responsibly. Payment history, debt levels, and responsible borrowing matter more than simply choosing one product over the other.

The Role of Credit Utilization

Credit utilization is particularly important when using credit cards. It compares your outstanding revolving balances with your available credit limits. For example, a $2,000 balance on a $10,000 limit represents 20% utilization. Understanding credit card tips and responsible usage can also help you manage revolving debt more effectively.

Lower utilization is generally better for credit health, although there is no universal percentage that guarantees a higher score. The often-mentioned 30% guideline is useful as a general reference, not a strict rule.

Personal loans do not normally count toward revolving credit utilization in the same way. Instead, they are installment accounts with a fixed balance that typically decreases as you make payments.

Credit cards can therefore have a more visible short-term effect on credit scores through utilization. However, this does not mean credit cards are inherently better for building credit.

To use a card responsibly:

  • Keep balances manageable.
  • Pay bills on time.
  • Avoid repeatedly reaching the credit limit.
  • Monitor your overall debt.
  • Pay more than the minimum when possible.

A personal loan can also support your credit history when you make every scheduled payment on time.

What are the disadvantages of a personal loan?

Personal loans offer predictable repayment, but they are not without drawbacks. One major disadvantage is the fixed repayment obligation. Once the loan is disbursed, you generally need to make the agreed monthly payment regardless of changes in your budget.

Personal loans can also include processing, origination, documentation, or other lender-specific charges. These costs reduce the amount you actually receive or increase the overall borrowing cost. Some loans may also have restrictions or charges related to early repayment, depending on the lender and local rules.

Another risk is borrowing more than you need. Because personal loans provide a lump sum, borrowers may spend surplus funds simply because the money is available.

The repayment structure can also become difficult if your income falls unexpectedly. Unlike revolving credit, you usually cannot reduce the scheduled installment without changing the loan arrangement. Maintaining an emergency fund can provide a financial buffer when unexpected expenses or income changes affect your ability to meet repayments.

Before applying, calculate whether the payment fits comfortably within your budget. Compare the total repayment amount, not just the monthly installment. A lower payment can still mean a higher total cost when the loan runs for longer. Creating a personal financial plan can help you assess whether new borrowing fits your wider financial goals.

Upfront Fees and Prepayment Penalties

Fees can change the true cost of a personal loan. Lenders may charge processing or origination fees before or when the loan is disbursed. The amount varies by lender, borrower, loan type, and market, so borrowers should never assume a standard percentage.

Some lenders may also charge fees for certain repayment actions. Depending on the loan agreement and applicable regulations, early repayment or foreclosure can sometimes involve additional costs.

These charges matter because a lower interest rate does not automatically make one loan cheaper. For example, a loan with a lower rate but substantial upfront fees may cost more than another loan with a slightly higher rate.

Before accepting an offer, review the complete fee schedule. Look for:

  • Processing or origination fees
  • Documentation charges
  • Late-payment fees
  • Early-repayment or foreclosure charges
  • Insurance or optional add-on costs

Ask the lender for the total amount payable over the full term. This provides a clearer comparison than looking at the advertised interest rate alone.

What is easier to get, a personal loan or a credit card?

A credit card can be easier to obtain than an unsecured personal loan in some situations, but approval is not guaranteed. Lenders assess your credit history, income, existing debt, and other eligibility factors for both products.

Some credit cards are designed for people with limited credit histories. Secured credit cards can also provide an alternative because they are backed by a refundable security deposit. However, applicants still need to meet the issuer’s requirements.

Personal loans usually involve a more detailed assessment because the lender is providing a lump sum that must be repaid over a fixed period. Approval may depend on income stability, credit history, existing obligations, and debt-to-income considerations.

A weaker credit profile can make either product more expensive or harder to obtain. Applying for several products at once may also result in multiple hard inquiries.

Instead of choosing based only on approval speed, compare the terms you qualify for. An easily approved credit card can become expensive if you carry a balance. A personal loan may offer better repayment terms when the lender’s offer is affordable.

Secured Cards for Fast Approvals

Secured credit cards can be useful for borrowers who have difficulty qualifying for traditional unsecured cards. They generally require a cash security deposit, which helps reduce the issuer’s lending risk. The credit limit may be linked to the deposited amount, depending on the issuer.

However, describing secured cards as having virtually guaranteed approval would be inaccurate. Approval still depends on the card provider’s eligibility rules and application assessment.

The main advantage is accessibility. A secured card can help establish or rebuild a credit history when used responsibly. Regular payments may be reported to credit bureaus, although reporting practices vary by issuer.

Before choosing a secured card, check whether it reports payments to the relevant credit bureaus. Also review annual fees, interest rates, deposit requirements, and other charges.

A secured card is not the same as borrowing a personal loan. The deposit provides security for the card issuer, while your spending remains subject to the card’s credit limit.

If your goal is to build credit, focus on consistent payments and controlled balances rather than simply obtaining an account quickly.

Personal Loan or Credit Card EMI: Which Is Better

Choosing between a personal loan and a credit card EMI depends on the expense, repayment period, and financing offer. When comparing personal loans vs credit cards, consider whether you need a lump-sum amount or want to convert a specific purchase into manageable monthly installments.

Credit card EMIs can be convenient for eligible purchases because they allow you to convert a transaction into fixed monthly installments. Some retailers and card issuers may also offer promotional or no-cost EMI plans on selected products. However, check processing fees, taxes, discounts, and the actual amount payable before accepting an offer.

A personal loan may be more suitable for larger expenses that are not linked to a particular merchant. Home repairs, education expenses, medical costs, or other planned expenditures may be financed through a personal loan, depending on lender eligibility and terms.

The repayment period also matters when evaluating personal loans vs credit card EMI. Personal loans may provide longer repayment tenures, whereas credit card EMI periods vary by issuer and transaction. A longer tenure can lower your monthly payment but may increase the total interest paid.

Do not choose an option simply because it has a smaller EMI. Compare the total repayment amount, interest rate, processing fees, tenure, and monthly payment. For personal loans vs credit cards, the better choice is ultimately the one that meets your funding requirement at a manageable overall cost without encouraging unnecessary borrowing.

Choosing Between Merchant Deals and Tenures

Credit card EMIs can make sense when a merchant or card issuer provides a genuine low-cost financing promotion. They may be particularly convenient for planned purchases such as electronics, appliances, or other eligible retail products.

However, the phrase “no-cost EMI” does not always mean the transaction has no additional costs. Check whether processing fees, taxes, or changes to an upfront discount affect the final amount you pay.

A personal loan may be more appropriate when you need a larger amount or a longer repayment period. It can provide a structured payment schedule without tying the borrowing to a particular purchase or merchant.

Compare these factors before choosing:

  • Total amount repayable
  • Interest rate or effective financing cost
  • Processing and other fees
  • Repayment tenure
  • Monthly installment
  • Prepayment terms

For a small purchase that you can repay within a short period, a credit card EMI may be convenient. For substantial expenses requiring longer repayment, a personal loan may provide better structure.

The key is to compare total cost rather than promotional wording. The cheapest-looking option is not always the cheapest one.

Frequently Asked Questions

Can I pay off a personal loan using a credit card?

Most lenders do not allow borrowers to make direct personal loan payments with a standard credit card. Some balance transfer cards or third-party services may provide alternatives, but fees can apply. Before choosing this route, compare the transfer costs, interest rate, and repayment period to determine whether it actually reduces your overall debt burden.

Does applying for both options hurt my credit score?

Applying for both a personal loan and a credit card can temporarily affect your credit score because lenders may perform hard credit inquiries. However, one or two inquiries generally have a limited impact. When comparing personal loans vs credit cards, use pre-qualification tools that rely on soft inquiries where available, and avoid submitting several applications in a short period.

What happens if I only pay the minimum on my credit card?

Paying only the minimum keeps your credit card account in good standing, but interest continues accumulating on the unpaid balance. Because credit card rates can be high, repayment may take much longer and cost substantially more. When comparing personal loans vs credit cards, remember that personal loans typically provide fixed payments and a defined payoff date.

Can I get a personal loan with a low credit score?

You may qualify for a personal loan with a low credit score, although your available terms may be less favorable. Some lenders charge higher interest rates or fees to offset increased lending risk. Comparing multiple offers, considering a secured loan, or applying with a qualified co-signer may improve your chances of obtaining more manageable terms.

Conclusion

Understanding personal loans vs credit cards can help you choose financing based on cost, flexibility, and repayment structure. Credit cards suit recurring purchases and short-term borrowing when balances are managed carefully, while personal loans can work better for larger, planned expenses and debt consolidation. Compare interest rates, fees, monthly payments, and your budget before choosing either option. For broader guidance, managing your finances wisely can help you make borrowing decisions that support your long-term financial goals.

How to Create a Personal Financial Plan for Wealth

How to Create a Personal Financial Plan

Learning how to create a personal financial plan can help you take control of your money and reduce financial stress. A clear plan makes it easier to manage expenses, prepare for emergencies, reduce debt, and work toward long-term goals. The Consumer Financial Protection Bureau also provides resources that support better financial decision-making and financial well-being.

There is no single budgeting method that works for everyone. Rules such as the 7-7-7 rule, 70-10-10-10 rule, and 50/30/20 rule are useful frameworks. However, you should adapt them to your income, expenses, debt, and goals. This guide explains how to create a personal financial plan and provides a practical example. You will also learn the five basic steps of financial planning and ways to make your plan easier to maintain.

What is the 7 7 7 rule for money?

The 7-7-7 rule for money is sometimes presented as a financial planning framework built around three groups of seven. However, unlike the 50/30/20 rule, it is not a universally standardized personal finance method. Different sources may define the three parts differently. One version focuses on maintaining several months of emergency savings, investing for a longer period, and managing debt through structured targets. Because interpretations vary, you should treat this rule as a planning concept rather than a strict financial formula. Before following it, consider your income, monthly expenses, interest rates, and financial goals. The most useful part of the approach is its emphasis on financial security, long-term investing, and debt reduction. These priorities can help you create a balanced strategy. Still, you do not need to force every financial decision into a seven-year or seven-month target if another timeframe better suits your circumstances.

Emergency Funds and Milestone Planning

An emergency fund should protect you from unexpected expenses without forcing you to rely on credit cards or loans. Start by calculating your essential monthly costs, including housing, food, utilities, transportation, and minimum debt payments. You can then choose an emergency savings target based on your circumstances.

Many people begin with a smaller cash buffer before working toward several months of essential expenses. A larger reserve may be useful when income is unstable or major financial responsibilities exist. Keep emergency savings accessible instead of placing the money in investments that could lose value.

You can also divide the goal into manageable milestones. For example, you might first save $1,000, then one month of essential expenses, and eventually several months. Automatic transfers can make progress easier by moving money into savings before you have an opportunity to spend it. Review the target whenever your income, household situation, or monthly expenses change. For more guidance, see emergency fund vs. savings priorities

What is the 70-10-10-10 rule for money?

The 70-10-10-10 rule for money is a budgeting framework that divides income into four categories. A common version assigns 70% to living expenses, 10% to savings or investments, 10% to debt repayment, and 10% to giving. However, this is a guideline rather than a universal financial standard. Your percentages may need to change based on housing costs, income level, debt, family responsibilities, and financial goals. For example, someone with high-interest debt may benefit from directing more than 10% toward repayment. Another person may need a larger savings contribution to build an emergency fund. The value of this framework comes from giving each part of your income a clear purpose. It encourages you to cover current expenses while also planning for the future. When learning how to create a personal financial plan, use the 70-10-10-10 rule as a starting point. Adjust the percentages when your circumstances require a different allocation.

Living Within Your Means

Living within your means requires keeping spending below your available income. The 70% spending target can provide a useful benchmark, but it should not become a rigid requirement. Using a structured approach such as the envelope budgeting method can also help you control spending across different categories.

Housing, transportation, childcare, and other essential costs vary between households. Start by reviewing your actual spending instead of assuming every expense fits neatly into one category.

Separate fixed expenses from variable expenses. Then identify costs you can reduce without affecting essential needs.

If housing consumes most of your income, cutting small purchases may not solve the problem. You may need larger changes, such as reducing transportation costs or reviewing housing expenses.

Avoid creating an unrealistic budget that removes every enjoyable purchase. A sustainable financial plan should leave room for reasonable lifestyle spending.

Regular expense reviews can help you identify waste and redirect money toward important goals. They also keep your budget aligned with changing income and priorities.

What is the 50/30/20 rule for personal finance?

The 50/30/20 rule for personal finance divides after-tax income into three broad spending categories. The traditional framework assigns 50% to needs, 30% to wants, and 20% to savings and debt repayment.

Needs can include housing, utilities, groceries, transportation, insurance, and required debt payments. Wants may include dining out, entertainment, hobbies, subscriptions, and vacations.

The final 20% can support emergency savings, retirement contributions, investments, or additional debt payments. This framework provides a simple starting point for organizing your money.

However, these percentages are not mandatory. Someone living in an expensive city may spend more than 50% on essential costs.

Someone with aggressive financial goals may choose to save more than 20%. Your budget should reflect your actual financial circumstances.

When considering how to create a personal financial plan, use the rule to understand your spending patterns. Then adjust the percentages according to your income, expenses, and priorities.

Balancing Needs and Wants

Separating needs from wants is essential when building a realistic budget. Needs are expenses required for basic living or important financial obligations.

These can include rent, groceries, utilities, insurance, transportation, and minimum loan payments. Wants provide convenience, entertainment, or enjoyment but are usually easier to reduce.

The distinction is not always absolute. For example, transportation may be a need, while an expensive vehicle upgrade may be a want.

Review each expense based on its purpose and cost. If spending exceeds your available income, start with flexible wants before cutting essential expenses.

You can also create limits for discretionary categories instead of removing them completely. This approach makes your budget easier to maintain over time.

A sustainable budget should reflect real life, rather than an unrealistic spending pattern. As your income or responsibilities change, revisit your needs, wants, and savings priorities.

That flexibility can help prevent your financial plan from becoming too restrictive.

What are the 5 basic steps in personal financial planning?

The five basic steps in personal financial planning provide a simple structure for managing your money. First, assess your current financial position by reviewing your income, expenses, savings, debts, assets, and net worth.

Second, establish specific financial goals. These might include building an emergency fund, paying off debt, buying a home, or preparing for retirement.

Third, create a budget that connects your income with those goals. You can use frameworks such as the 50/30/20 rule as a starting point.

Fourth, put the plan into action through consistent saving, appropriate investing, debt repayment, and expense management. If debt is a major priority, learning how to pay off debt faster can help you choose a repayment strategy. Choose strategies that match your financial situation and goals.

Fifth, monitor your results and make adjustments when your circumstances change. These steps work together rather than operating as isolated tasks.

A new expense can affect your budget, while a salary increase can change your savings capacity. Learning how to create a personal financial plan therefore requires both initial planning and regular review.

The goal is to create a system that can adapt as your financial life changes.

Tracking and Adapting Over Time

A financial plan should not remain unchanged after you create it. Regular reviews help you identify problems before they become larger financial setbacks.

Review your budget several times each year. Consider a deeper review whenever your income or expenses change significantly.

Check whether you are meeting savings targets, reducing debt, and progressing toward longer-term goals. You should also review recurring expenses, subscriptions, insurance costs, and investment contributions. Using personal finance apps can make it easier to track these areas consistently.

Major life events may require more significant changes. A new job, marriage, relocation, large purchase, or change in household income can affect your priorities.

Market conditions can also influence investment decisions. Understanding risk vs. return in investing can help you evaluate how much uncertainty you are comfortable accepting. However, short-term market movements should not automatically change a long-term investment strategy.

Keep a simple record of your goals and progress. This makes it easier to compare results and identify areas that need attention.

Financial planning is an ongoing process, not a one-time exercise. Adjust your plan when circumstances change while keeping your broader financial objectives in focus.

How to create a personal financial plan example?

A practical example can make how to create a personal financial plan easier to understand. Imagine Sarah earns $4,000 in monthly take-home pay.

She wants to build an emergency fund, save for retirement, and manage everyday expenses. Using the 50/30/20 framework as a starting point, she could allocate up to $2,000 toward essential needs.

These needs might include housing, groceries, utilities, and transportation. She could reserve up to $1,200 for wants, including dining, entertainment, and hobbies.

The remaining $800 could support savings and additional debt payments. If Sarah has high-interest debt, she may direct more money toward repayment before increasing investments.

If her essential expenses already exceed $2,000, she should adjust the percentages. She should not force her budget to fit the rule.

Sarah can track her spending each week and review her progress monthly. This personal financial plan example shows how a simple framework can become a practical system.

The plan should reflect her actual income, expenses, financial obligations, and long-term priorities.

Setting Up Automated Transfers

Automation can make your financial plan easier to follow. It reduces the need to make the same saving decision every month.

After receiving your paycheck, schedule automatic transfers toward your emergency fund, retirement account, investment account, or other savings goals. Start with an amount your budget can consistently support.

If you are building an emergency fund, keep those savings accessible. Separating them from everyday spending money can also reduce the temptation to spend them.

Once you establish a sufficient cash reserve, you can redirect additional savings toward longer-term goals. Exploring investment ideas and tips for financial success can help you consider different approaches. Consider your risk tolerance and investment time horizon when making those decisions.

Automation should support your plan rather than replace it. Review your transfers whenever your income, expenses, or financial priorities change.

You should also maintain enough money in your main account for essential bills and unexpected costs. Paying yourself first can make saving more consistent, while learning about the best places to keep your savings safely can help you decide where to hold your cash. The amount must still fit your overall budget.

When combined with regular reviews, automated transfers can turn financial goals into repeatable monthly habits.

Frequently Asked Questions

What is the best way to start tracking daily expenses?

The best way to start tracking daily expenses is by using a dedicated mobile budgeting app or a simple digital spreadsheet. Reviewing every transaction weekly helps you identify wasteful spending patterns and ensures you stay aligned with your overall financial plan.

How often should I review my personal financial plan?

You should review your personal financial plan at least once every quarter, or immediately after experiencing major life changes. Significant events like getting married, changing jobs, or buying a home require immediate adjustments to your budget and savings goals.

Is it necessary to eliminate all debt before investing?

It is not necessary to eliminate all low-interest debt before investing, but high-interest consumer debt should be cleared first. Balancing debt repayment with retirement contributions allows your money to compound in the market while you steadily reduce liabilities.

What constitutes an emergency expense?

An emergency expense is an unexpected, urgent, and necessary financial need that threatens your immediate well-being or stability. Examples include sudden medical bills, critical car repairs, or emergency home maintenance, rather than planned vacations or holiday shopping.

Conclusion

Learning how to create a personal financial plan empowers you to take command of your money rather than letting money control you. By applying structured frameworks like the 50/30/20 rule, the 70-10-10-10 guideline, and essential planning steps, you build unshakeable security. Financial freedom does not happen overnight, but consistent small actions compound into massive long-term results over time. Take the first step today by assessing your income, setting clear goals, and automating your savings routines. Your future self will thank you for the financial discipline and peace of mind you cultivate right now.

Public Service Loan Forgiveness: Complete Guide

Understanding the Complete Guide to Public Service Loan Forgiveness

Navigating student debt can feel overwhelming when you are building a career in public service. Fortunately, Public Service Loan Forgiveness (PSLF) can help eligible borrowers eliminate the remaining balance on qualifying federal student loans.

The program is available to borrowers who meet specific requirements involving their employer, loan type, repayment plan, and qualifying payments. The rules are detailed, so checking your status regularly is essential. You can review current guidance and use official tools through Federal Student Aid.

PSLF generally requires 120 qualifying monthly payments while working full-time for an eligible employer. Those payments do not need to be consecutive. Your eligible employment and loan status must also meet program requirements during the qualifying period.

This guide explains how Public Service Loan Forgiveness works, who qualifies, how to document employment, what happens after 10 years, and how recent policy changes may affect borrowers.

How to do Public Service Loan Forgiveness?

Successfully pursuing Public Service Loan Forgiveness requires careful attention to your loans, employment, repayment plan, and payment history. Start by checking whether your federal loans are eligible Direct Loans. Federal Family Education Loan and Perkins Loans generally do not qualify unless they are consolidated into a Direct Consolidation Loan.

Next, confirm that your employer qualifies. PSLF eligibility depends primarily on your employer rather than your specific job title. Government organizations and qualifying nonprofit employers can meet the requirement. Understanding how debt affects your broader finances is also important, so consider reviewing good debt vs. bad debt.

You should then review your repayment options and confirm that your payments can qualify. Federal Student Aid recommends using its repayment calculator when comparing plans for PSLF. Current repayment rules have changed, including new repayment options introduced in 2026. Managing these payments alongside other financial obligations can be easier with a clear budgeting strategy.

Finally, submit a PSLF form regularly to document your qualifying employment and track your payment count. Keeping copies of forms, employment records, and payment information can help resolve future discrepancies.

Submitting Employment Certification Forms

Submitting employment certification regularly is one of the most useful ways to monitor your Public Service Loan Forgiveness progress. Federal Student Aid encourages borrowers to submit a PSLF form each year. You should also consider submitting one when you change qualifying employers.

The form allows the Department of Education to verify your employer and update your qualifying payment information. Your employer must provide the required certification and signature. The PSLF Help Tool can help identify eligible employers and generate the appropriate form.

Annual certification is not the only time you can submit the form. Current guidance states that borrowers are required to submit it when they reach the required 120 qualifying months. However, submitting it more frequently can help identify problems earlier.

Keep copies of submitted forms and confirmation records. Also monitor your payment count through your StudentAid.gov account. If your count changes unexpectedly, review your employment and payment history promptly.

What qualifies under Public Service Loan Forgiveness?

Eligibility for Public Service Loan Forgiveness depends on several requirements working together. Your employer, loans, repayment plan, employment status, and payments all matter. Meeting only one or two requirements is not enough to receive forgiveness.

Your employer generally must be a qualifying government organization or eligible nonprofit organization. Federal, state, local, and tribal government employers can qualify. Certain tax-exempt nonprofit organizations also qualify, along with some other nonprofit organizations providing qualifying public services.

Your loans must generally be eligible Direct Loans. Federal Family Education Loan and Perkins Loans do not qualify for PSLF unless appropriate consolidation requirements are met.

You must also work full-time for a qualifying employer while making qualifying payments. PSLF requires 120 qualifying monthly payments before forgiveness can be granted. Those payments do not have to be consecutive.

Because repayment rules are changing, borrowers should verify their current repayment options through Federal Student Aid rather than relying on older PSLF guides. Borrowers can also benefit from managing education expenses wisely when planning their overall student finances.

Evaluating Eligible Employer Types

Your employer’s status is more important than your job title when determining Public Service Loan Forgiveness eligibility. A qualifying position does not automatically make an employer eligible, and a specific profession is not required for PSLF.

Government organizations at the federal, state, local, and tribal levels can qualify. Certain tax-exempt organizations under Section 501(c)(3) can also qualify. Some other nonprofit organizations may qualify when they provide specified public services.

Before assuming that your employer qualifies, use the official PSLF Employer Search. Federal Student Aid allows borrowers to search for an employer using identifying information such as the employer’s EIN.

This step is especially important before relying on future forgiveness as part of your financial plan. Employer eligibility can also change, so previously qualifying employment should not be treated as permanent proof of future eligibility.

Keep documentation showing where you worked and when you worked there. Regular PSLF certification can provide additional confirmation and help identify eligibility problems before you reach the end of your repayment period.

What happens after 10 years of PSLF?

Reaching 10 years of qualifying service does not automatically erase your loans. Instead, you generally need 120 qualifying monthly payments before requesting Public Service Loan Forgiveness. The payments must meet program requirements, and qualifying employment must also be established.

Once you reach the required number of qualifying payments, you can request forgiveness through the appropriate PSLF application process. The Department of Education reviews your qualifying employment and payment history before approving the discharge.

The amount forgiven generally includes the remaining principal and accrued interest on eligible loans after the final required payment.

Do not assume that every payment made during a 10-year period automatically qualifies. Periods involving certain repayment plans, deferments, forbearances, or employment changes may affect your payment count. If you are managing multiple balances, learning how to pay off debt faster can also help you stay financially organized.

The safest approach is to track your qualifying payment count throughout the process. Review your StudentAid.gov account regularly and resolve discrepancies before submitting your final forgiveness request.

Receiving Official Loan Discharge

The final stage of Public Service Loan Forgiveness involves submitting your forgiveness request and allowing the Department of Education to verify your eligibility. Reaching 120 payments does not mean that your balance disappears immediately.

The department must confirm that your payments and employment satisfy the applicable requirements. Current federal regulations provide that forgiveness covers the qualifying principal and accrued interest remaining when the borrower satisfies the final required monthly payment obligation.

Until your forgiveness is officially processed, follow instructions from your loan servicer regarding payments. Do not simply stop paying because your payment count appears to have reached 120.

Keep copies of your PSLF forms, employment certifications, payment records, and official correspondence. These documents can be useful if your account requires additional review. Maintaining an emergency fund can also provide a financial cushion while you wait for your loan status to be finalized.

After approval, monitor your loan account to confirm that the eligible balance has been discharged. You should also check your account for any remaining loans that were not included in the forgiveness request.

The important distinction is simple: 120 qualifying payments make you eligible to request forgiveness; they do not replace the final approval process.

Are PSLF loans still being forgiven?

Yes. Public Service Loan Forgiveness remains an active federal program in 2026. The program continues to provide forgiveness for eligible borrowers who satisfy the applicable requirements. Federal Student Aid continues to provide PSLF forms, employer verification tools, payment tracking, and forgiveness resources.

However, borrowers should not assume that older PSLF guidance remains completely unchanged. Federal student loan repayment rules have undergone significant changes during 2026. New repayment options took effect July 1, 2026, while some older repayment plans are being phased out.

The Department of Education has also implemented changes affecting PSLF regulations and employer eligibility. Some regulatory provisions have faced court action, so borrowers should rely on current federal guidance rather than outdated articles or social media claims.

For borrowers pursuing forgiveness, the practical priorities remain the same: verify your employer, understand your loan status, track qualifying payments, and submit PSLF documentation regularly.

Tracking Ongoing Program Updates

Following official updates is especially important because Public Service Loan Forgiveness rules can change through legislation, regulations, court decisions, and administrative actions. Borrowers should avoid making long-term financial decisions based solely on headlines or social media posts.

Start with StudentAid.gov and the Department of Education for authoritative information. The PSLF Help Tool can help borrowers check employer eligibility, submit forms, and monitor their progress.

Current repayment rules also deserve attention. Federal student loan reforms introduced new repayment options in 2026, while some existing plans are scheduled to end later. Borrowers pursuing PSLF should therefore review how their repayment plan fits their individual circumstances.

Keep records of important notices and changes affecting your account. If your payment count changes, investigate the reason rather than assuming the change is permanent.

Finally, be cautious with companies promising guaranteed student loan forgiveness. You can access official PSLF resources directly through Federal Student Aid without paying a third party to explain basic eligibility requirements.

What is Trump’s new student loan forgiveness?

The phrase “Trump’s new student loan forgiveness” can be misleading because there is not one new program that simply replaces Public Service Loan Forgiveness. Instead, the Trump administration has implemented broader federal student loan changes through legislation and Department of Education regulations.

The Working Families Tax Cuts Act introduced significant changes to federal student lending and repayment. Regulations effective July 1, 2026, established new repayment options, including the Repayment Assistance Plan and Tiered Standard plan, while phasing out certain existing plans.

PSLF itself continues as a separate statutory forgiveness program. Eligible borrowers still need qualifying Direct Loans, qualifying employment, and 120 qualifying monthly payments.

The administration has also pursued changes affecting which organizations can qualify as PSLF employers. However, a federal court vacated a related final rule shortly before its planned July 2026 effective date, and the Department subsequently moved to revise the PSLF form.

Therefore, borrowers should distinguish between PSLF, broader repayment reforms, and other federal loan relief programs.

Navigating Policy Shifts and Waivers

Federal student loan policy can change quickly. Following outdated PSLF information can therefore create unnecessary risks. Borrowers should verify their repayment plan, employer eligibility, and qualifying payment count through current federal resources.

In 2026, the Department of Education introduced the Repayment Assistance Plan and Tiered Standard plan. The department also began phasing out several older repayment options. Some existing plans will end no later than July 1, 2028.

PSLF borrowers should carefully review how these changes affect future qualifying payments. Your loan type, borrowing history, income, and other circumstances can influence which repayment option fits your situation. Keeping track of your overall financial position also makes understanding your assets and liabilities easier.

Court decisions can also change how federal agencies apply student loan rules. For example, a federal court vacated a PSLF employer-related final rule before its planned July 2026 effective date. The Department of Education then sought changes to the PSLF certification form to address the court’s decision.

Accurate documentation offers the best protection. Save employment certifications, payment records, account notices, and official correspondence. Check StudentAid.gov regularly before changing your repayment strategy or assuming a new policy changes your eligibility.


FAQ

What happens if I miss a monthly payment?

Missing a monthly payment means that specific month will not count toward your required 120 payments. To stay on track, you must make consecutive or cumulative qualifying payments rather than relying on grace periods. Setting up automatic debit can prevent accidental missed deadlines.

Can part-time employment count toward qualification?

Part-time jobs generally do not qualify unless you work multiple part-time positions for eligible employers totaling at least 30 hours per week. Your combined hours must meet the standard definition of full-time work established by your employers.

Do payments need to be consecutive?

Your 120 qualifying payments do not need to occur consecutively to qualify for PSLF forgiveness. If you leave public service or change employers, you can return to qualifying employment later. Your previous qualifying payments can still count toward the 120-payment requirement, provided they met the program rules when you made them.

Are Parent PLUS Loans Eligible for This Program?

Direct Parent PLUS Loans do not qualify directly for Public Service Loan Forgiveness (PSLF). However, borrowers can consolidate these loans into a Direct Consolidation Loan. After consolidation, the borrower must use the Income-Contingent Repayment (ICR) Plan to pursue PSLF. Qualifying employment and monthly payment requirements still apply.


Conclusion

Mastering Public Service Loan Forgiveness provides a clear pathway to eliminating student debt while building a meaningful career. By understanding qualifying employment, maintaining accurate paperwork, and tracking your monthly progress, you secure your financial independence. The journey requires patience and attention to detail, but the ultimate reward of debt freedom is well worth the effort. Apply these insights today by verifying your loan types and setting up your annual employment certification routine. Take control of your financial future and let your public service work for you.

Best Places to Keep Your Savings Safely: Ultimate Guide

What is the Best Place to Keep Your Savings Safely?

Finding the right spot for your hard-earned cash is one of the most important financial decisions you will ever make. When you want the best places to keep your savings safely, you must balance security with growth. According to the Federal Deposit Insurance Corporation, traditional banking institutions offer unmatched protection for your principal balance. Whether you are building an emergency fund or saving for a major milestone, knowing where to park your funds prevents unnecessary financial stress. This comprehensive article explores the safest vehicles, smart money rules, high-yield accounts, and structured monthly saving schemes designed to keep your wealth secure.

What Is the Safest Place to Keep Savings Money?

When security is your top priority, federally insured deposit accounts are among the safest places to keep savings. In the United States, FDIC-insured banks protect eligible deposits up to applicable coverage limits. NCUA-insured credit unions provide similar protection for eligible deposits. This coverage helps protect your money if a covered financial institution fails.

Traditional savings accounts, money market deposit accounts, and certificates of deposit can all provide this type of protection when offered by an insured institution. However, federal insurance does not protect unlimited amounts. You should understand the applicable coverage limits and account ownership rules before depositing large sums.

These accounts also keep your money separate from market investments. Your balance does not normally rise or fall with stock prices. They can therefore work well for emergency funds, short-term goals, and cash you cannot afford to lose.

For maximum safety, verify that your bank or credit union is federally insured. Also, keep your balance within applicable insurance limits whenever possible.

Maximizing Protection Through Federal Insurance Coverage

Federal deposit insurance can provide an important layer of protection for your savings. However, simply having several accounts at the same bank does not automatically multiply your coverage. Insurance limits generally depend on the depositor, ownership category, and institution.

If you have more money than the applicable insurance limit, consider spreading eligible deposits across separately insured institutions. Different ownership categories may also receive separate coverage under applicable rules.

Before moving money, check the current FDIC or NCUA coverage rules. Your bank or credit union can also explain how your accounts are categorized. This matters because account structures can affect how much of your money receives insurance protection.

For example, keeping excess cash at multiple qualifying institutions may help you remain within applicable coverage limits. You should not assume that every financial product offered by a bank is insured. Stocks, bonds, mutual funds, and other investments generally do not receive FDIC or NCUA deposit insurance.

The goal is simple: understand where your money sits, determine whether it is insured, and stay within the relevant limits.

What Is the 7-7-7 Rule for Money?

The 7-7-7 rule for money is not a universally standardized financial rule. Different personal finance sources use the term to describe different saving or budgeting approaches. Therefore, you should verify which version a particular source means before applying it to your finances.

Some versions use three separate financial priorities. These may include building savings, preparing for long-term goals, and allowing money for personal spending. The broader idea is to divide your financial resources deliberately instead of treating all available money as spendable.

A structured approach can help you build better habits. It can also reduce the risk of ignoring emergency savings while focusing entirely on retirement or investments. However, there is no single percentage allocation that works for everyone.

Your income, debt, expenses, emergency fund, and financial goals should determine your actual allocation. Someone with expensive debt may need a different approach from someone with stable income and substantial savings.

Use the 7-7-7 concept as a budgeting framework, rather than a guaranteed formula for building wealth.

Applying the Three-Part Framework to Daily Finances

If you use a three-part savings framework, start by identifying your most important financial priorities. Emergency savings should generally come before aggressive long-term investing when you have little accessible cash.

You can then divide your monthly surplus between short-term savings and long-term financial goals and discretionary spending. The exact percentages should reflect your circumstances rather than an arbitrary formula.

For example, you might direct part of each paycheck toward an emergency fund. Another portion could support retirement or other long-term investments. The remaining amount could cover planned personal spending.

Automation can make this process easier. Schedule transfers shortly after receiving your income so saving happens before unnecessary spending.

Review the allocation regularly as your income and expenses change. A new job, major purchase, debt repayment, or family responsibility may require adjustments.

The main benefit is consistency. A simple framework gives each dollar a purpose and helps prevent short-term spending from consuming money intended for future goals.

Where Is the Safest Place to Keep a Lot of Money?

Keeping a large amount of money requires more planning than choosing a standard savings account. The first priority should be determining how much protection your deposits receive. Large balances can exceed standard federal insurance limits, creating additional exposure if everything is held at one institution.

For substantial cash holdings, you may consider several options. These can include multiple federally insured bank accounts, insured cash sweep arrangements, Treasury bills, and other appropriate short-term government securities.

Treasury bills are short-term U.S. government securities. They are generally considered very low-risk because they are backed by the U.S. government. However, they are investments rather than bank deposits, so they do not receive FDIC insurance.

Money market mutual funds are another option, but they are also investments. Their balances are not protected by FDIC or NCUA deposit insurance. They can therefore behave differently from insured bank deposit accounts.

For large sums, the right strategy depends on safety, liquidity, taxes, and time horizon. Avoid assuming that a product is insured simply because a bank or financial institution sells it.

Utilizing Treasury Bills for Government-Backed Security

U.S. Treasury bills can be useful when you want to hold significant cash outside a traditional deposit account. They are short-term government securities with maturities ranging from several weeks to one year.

Treasury bills are backed by the U.S. government’s ability to meet its obligations. This makes them widely regarded as one of the lower-risk options for preserving capital over short periods.

However, Treasury bills are not identical to savings accounts. You purchase a security and generally hold it until maturity or sell it before maturity. Their prices can vary if you sell before maturity.

They also do not provide the same instant account access as a regular savings account. You should therefore consider when you will need the money before choosing a maturity period.

For large cash balances, Treasury bills can complement insured bank deposits. For example, you might keep your emergency cash in an insured savings account while using short-term Treasury bills for money you will not need immediately.

The key is matching the investment with your cash-flow needs and time horizon. Safety does not mean every option works equally well for every purpose.

Where Is the Best Place to Keep Savings?

The best place to keep savings depends on when you need the money and how much access you require. There is no single account that is automatically best for everyone.

For emergency savings and short-term goals, a high-yield savings account can offer a useful combination of accessibility and interest earnings. These accounts may pay more interest than traditional savings accounts, although rates can change over time.

If you do not need immediate access to your money, a certificate of deposit may be another option. CDs generally provide a fixed interest rate for a specific term. You can also compare CDs with other savings and investment choices using FD vs mutual fund returns. In exchange, withdrawing money early may result in a penalty.

Traditional savings accounts can still be useful when convenience and branch access matter more than maximizing interest. The difference in rates should be weighed against account requirements and fees.

When comparing accounts, look beyond the advertised interest rate. Check the annual percentage yield, minimum balance requirements, withdrawal restrictions, fees, and insurance status.

Your savings strategy should also separate emergency money from long-term investments. Cash needed soon should not depend on stock-market performance.

Choosing Between Flexible Savings and Fixed Certificates

High-yield savings accounts and certificates of deposit serve different purposes. Comparing FD and mutual fund returns can also help you understand how deposit-based savings options differ from market-linked investments when choosing the right place for each portion of your savings.

A high-yield savings account generally provides easier access to your money. You can usually make withdrawals or transfers when needed, subject to the account’s terms and applicable rules. The interest rate can change over time.

A CD typically requires you to keep your money deposited for a specified term. In return, you may receive a fixed interest rate for that period. Early withdrawal can result in a penalty, depending on the account.

Consider a savings account for your emergency fund and near-term expenses. A CD may suit money you know you will not need until a specific future date.

You can also use both options. Keep immediately accessible savings in a high-yield account and place some longer-term cash into CDs.

Before opening either account, compare rates, fees, terms, minimum deposits, and insurance coverage. The highest advertised rate is not always the best choice if the account has restrictions that do not fit your needs.

Best Bank Investment Plans

Bank investment plans can help you pursue long-term financial goals, but they are fundamentally different from insured savings accounts. Investment products can include mutual funds, bonds, stocks, structured products, and professionally managed portfolios. Comparing SIPs and fixed deposits can help you understand how different options balance potential returns and risk. Their potential returns come with varying levels of risk.

The right investment strategy depends on your time horizon, financial goals, and tolerance for losses. Money needed for an emergency or near-term purchase generally should not be placed in volatile investments.

For long-term goals such as retirement, diversified investments may provide greater growth potential than keeping all your money in cash. However, market values can fall, sometimes significantly.

Banks may offer investment services, but the fact that an investment is sold through a bank does not make it federally insured. FDIC insurance generally covers eligible deposits, not market investments.

Before selecting an investment plan, understand its fees, risks, expected time horizon, and underlying assets. Avoid choosing a product simply because a bank employee recommends it.

A suitable portfolio should reflect your broader financial plan. Diversification can reduce concentration risk, but it cannot eliminate investment losses or guarantee returns.

Diversifying Your Portfolio for Balanced Growth

Diversification means spreading your investments across different assets rather than relying heavily on one investment. It can help reduce the impact of a poor performance from a single company, sector, or asset class.

A diversified portfolio might contain a combination of stocks, bonds, and other suitable investments. The appropriate mix depends on your financial goals and risk tolerance.

You can also diversify within an asset class. For example, stock exposure can be spread across different companies, industries, and geographic markets. Bond investments can vary by issuer, maturity, and credit quality.

However, diversification does not guarantee profits. A broad portfolio can still decline during a major market downturn. Its main purpose is to reduce concentration risk and create a more balanced exposure to different sources of return.

Review your portfolio periodically rather than reacting to every short-term market movement. Your allocation may need adjustment as your goals, income, or time horizon changes.

For long-term investors, diversification can provide a more disciplined approach to investing. It is generally more reliable than trying to predict which single investment will perform best.

Best Monthly Saving Scheme

Choosing among the Best Places to Keep Your Savings Safely also means finding a savings method you can maintain consistently. A monthly savings scheme turns saving into a regular financial habit. Understanding short-term and long-term savings goals can help you decide how much to save and where to keep it. Instead of deciding how much to save each month, you set a predetermined contribution and automate the process.

You can use this approach with a savings account, recurring deposit, or another suitable savings product. The right choice depends on your country, financial institution, interest rates, account terms, and personal goals. Always check whether the product provides applicable deposit insurance or other protections.

Regular contributions can help your savings grow steadily over time. They also reduce the temptation to spend money that you intended to save. When comparing the Best Places to Keep Your Savings Safely, consider more than the interest rate.

Check the maturity period, withdrawal rules, minimum contribution, fees, penalties, and insurance status. For short-term goals, prioritize liquidity and capital safety. For longer-term goals, investments may offer greater growth potential but also involve market risk.

A monthly savings plan works best when the contribution fits your budget. Consistent saving is usually more sustainable than an unrealistic target that you cannot maintain.

Automating Deposits to Build Effortless Saving Habits

Automation can make saving easier by removing repeated decisions from your monthly routine. You can schedule a recurring transfer from your primary account to a dedicated savings account after receiving your income.

This approach supports the pay-yourself-first strategy. Instead of saving whatever remains after spending, you set aside your planned amount first. This can help you make steady progress toward emergency funds and short-term and long-term financial goals.

When reviewing the Best Places to Keep Your Savings Safely, consider accounts that support automatic transfers. Start with an amount you can comfortably maintain. If your income or expenses change, adjust the transfer to protect your cash flow.

You can also create separate accounts for different goals. One account could hold your emergency fund, while another supports a planned purchase or annual expense.

Review your automated transfers regularly. Check the account’s interest rate, fees, withdrawal conditions, and insurance status. Remember that automation does not replace a budget. You still need to monitor spending, debt, and overall financial progress.

The goal is to make saving easier to repeat. A consistent automated contribution can turn saving into a long-term habit and help you choose the Best Places to Keep Your Savings Safely.

Frequently Asked Questions

What Is the Difference Between a Savings Account and a CD?

When comparing the Best Places to Keep Your Savings Safely, a savings account offers more flexibility than a certificate of deposit (CD). You can usually deposit or withdraw money from a savings account when needed, while its interest rate may change over time. A CD requires you to keep your money deposited for a fixed period. In return, it may provide a guaranteed interest rate. Early CD withdrawals can result in penalties. Savings accounts generally suit emergency funds, while CDs can work well for planned expenses.

Are Online Banks Safe for Holding Large Savings?

When considering the Best Places to Keep Your Savings Safely, online banks can be a secure option. The key factor is whether the institution carries appropriate federal deposit insurance. In the United States, eligible deposits at FDIC-insured banks receive protection within applicable limits. Credit unions may provide NCUA insurance instead. Online banks can also offer competitive interest rates because they often have lower operating costs. Before depositing a large amount, verify the institution’s insurance status and understand the applicable coverage limits. Do not assume every financial product offered online is insured.

How Much Money Should I Keep in a Liquid Savings Account?

Choosing the Best Places to Keep Your Savings Safely also means deciding how much money should remain easily accessible. A common guideline is to keep around three to six months of essential living expenses in an emergency fund. Your personal situation may require more or less. Consider your income stability, household expenses, debt, and job security when setting the target. Keep this money in a liquid account where you can access it without selling investments or paying an early withdrawal penalty. The purpose is to cover unexpected expenses without disrupting your long-term financial plans.

Can I Lose Money in a High-Yield Savings Account?

Among the Best Places to Keep Your Savings Safely, a federally insured high-yield savings account can provide strong protection for eligible deposits. However, the statement that you can never lose money needs an important qualification. Federal deposit insurance protects eligible deposits within applicable coverage limits, but not every financial product labeled as a savings product is insured. Interest rates can also change, affecting how quickly your balance grows. Unlike stocks or mutual funds, an insured savings deposit is not directly exposed to daily market price fluctuations. Always verify the institution’s insurance status and applicable coverage limits.

Conclusion

Choosing the Best Places to Keep Your Savings Safely requires more than selecting the account with the highest advertised interest rate. You should consider security, accessibility, insurance coverage, fees, and your financial timeline before making a decision. Federally insured savings accounts can provide a strong foundation for emergency funds and short-term goals. CDs may suit money you can leave untouched for a fixed period. Treasury bills and diversified investments may serve different long-term purposes. The right approach is to match each portion of your money with its specific purpose. Review your current savings strategy, automate regular contributions, and keep your cash in suitable financial vehicles.

Good Debt vs Bad Debt Explained: A Complete Guide

Good Debt vs Bad Debt Explained: How to Borrow Wisely

Understanding the concept of good debt vs bad debt explained clearly can completely transform your personal financial journey. Many people view all borrowing as stressful or harmful. However, financial experts and institutions like the Consumer Financial Protection Bureau emphasize that not all liabilities are created equal. Borrowing money strategically can help build long-term wealth, while reckless borrowing can drain your resources rapidly. Knowing the distinction helps you make smarter choices every single day. This comprehensive guide answers what is an example of good debt vs bad debt, what are the four types of debt, how much money is considered bad debt, what is an example of good debt, and reviews essential good debt vs bad debt examples to keep your budget safe and secure.

Good Debt vs Bad Debt Explained: Examples, Types, and Risks


What Is an Example of Good Debt vs Bad Debt?

Good debt vs bad debt often depends on what the borrowed money helps you achieve. Good debt can increase your net worth, improve earning potential, or create future value. A common example is a low-interest mortgage used to buy a home that may appreciate over time.

Bad debt usually pays for items or experiences that lose value quickly. For example, using a high-interest credit card to fund a luxury vacation creates debt without producing a financial return. The interest can also make the purchase much more expensive.

When comparing the two, consider what you receive in return for borrowing money. Ask yourself:

  • Will the purchase increase in value?
  • Can it generate income?
  • Could it improve your future earning potential?
  • Is the interest rate reasonable?

Identifying Value Versus Depreciation

To identify good debt, examine what you acquire with the borrowed funds. An asset that generates income, appreciates, or supports your career may provide long-term value. For a clearer understanding of how these financial concepts connect, see Understanding Assets and Liabilities for Beginners.

By contrast, depreciating purchases with high interest costs can quickly become financial burdens. Understanding this difference helps you make more informed borrowing decisions.

What Are the Four Types of Debt?

Personal finance commonly divides debt into four major categories based on how the money is borrowed and used. Revolving debt allows you to borrow repeatedly up to a specific credit limit. Credit cards are the most common example, and balances can carry over from month to month.

Installment debt provides a fixed amount that you repay through scheduled payments. Auto loans and personal loans commonly fall into this category.

Mortgages are another type of installment borrowing, but they are specifically secured by real estate. They usually have longer repayment periods than other consumer loans.

Finally, student loans help borrowers pay for higher education, training, or career development. Their value depends partly on the education’s cost and its potential effect on future income. For more detailed guidance, see Student Loan Guidelines 2026: Everything You Need to Know.

Categorizing Your Financial Obligations

Knowing your debt type makes repayment planning easier. High-interest revolving debt often deserves priority because interest can accumulate quickly.

Installment loans usually offer predictable payments, which can make monthly budgeting simpler. However, the interest rate, loan term, and purpose still matter when evaluating the debt.

How Much Money Is Considered Bad Debt?

There is no specific dollar amount that automatically makes debt bad. Instead, financial risk depends on factors such as your income, interest rates, monthly expenses, and ability to repay the balance.

High-interest consumer debt can become especially risky when payments begin consuming money needed for essential expenses. Large credit card balances can also become expensive when annual percentage rates are high.

Rather than focusing only on the balance, consider how the debt affects your overall cash flow. A manageable loan payment may fit comfortably within your budget. The same payment could create serious pressure for someone with lower income or higher living costs.

Your debt-to-income ratio (DTI) is another useful measure. It compares your monthly debt payments with your gross monthly income.

Assessing Your Debt-to-Income Ratio

A lower DTI generally gives you more financial flexibility. Many lenders view a DTI below 36% as a healthier range, although standards vary by lender and loan type.

If debt payments consume too much of your income, consider reducing borrowing, increasing payments, or restructuring expensive balances. A practical budgeting approach can also help you manage these obligations alongside your regular expenses.

What Is an Example of Good Debt?

A common example of good debt is a student loan used for valuable education or professional training. A degree, certification, or specialized program may increase your skills and improve your long-term earning potential.

However, education debt is not automatically good. The cost of the program, expected income, repayment terms, and career opportunities should all be considered before borrowing.

A business loan can also represent good debt when it funds equipment, technology, inventory, or another investment that supports growth. If the investment improves efficiency or increases revenue, the borrowing may create meaningful long-term value.

The key is to compare the expected benefits with the total borrowing cost. Interest, fees, and repayment obligations can reduce your eventual return.

Maximizing Educational and Career Investments

Before borrowing for education or business expansion, research the likely financial outcome. Compare program costs with expected salaries and employment demand. For education-related borrowing, Managing Education Expenses Wisely: A Complete Guide can provide additional guidance.

For business borrowing, estimate whether the investment can produce enough additional revenue to justify its cost. Careful planning helps ensure that debt supports your financial goals rather than limiting them.

Good Debt vs Bad Debt Examples

Practical examples make the difference between good debt and bad debt easier to understand. A modest home purchased with a manageable mortgage may be considered good debt when the property provides housing value and potentially appreciates over time.

Financing reliable transportation can also be reasonable when the vehicle is necessary for employment and the loan fits your budget. However, this does not make every auto loan good debt.

Bad debt often involves expensive borrowing for purchases that provide little lasting financial value. Examples include luxury purchases charged to high-interest credit cards, lavish weddings financed through loans, or payday loans used for nonessential expenses.

Practical Budgeting for Everyday Purchases

Before using credit, consider the purchase’s long-term value. Ask whether it supports your income, builds an asset, or simply provides short-term enjoyment. Comparing needs vs. wants can also help you avoid unnecessary borrowing for discretionary purchases.

For everyday depreciating goods, paying with available cash can help prevent unnecessary interest charges. Most importantly, focus on affordability, interest costs, and purpose rather than labeling every type of debt as automatically good or bad.

FAQ SECTION

How can I pay off bad debt quickly?

Start by listing all your high-interest balances and choose between the debt avalanche or debt snowball repayment methods. Dedicate extra cash flow each month strictly to the highest-interest balance while paying minimums on the rest. Cutting unnecessary monthly expenses accelerates this elimination process significantly.

Does good debt affect my credit score?

Yes, managing good debt responsibly through on-time monthly payments significantly improves your credit score. Lenders view timely mortgage or student loan payments as proof of reliability. Keeping these accounts active and well-managed demonstrates strong creditworthiness to future financial institutions.

Can good debt turn into bad debt?

An obligation can become harmful if your personal financial circumstances change unexpectedly. For instance, a low-interest mortgage can strain your budget if you lose your primary source of income. Always maintain an emergency fund to protect your beneficial borrowing commitments.

Is a car loan considered good or bad?

A car loan sits in a middle ground depending entirely on your specific lifestyle and transportation needs. If a dependable vehicle is strictly necessary to reach your job and earn an income, it functions as a helpful tool. If you purchase an expensive luxury vehicle that drains your savings, it acts as bad debt.

Conclusion

Mastering the principles behind good debt vs bad debt explained throughout this guide empowers you to take control of your financial destiny. By distinguishing between liabilities that build long-term value and those that drain your resources, you can make informed borrowing decisions. Remember that strategic borrowing like mortgages or education can elevate your financial standing, while high-interest consumer borrowing requires extreme caution. Apply these insights to evaluate your current financial portfolio, prioritize high-interest liabilities, and build a secure, prosperous future. Consistent, smart management of your financial obligations is the ultimate key to achieving lasting peace of mind and enduring wealth.

Risk vs Return in Investing: Complete Beginner’s Guide

Understanding Risk vs Return in Investing: A Complete Guide

When you start your wealth-building journey, understanding risk vs return in investing is the single most important concept to master. Every financial decision you make balances the danger of losing capital against the potential reward of financial growth. Without grasping this fundamental trade-off, building a resilient, long-term portfolio becomes nearly impossible. According to the Securities and Exchange Commission, virtually all investments carry some degree of risk, and higher potential returns almost always require accepting higher uncertainty. This comprehensive article answers the core questions every smart investor asks, including the differences between risk and return, popular allocation frameworks like the 70-20-10 and 40-40-20 rules, the seven types of risks, measurement techniques, and practical real-world examples.

What Is the Difference Between Risk and Return in Investing?

Risk and return are two of the most important concepts in investing. They help investors understand the potential rewards and possible losses associated with an investment. Return refers to the gain or loss generated over a specific period. It can include capital appreciation, dividends, and interest income. For investors comparing relatively stable and growth-oriented options, FD vs Mutual Fund Returns can provide useful context.

Investment risk refers to the uncertainty surrounding those returns. It includes the possibility that actual returns may be lower than expected. In some cases, investors can also lose part or all of their original investment.

Generally, investments with higher potential returns also involve greater uncertainty. However, higher risk does not guarantee higher returns. An investment can carry substantial risk and still perform poorly.

Understanding the risk-return relationship helps investors choose assets that match their financial goals, investment horizon, and tolerance for losses. A balanced approach is usually more useful than simply chasing the highest possible return. This also means developing good financial habits that build wealth rather than making investment decisions based only on short-term returns.

The Trade-Off Mechanics

The basic risk-return principle suggests that investors usually demand greater potential compensation for accepting greater uncertainty. Lower-risk investments, such as high-quality government securities, generally offer more predictable income. Their long-term growth potential may also be lower.

Higher-risk investments, including equities and some speculative assets, can experience much larger price movements. They may generate strong returns over time, but losses can also be substantial during market downturns.

This does not mean investors should automatically choose higher-risk assets. Risk tolerance depends on personal circumstances, including income, financial goals, investment horizon, and ability to absorb losses.

For example, a young investor with a long time horizon may tolerate more equity-market volatility. Someone approaching retirement may prioritize capital preservation instead.

The key is to understand what you are giving up when seeking higher returns. Greater return potential usually comes with greater uncertainty, not a guaranteed reward. Diversification can help manage this trade-off without eliminating investment risk completely.

What Is the 70-20-10 Rule for Investing?

The 70-20-10 rule is a portfolio allocation approach that divides investments into three broad categories. However, it is not a universal investing rule or a scientifically established formula. Its usefulness depends on an investor’s goals, risk tolerance, and financial situation.

Under this framework, 70% of the portfolio may be allocated to relatively established investments. These could include broad-market index funds, diversified large-cap stocks, or other core holdings. The next 20% can target additional diversification or moderate growth opportunities.

The remaining 10% may be allocated to higher-risk investments. Examples include speculative stocks, emerging technologies, or other assets with substantial volatility.

The purpose is to create a core-and-satellite portfolio. Most capital remains in diversified core investments, while a smaller portion can pursue higher growth potential.

Investors should not treat these percentages as fixed requirements. Asset allocation should reflect financial goals, time horizon, risk capacity, and the investor’s need for liquidity.

Core Portfolio Stability

The 70% core allocation is intended to provide the foundation of the portfolio. Holding diversified, established investments can reduce dependence on a small number of speculative assets. However, it cannot prevent losses during a broad market decline.

A core portfolio might include diversified index funds, high-quality bonds, or established companies. The exact mix should depend on the investor’s objectives and risk profile.

The smaller allocations can then provide exposure to areas with different return characteristics. This structure may help investors participate in growth opportunities without placing their entire portfolio in highly volatile assets.

However, calling the core portion completely safe would be misleading. Stocks can decline sharply, even when they represent established companies. Bonds can also lose value when interest rates rise.

The main benefit is diversification rather than guaranteed stability. Investors should also review fees, taxes, liquidity, and concentration risk before selecting individual investments.

A sensible portfolio should protect against excessive exposure while still providing enough growth potential to meet long-term financial goals.

What Are the 7 Types of Risks?

Investors face several types of risk, and these risks can affect different assets in different ways. Market risk refers to losses caused by broad market movements. Economic conditions, investor sentiment, and corporate earnings can all influence market prices.

Credit risk is the possibility that a borrower or bond issuer fails to meet its obligations. Liquidity risk occurs when an investor cannot sell an asset quickly at a reasonable price.

Inflation risk reduces purchasing power when investment returns fail to keep pace with rising prices. Interest rate risk is especially important for bonds because changing rates can affect their market values.

Currency risk affects international investments when exchange-rate movements change the value of returns. Political and regulatory risk can arise when government policies, taxes, or regulations affect an investment.

These risks can overlap. Understanding them helps investors evaluate potential losses before investing. No strategy can eliminate every type of risk, so investors should focus on managing risk rather than expecting to remove it completely.

Mitigating Market Threats

Diversification is one of the most practical ways to manage investment risk. Instead of concentrating money in one company, industry, asset class, or country, investors can spread exposure across different investments.

For example, a diversified portfolio might contain domestic and international equities, bonds, and cash or cash equivalents. These assets may respond differently to economic events.

Diversification does not guarantee profits or prevent losses. A broad market decline can still reduce the value of a diversified portfolio. However, diversification can reduce the impact of problems affecting a single investment.

Investors should also consider their investment horizon. Short-term goals may require more stable and liquid assets because there is less time to recover from market declines. Understanding short-term vs long-term savings can help investors match their savings strategy with the time horizon of each financial goal.

Regular portfolio reviews can help identify excessive concentration. Rebalancing may also restore the intended asset allocation after large market movements.

The goal is not to avoid every loss. Instead, effective risk management aims to ensure that one unexpected event does not cause damage that permanently derails long-term financial plans.

What Is the 40-40-20 Rule in Investing?

The 40-40-20 rule is another asset allocation framework that divides a portfolio among domestic equities, fixed-income investments, and international equities. Like the 70-20-10 approach, it should not be treated as a universal formula.

Under this framework, 40% of the portfolio is allocated to domestic stocks. Another 40% goes toward bonds or other fixed-income investments. The remaining 20% is allocated to international equities.

The intended purpose is to combine growth, income, and geographic diversification. Domestic equities can provide exposure to the investor’s home economy. Bonds may provide income and reduce overall portfolio volatility. International equities can add exposure to different economies and markets.

However, the appropriate allocation varies between investors. A portfolio for a 25-year-old investor may look very different from one designed for someone nearing retirement.

Investors should also consider inflation, taxes, currency movements, bond duration, and the specific funds or securities they choose. Asset allocation should be personalized, rather than followed mechanically.

International Exposure Benefits

International investments can provide diversification because foreign markets do not always move in the same direction as the investor’s domestic market. Exposure to different economies can therefore reduce dependence on one country’s economic performance.

For example, a domestic recession may affect local companies while some foreign markets continue growing. International holdings could potentially offset part of that weakness.

However, international diversification introduces additional risks. Currency movements can increase or reduce investment returns when foreign assets are converted into the investor’s home currency.

Foreign markets may also have different political conditions, regulations, accounting standards, and economic structures. Some markets can be less liquid or more volatile than developed domestic markets.

For these reasons, international exposure should be considered as part of an overall diversification strategy. A 20% allocation is not automatically appropriate for every investor.

The right percentage depends on the investor’s objectives, existing portfolio, risk tolerance, and investment horizon. International funds can provide a convenient way to gain diversified global exposure without selecting individual foreign stocks.

How Are Risk and Return Measured in Investing?

Measuring risk and return helps investors compare investments more systematically. Investment return can be measured using total return, which includes both price changes and income such as dividends or interest. Using these comparisons alongside a SIP vs FD calculator can help investors evaluate potential outcomes more systematically.

Investors may also use annualized returns to compare investments held for different periods. Compound annual growth rate, or CAGR, shows the annualized rate required to grow an investment from its starting value to its ending value over a specified period.

Risk can be measured in several ways. Standard deviation measures how widely returns have historically varied around their average. A higher standard deviation generally indicates greater historical volatility.

Other measures provide different perspectives. The Sharpe ratio compares excess return with the volatility taken to achieve it. Maximum drawdown measures the largest historical decline from a peak to a subsequent low.

No single metric captures every type of investment risk. Historical volatility also does not guarantee future behavior. Investors should therefore combine quantitative measures with factors such as liquidity, credit quality, time horizon, and economic conditions.

Utilizing Standard Deviation

Standard deviation is commonly used to evaluate the historical volatility of an investment. It shows how widely an asset’s returns have moved around its average return during a particular period.

A higher standard deviation generally means the investment experienced larger historical fluctuations. A lower value indicates that returns were more stable during the period measured.

However, standard deviation is not a complete measure of investment risk. It treats upward and downward movements as volatility, even though investors may view gains differently from losses.

It also relies on historical data. Future market conditions can differ significantly from the past. An investment with low historical volatility can still experience a sudden decline.

Investors should therefore use standard deviation alongside other measures. These may include maximum drawdown, credit risk, liquidity, and the Sharpe ratio.

The most useful question is not simply whether an investment has high or low volatility. Instead, investors should ask whether its historical risk characteristics fit their financial goals and ability to withstand losses.

What Is the Relationship Between Risk and Return? Example

The relationship between risk and return is often described as a trade-off. Investments with greater uncertainty may offer higher potential returns because investors require compensation for accepting additional risk.

However, this relationship is not a guarantee that higher risk produces higher returns. Riskier investments can lose money or underperform for long periods.

Consider two hypothetical investments. Option A is an insured certificate of deposit offering a 4% annual return, subject to applicable terms and insurance limits. Option B is an emerging-market equity fund that could potentially earn 15% in a strong year but could also experience a 20% decline during a market downturn.

The second investment has greater return potential, but it also carries substantially more uncertainty. An investor’s choice should depend on their financial goals, time horizon, and ability to tolerate losses.

Someone with a short-term financial need may prefer greater stability. A long-term investor may accept greater equity volatility in pursuit of higher growth potential.

The example shows why risk and return should be evaluated together, rather than focusing only on headline returns.

Real-World Asset Comparison

A comparison between cash savings and equities helps illustrate the risk-return relationship. Cash and savings deposits generally provide greater stability and liquidity, but their returns may be modest and may not always keep pace with inflation. This distinction is also important when deciding whether an emergency fund or savings should be prioritized for short-term financial security.

Equities can experience significant short-term declines. However, they have historically provided stronger long-term growth potential than cash in many markets. Past performance does not guarantee future results.

The difference becomes especially important when considering an investor’s time horizon. Someone saving for a purchase next year may have little capacity to tolerate a major market decline.

An investor saving for a goal several decades away may have more time to recover from temporary losses. Even then, the investor must be able to remain invested during periods of severe volatility. For shorter-term financial needs, building an emergency fund can provide accessible reserves without requiring the investor to sell volatile assets during a downturn.

The key lesson is that risk should match the investor’s circumstances. There is no single asset allocation that works for everyone.

Instead of chasing the highest possible return, investors should consider expected return, downside risk, diversification, liquidity, taxes, and their ability to stay invested through market cycles.

Frequently Asked Questions

What Is a Good Risk-to-Reward Ratio in Investing?

There is no single risk-to-reward ratio that guarantees investment success. A commonly used benchmark is 1:2, meaning you target ₹2 of potential profit for every ₹1 you are willing to risk. This concept is more useful for individual trades than long-term investing. In Risk vs Return in Investing, both potential return and the probability of achieving it matter. A favorable ratio does not make a trade profitable by itself.

How Does Time Horizon Affect Investment Risk?

Your investment time horizon can strongly influence how much market volatility you can tolerate. A longer horizon gives investments more time to recover from temporary declines, but it does not eliminate risk. This is important when considering Risk vs Return in Investing. For example, an investor with a 20-year goal may tolerate greater equity volatility than someone needing money within two years. Longer periods can also allow compounding to work, but markets can still experience prolonged downturns.

Can You Achieve High Returns With Zero Risk?

No, consistently achieving high returns with zero risk is not realistic in legitimate financial markets. Higher potential returns usually involve greater uncertainty, although taking more risk does not guarantee higher returns. This principle is central to Risk vs Return in Investing. Relatively safe investments, such as certain government securities, generally offer lower expected returns. Be cautious of investments promising unusually high guaranteed returns. Such claims may indicate excessive risk, misleading marketing, or potential investment fraud.

How Do I Determine My Personal Risk Tolerance?

Your personal risk tolerance depends on your financial goals, investment timeframe, income stability, savings, and ability to handle losses. Your emotional response to market declines also matters. If a 10% decline would cause you to sell immediately, an aggressive portfolio may not suit you. However, Risk vs Return in Investing also requires considering risk capacity. You may feel comfortable taking high risks but still lack the financial ability to absorb major losses. A suitable portfolio should balance both factors.

Conclusion

Understanding Risk vs Return in Investing helps investors make better decisions about potential gains and possible losses. This guide covered the core relationship between risk and return, asset allocation strategies, seven major investment risks, and common methods for measuring volatility. We also examined how time horizon and personal risk tolerance affect investment choices. Successful investing is not about eliminating risk. It is about understanding, measuring, and managing risk while pursuing realistic long-term returns. Use Risk vs Return in Investing as a framework for building a portfolio that fits your financial goals, time horizon, and ability to withstand market losses.

Envelope Budgeting Method: Is It Still Effective?

Envelope Budgeting Method: Is It Still Effective?

Managing personal finances often feels overwhelming with endless digital transactions and automated payments. Many people search for a reliable way to regain control over their spending habits and save more money. According to the Consumer Financial Protection Bureau, structured budgeting strategies significantly improve long-term financial stability and reduce household debt. The envelope budgeting method has stood the test of time as a tangible strategy for tracking expenses and curbing impulse purchases. This comprehensive guide answers the most important questions about the envelope budgeting method, exploring how the strategy functions in today’s digital economy, examining popular alternative money rules like the 70/20/10 framework, and reviewing which financial institutions and applications support modern cash tracking.

What Is the Envelope Method of Budgeting?

The envelope method of budgeting is a cash-management strategy that divides your income into specific spending categories. Each category receives a fixed amount based on your monthly budget. For a broader introduction to budgeting principles, see What Is Budgeting? A Beginner’s Guide to Managing Money.

Traditionally, you place physical cash into labeled envelopes for expenses such as groceries, entertainment, dining out, clothing, and transportation. You then spend only the money assigned to each category. When an envelope becomes empty, you stop spending in that category until the next budgeting period.

The method creates clear spending limits and makes your available money easier to understand. It can also reduce impulse spending because each purchase directly reduces the cash available for that category.

You normally pay fixed bills first, then allocate your remaining discretionary money. The system works best when your categories reflect your actual spending habits.

Unlike a general spending plan, the envelope system gives every category a defined limit. This makes overspending easier to identify before it becomes a problem.

The Psychology Behind Physical Cash Spending

Physical cash can make spending feel more tangible because you can see your money leaving your hands. This is often called the pain of paying. Digital payments can feel less immediate because the money exists mainly as a number on a screen.

When you physically hand over cash, the transaction becomes more noticeable. That extra awareness may encourage you to pause before making an unnecessary purchase.

The effect is particularly useful for discretionary categories. These include dining out, entertainment, shopping, and other expenses that can easily exceed a planned budget. Learning to distinguish between essential purchases and discretionary spending can also help; Needs vs Wants: How to Spend Money Wisely explores this distinction in more detail.

However, cash is not automatically better for everyone. Some people manage money more effectively through banking apps and automatic transaction tracking.

The key benefit is the spending boundary. Physical envelopes make that boundary visible and immediate. Digital envelopes can create a similar structure when they clearly show how much remains in each category.


Does the Envelope System Really Work?

The envelope budgeting system can work well for people who frequently overspend in flexible categories. Its main advantage is simplicity. Instead of checking a large account balance, you can look at the amount remaining for a specific expense.

For example, suppose you allocate ₹8,000 for groceries. Once that category reaches zero, you know that your planned grocery budget has been used. This creates a clear decision point before you spend more.

The method can also help identify spending patterns. If you repeatedly run out of money for dining out, your budget may need adjustment.

However, the system is not automatically effective. It requires accurate category planning, regular reviews, and enough discipline to respect the limits. Physical cash can also become inconvenient for online purchases and recurring payments.

The best approach depends on your spending habits. People who need stronger spending boundaries may benefit from physical envelopes. Others may prefer digital tools that provide similar controls without requiring cash.

Overcoming the Inconveniences of Carrying Cash

Carrying cash can create practical problems. It may be inconvenient for online purchases, recurring subscriptions, large payments, and situations where merchants prefer digital transactions.

You can reduce these problems by keeping physical cash only for categories where you tend to overspend. For example, you might use envelopes for groceries, entertainment, and dining while paying fixed bills electronically.

You also do not need to carry every envelope with you. Keep the cash for less frequently used categories in a secure location at home. Take only the money needed for your planned errands.

Another option is to combine physical and digital budgeting. Use cash for discretionary spending and a bank account for fixed expenses.

Review your envelopes once a week. Check whether you are spending faster than expected and adjust future allocations when necessary.

The goal is not to make your finances unnecessarily complicated. The goal is to create spending limits that you can actually follow.


What Is the 70/20/10 Rule for Money?

The 70/20/10 rule is a percentage-based budgeting framework that divides monthly net income into three broad categories. Unlike envelope budgeting, it does not require you to assign a specific cash amount to every individual expense.

Under the version described here, 70% of income covers regular living expenses and everyday needs. This can include housing, utilities, groceries, transportation, insurance, and other essential costs.

Another 20% is directed toward financial priorities. These may include retirement contributions, emergency savings, or debt payments above required minimums.

The remaining 10% can support charitable giving, personal development, or discretionary spending, depending on your priorities.

The percentages are guidelines rather than universal rules. Your housing costs, debt obligations, income level, and financial goals may require different allocations.

For someone with variable expenses, percentage budgeting can provide a flexible starting point. You can calculate each category from your actual monthly income instead of rebuilding a fixed-dollar budget every time your earnings change.

Adapting Percentage Rules for Variable Income

Percentage-based budgeting can be useful when your income changes from month to month. Freelancers, commission-based workers, contractors, and business owners may find fixed monthly spending limits difficult to maintain.

Instead of assigning the same dollar amount every month, you can calculate your budget after receiving your income. The percentages then scale with your available money.

For example, a lower-income month produces smaller allocations. A stronger month produces larger allocations while maintaining the same general structure.

However, variable income requires another safeguard. Your essential expenses may not decrease as quickly as your income. Rent, insurance, and debt payments can remain fixed even during a weaker month.

For that reason, build an emergency fund before relying heavily on percentage rules. You can also calculate your essential monthly expenses and establish a minimum income threshold. For more guidance, How to Build an Emergency Fund: Risk, Returns & Liquidity explains how to approach this financial safety net.

The 70/20/10 framework should therefore serve as a starting point, not a rigid formula. Adjust the percentages when your financial circumstances require it.


Which Banks Offer the Envelope Budget System?

Most traditional banks do not provide literal physical budgeting envelopes. Instead, some banks and financial platforms offer digital features that divide money into categories.

For example, Ally Bank currently offers Spending Buckets within its Spending Account. Customers can allocate money toward expenses such as groceries, bills, and other planned spending. Ally also offers savings buckets for separate financial goals.

These features resemble digital envelopes because they organize money by purpose. However, they do not necessarily impose the same hard spending restriction as physical cash. Ally notes that transactions can still use available funds outside a particular bucket.

Qube Money also focuses on digital cash-envelope budgeting. Its current Qube+ product lets users organize money into Bills, Spend, and Goals categories while connecting existing financial accounts.

Before choosing a platform, check availability, fees, account requirements, transaction rules, and supported financial institutions.

Choosing the Right Feature Set for Your Needs

The best digital envelope system is not necessarily the one with the most features. It is the one that matches how you actually manage money.

Start by identifying the categories where you need the most control. If groceries and dining are your problem areas, prioritize clear spending categories and real-time transaction visibility.

If your main goal is saving, look for tools that separate savings goals from everyday spending. Automatic transfers can also reduce the need for manual budgeting. You can also compare different approaches in Short-Term vs Long-Term Savings: Mastering Your Goals.

Before opening an account or subscribing to an app, review:

  • Monthly or annual fees
  • Account minimums
  • ATM availability
  • Transaction limits
  • Bank-account compatibility
  • Automatic transfer options
  • Mobile-app functionality
  • Rules for moving money between categories

Also check whether the digital envelopes actually restrict spending or simply organize your balance. That distinction matters.

A tool that only labels your money may not provide enough control if you frequently overspend. Choose a system that creates the level of accountability you need without making everyday banking unnecessarily difficult.


Digital Envelope Budgeting

Digital envelope budgeting recreates the basic structure of physical envelopes through a banking app, budgeting application, or spreadsheet. Instead of placing cash into separate envelopes, you assign money to virtual categories.

For example, you could create categories for groceries, transportation, entertainment, clothing, and household expenses. Each category receives a planned amount based on your income and expected spending.

Digital systems remove several problems associated with physical cash. You do not need to visit an ATM, carry large amounts of money, or keep multiple envelopes at home.

Some platforms also connect with financial accounts and track transactions automatically. Goodbudget, for example, is designed around the envelope budgeting method and supports budgeting across web and mobile platforms.

The biggest advantage is convenience. You can review category balances from your phone and update your budget without handling physical currency.

However, digital budgeting can feel less restrictive. A card transaction may not create the same psychological reaction as spending cash. Strong notifications, regular reviews, and clear category limits can help close that gap.

Maintaining Awareness Without Physical Cash

The biggest challenge with digital envelope budgeting is maintaining spending awareness. When you pay with a card, the transaction can feel disconnected from the remaining amount in your budget.

You can reduce this problem by turning on transaction notifications. Seeing a purchase immediately can make your spending more visible.

Another useful habit is checking your category balances before making discretionary purchases. Do not wait until the end of the month to discover that you have exceeded your planned limit. For additional practical strategies, 7 Money Saving Tips You Must Know: Your Finance Guide covers ways to reduce unnecessary spending.

You can also schedule a short weekly budget review. Compare your actual spending with the amount remaining in each category.

For example, if your entertainment budget is ₹3,000 and you have already spent ₹2,500, you know that only ₹500 remains. That information can influence your next decision.

Some digital systems also allow you to record transactions before they fully clear. This can make your category balance more responsive to your actual spending decisions.

The objective is to recreate the awareness of physical cash while keeping the convenience of digital payments.


Free Envelope Budgeting Apps

A free envelope budgeting app can help you test the method without adding another subscription to your monthly expenses. Free options are useful when you are unsure whether envelope budgeting fits your habits. If you want to compare more budgeting tools, see Best Budgeting Apps for Students: Track & Save Money.

Goodbudget is one established option built specifically around the envelope budgeting approach. Its platform is available on the web, Android, and iPhone, and it allows users to organize spending through digital envelopes.

Free plans can be enough for simple household budgeting. However, they may include restrictions on the number of envelopes, accounts, or automated features available.

Before choosing an app, decide whether you need automatic bank synchronization. Manual tracking may be sufficient if you have a small number of transactions and want stronger awareness of your spending.

If you prefer automation, compare the available bank connections and transaction features before committing.

Avoid choosing an app simply because it advertises itself as free. Review what the free version actually includes and whether important features require payment.

The best free budgeting app is the one you can use consistently without making your budgeting routine unnecessarily complicated.

Maximizing Free-Tier Features for Success

Free budgeting tools often provide enough functionality for beginners, but you may need to manage transactions manually. That can feel inconvenient at first, yet it can also increase awareness of where your money goes.

Start with a small number of categories. Create envelopes only for expenses that require active control. Too many categories can make budgeting difficult to maintain.

Set aside a few minutes each week to review your transactions. Enter missing expenses, compare category balances, and identify areas where spending is running ahead of plan.

You can also use receipts and bank statements to improve accuracy. Keep your digital balances updated rather than relying on memory.

If an app offers transaction synchronization on its free tier, enable it and still review the imported transactions regularly. Automatic categorization can occasionally place purchases in the wrong category.

Once you understand your spending patterns, decide whether you actually need premium features. Paying for software is not automatically an improvement.

A simple system that you use every week is more valuable than an advanced budgeting app that you abandon after a month.


FAQ SECTION

Can I use the envelope budgeting method if I pay most of my bills online?

Yes, you can easily adapt the envelope budgeting method for online bill payments by using a hybrid approach. Keep physical cash exclusively for discretionary categories like dining out and groceries, while managing fixed monthly bills through designated checking account sub-accounts or digital software tools. This separation ensures your essential housing and utility obligations are met automatically without requiring cash withdrawals for digital transactions.

How do I handle unexpected expenses that do not fit my current envelopes?

Unexpected expenses require you to practice flexibility by reallocating funds from a lower-priority envelope to cover the emerging cost. If your car needs an unexpected repair, pull the necessary money from your entertainment or clothing envelope for that month. To prevent this from disrupting your core budget, establish a miscellaneous buffer envelope specifically designed to absorb small, unforeseen daily surprises.

What happens to leftover money in my envelopes at the end of the month?

Leftover money at the end of the month gives you complete flexibility to choose between several strategic financial moves. You can roll the remaining balance over into the same category for the upcoming month to build a larger safety cushion. Alternatively, you can sweep the surplus funds directly into your savings account or put them toward accelerating your current debt payoff goals.

Is the envelope budgeting method suitable for high-income earners?

The envelope budgeting method works exceptionally well for high-income earners who want to curb lifestyle inflation and build intentional spending habits. High earners often struggle with unconscious spending because discretionary funds feel limitless on digital cards. Establishing strict category limits restores mindfulness, ensuring that surplus income actively contributes to long-term wealth creation rather than disappearing into unmonitored purchases.


Conclusion

Mastering your personal finances requires intentional strategies that align with your spending psychology and long-term goals. The envelope budgeting method remains a remarkably effective tool for building financial discipline, whether you choose traditional physical cash or modern digital applications. By setting clear boundaries for your discretionary spending and eliminating unconscious purchases, you take active control of your financial future. Reflect on your current spending habits, select the digital or physical tracking style that fits your lifestyle best, and start applying these principles today to watch your savings grow.

Modern Asset Allocation Strategies for Beginners

Understanding Modern Asset Allocation Strategies for Beginners

Stepping into the world of investing can feel overwhelming without a clear roadmap. Modern asset allocation strategies help beginners divide their money across various asset classes to balance potential risks and rewards. Understanding how to distribute your capital correctly is essential for long-term financial growth and stability. Whether you are building your first portfolio from scratch or refining an existing plan, knowing the right frameworks makes all the difference. This comprehensive guide answers critical questions about Warren Buffett’s 90/10 rule, the 40-40-20 rule, Harry Markowitz’s Modern Portfolio Theory, the 70/30 strategy, and other primary types of asset allocation strategies. For official regulatory context on financial markets and investor protection, you can visit the U.S. Securities and Exchange Commission. By exploring these time-tested methods, you will gain the knowledge needed to make confident, informed investment decisions that align with your personal financial goals.

What Is Warren Buffett’s 90/10 Rule?

Warren Buffett’s 90/10 rule is a simple investment strategy for people who prefer a hands-off approach to building wealth. Buffett has recommended that the trustee of his estate invest 90% of the cash designated for his wife in a very low-cost S&P 500 index fund. The remaining 10% should go into short-term U.S. government bonds. The idea is to avoid stock picking, market timing, and unnecessary fund-management costs.

A 90/10 portfolio puts most assets in equities, giving investors broad exposure to large U.S. companies and their long-term growth potential. The bond allocation adds a modest layer of stability and liquidity during market declines. However, this strategy can still experience substantial losses because 90% remains invested in stocks.

The approach rests on three principles: low costs, broad diversification, and long-term discipline. It is simple, but it is not suitable for every investor or every time horizon.

Why Low-Cost Index Funds Drive the Strategy

Low-cost index funds are central to Buffett’s 90/10 approach because fees directly reduce investment returns. Even small annual expenses can compound into a meaningful difference over several decades. An index fund also removes the need to identify individual stocks or predict which companies will outperform, which is particularly relevant when comparing FD and mutual fund returns.

An S&P 500 index fund provides exposure to leading U.S. companies across multiple industries. This broad exposure reduces the impact of a single company performing poorly. However, diversification does not eliminate market risk, and the fund remains concentrated in U.S. large-cap stocks.

The main benefits of low-cost index investing include:

  • Lower fees: More of the portfolio’s return stays invested.
  • Broad diversification: One fund can provide exposure to many companies.
  • Simplicity: Investors do not need to research individual stocks.
  • Consistency: The fund follows a defined market index instead of relying on manager decisions.

For long-term investors, controlling costs can be more dependable than trying to beat the market.


What Is the 40/40/20 Rule in Investing?

The 40/40/20 rule in investing is a portfolio allocation framework that divides capital among three broad buckets. However, there is no single, universally accepted 40/40/20 formula. One common interpretation uses 40% large-cap domestic equities, 40% international or growth-oriented assets, and 20% fixed-income securities or cash equivalents.

The purpose is to spread risk across different asset classes and geographic exposures. The equity portions provide most of the portfolio’s growth potential, while the 20% defensive allocation can provide stability and liquidity during difficult markets.

This framework can help investors maintain discipline because it creates clear target weights. Still, the right allocation depends on factors such as:

  • Risk tolerance
  • Investment horizon
  • Financial goals
  • Need for near-term cash
  • Tax considerations

Investors should also remember that international, growth, and fixed-income assets carry different risks. A fixed allocation does not guarantee profits or prevent losses.

Balancing Risk Through Strategic Capital Splits

Balancing risk through strategic capital splits requires investors to monitor their target allocation and rebalance when necessary. Rebalancing means bringing the portfolio back toward its intended percentages after market movements cause them to drift.

For example, suppose an investor starts with 40% domestic equities, 40% international or growth assets, and 20% bonds or cash. If stocks rise sharply, equities may become a much larger share of the portfolio. The investor could then sell some of the overweight assets and add to the underweight allocation.

This process can help maintain the portfolio’s intended risk level. It can also create a disciplined pattern of trimming assets after strong performance and adding to assets that have fallen.

Many investors review their allocation once or twice a year instead of making frequent changes. The key is to follow a clear rule instead of reacting emotionally to market headlines. Rebalancing should also account for taxes, transaction costs, and the investor’s circumstances.


What Is Harry Markowitz’s Modern Portfolio Theory?

Harry Markowitz’s Modern Portfolio Theory (MPT) is a foundational framework for understanding how diversification can improve portfolio construction. Markowitz introduced the theory in 1952, arguing that investors should evaluate each holding by how it affects the risk and return of the entire portfolio.

An asset with high individual volatility may still improve a portfolio if its returns do not closely track the portfolio’s other holdings. Combining assets with different correlations can therefore reduce overall portfolio volatility. Stocks and bonds are a common example, although their relationship can change over time.

MPT introduced the concept of the efficient frontier. It represents portfolios that aim to provide the highest expected return for a given level of risk.

The theory does not promise a specific return or eliminate losses. Instead, it provides a framework for thinking about diversification, correlation, expected returns, and risk. Its central lesson is that portfolio construction matters, not just individual security selection.

Understanding Asset Correlation in Portfolio Construction

Asset correlation measures how closely two investments tend to move relative to each other over time. Correlation ranges from -1 to +1. A correlation near +1 means two assets tend to move together, while a correlation near -1 indicates opposite movements.

This concept matters because combining assets with lower correlations can reduce portfolio volatility. If one investment falls while another remains stable or rises, the overall portfolio may experience a smaller decline than a concentrated portfolio.

Relationships between stocks, bonds, commodities, and international markets can change during different economic environments. Assets that appeared diversified in one period may move together during a severe market shock.

Investors should therefore avoid assuming that diversification guarantees protection. Asset correlation is one tool for evaluating investment relationships, alongside liquidity, valuation, credit risk, and investment horizon. This makes correlation especially important when designing a diversified investment portfolio.


What Is a 70/30 Investment Strategy?

A 70/30 investment strategy allocates 70% of a portfolio to growth-oriented assets, usually stocks, and 30% to more conservative assets, such as bonds or cash equivalents. For investors evaluating different ways to build wealth, understanding how FD and mutual fund returns compare can also help when considering the role of conservative and growth-oriented assets.

The 70% equity allocation gives the portfolio substantial exposure to corporate earnings and economic growth. The 30% defensive allocation can provide income, liquidity, and some diversification when stock markets decline. However, the bond portion does not guarantee that the portfolio will avoid losses.

A 70/30 portfolio may suit investors who want meaningful growth but do not want the full volatility of an all-stock portfolio. It can also serve as a starting framework for investors with a medium- or long-term horizon.

Still, there is no universal “correct” allocation. Investors should consider:

  • Time horizon
  • Risk capacity and tolerance
  • Income needs
  • Financial goals
  • Other assets and liabilities

The allocation should fit the investor.

Choosing the Right Mix for Your Timeline

Choosing the right 70/30 mix depends heavily on your investment timeline and financial goals. An investor with several decades before needing the money may have enough time to recover from major stock-market declines. Someone approaching retirement may have less time to recover and may need greater portfolio stability, making retirement planning across different ages an important consideration.

A 70/30 allocation can reduce equity exposure compared with a 100% stock portfolio, but it can still experience meaningful losses during severe market downturns.

Your decision should consider more than age alone. Think about when you will need the money, how much income you require, and whether you could stay invested during a major decline.

As a goal approaches, some investors gradually increase their allocation to bonds or cash. Others keep a consistent allocation and rebalance regularly. The right approach depends on the goal and the investor’s ability to tolerate volatility. Regular reviews can keep the allocation aligned with changing needs.


Types of Asset Allocation Strategies

Types of asset allocation strategies differ mainly in how actively investors adjust their portfolio weights. Strategic asset allocation sets a long-term target mix and periodically rebalances back to those targets.

Tactical asset allocation allows temporary changes from the target mix when an investor expects certain opportunities or risks. Constant-weighting strategies maintain target percentages through regular rebalancing. Insured asset allocation focuses on maintaining a portfolio floor and increasing defensive positioning if the portfolio approaches that level.

Dynamic asset allocation changes portfolio weights more actively as market conditions, valuations, or economic factors change.

Each method has trade-offs:

  • Strategic: Simple and disciplined.
  • Tactical: Flexible but more difficult to execute.
  • Constant-weighting: Systematic but requires regular monitoring.
  • Insured: Focuses on protecting a minimum value.
  • Dynamic: Responsive but more dependent on forecasts.

No strategy guarantees better returns. The choice should match the investor’s objectives and capacity for risk.

Selecting the Best Strategy for Your Goals

Selecting the best asset allocation strategy depends on your goals, risk tolerance, time horizon, and ability to manage the portfolio.

Beginners may prefer strategic asset allocation because it provides clear target percentages and reduces the temptation to react to short-term market movements. A diversified mix of stock and bond funds can be easier to maintain than a portfolio requiring frequent decisions.

More experienced investors may consider tactical or dynamic approaches. These methods require more research, monitoring, and discipline. Incorrect forecasts can reduce returns and increase risk.

Before choosing a strategy, consider:

  • When you need the money
  • How much loss you can financially tolerate
  • How much volatility you can emotionally tolerate
  • Whether you need regular income
  • How often you are willing to review the portfolio

The best strategy is usually one you can maintain through both strong markets and severe downturns.


FAQ SECTION

How Often Should I Rebalance My Investment Portfolio?

You should generally review and rebalance your portfolio once or twice a year, or when an asset class moves significantly away from its target allocation. A common guideline is a 5% deviation, but there is no universal threshold. Rebalancing helps maintain your intended risk level and supports disciplined Modern Asset Allocation Strategies. Avoid making frequent changes because of short-term market movements, which can increase costs and encourage emotional decisions.

Is Asset Allocation More Important Than Stock Picking?

For most long-term investors, asset allocation is more important than trying to select individual winning stocks. Your mix of stocks, bonds, and other assets strongly influences your portfolio’s overall risk and return characteristics. Modern Asset Allocation Strategies emphasize diversification rather than relying on a few successful investments. Stock picking can produce higher returns, but it also creates concentration risk and requires significant research. A diversified allocation provides a more systematic approach to managing investment risk.

Can Beginners Start Investing With a Small Amount of Money?

Yes, beginners can start investing with relatively small amounts of money. Many investment platforms provide fractional shares, while low-cost index funds and ETFs can offer diversified exposure without requiring a large initial investment. Modern Asset Allocation Strategies can be adapted to smaller portfolios by using broad, low-cost funds. Starting early can also matter more than starting with a large amount because consistent contributions and long-term compounding can gradually build wealth.

What Is the Difference Between Stocks and Bonds in a Portfolio?

Stocks represent ownership in companies and generally offer greater long-term growth potential, but they also experience higher price volatility. Bonds represent loans to governments or companies and typically provide interest income while offering different risk characteristics from stocks. Modern Asset Allocation Strategies often combine both assets to balance growth and stability. Stocks can drive long-term capital appreciation, while high-quality bonds may provide income, diversification, and liquidity during periods of market stress.


Conclusion

Understanding Modern Asset Allocation Strategies can help investors build portfolios that match their goals, time horizons, and risk tolerance. Warren Buffett’s 90/10 rule, the 40/40/20 framework, Markowitz’s Modern Portfolio Theory, and the 70/30 strategy illustrate different approaches to diversification. None guarantees profits or eliminates investment risk. The most important step is choosing an allocation you can maintain through market ups and downs. Focus on reasonable diversification, low costs, regular reviews, and disciplined rebalancing. Modern Asset Allocation Strategies work best when applied consistently rather than changed whenever markets become uncertain. For beginners, starting with a simple portfolio and gradually increasing contributions can provide a practical foundation for long-term retirement planning.

Improving Your Credit Score Fast: Expert Guide

A Beginner Guide to Improving Your Credit Score Fast

Improving your credit score fast can create better financial opportunities. A stronger credit profile may help when you apply for a home loan, car loan, or credit card. It can also help you qualify for more favorable borrowing terms.

This beginner-friendly guide explains practical ways to improve your credit score. You will learn how to raise your credit score immediately, reach a 900 CIBIL score, and potentially raise your score significantly within 30 days.

We will also cover how to get a 700 credit score in 3 months, improving your credit score fast in India, and how to increase your CIBIL score from 750 to 800. These strategies focus on responsible borrowing, timely payments, lower credit utilization, and accurate credit-report information.

For reliable information about consumer credit and financial rights, you can also consult the Consumer Financial Protection Bureau. However, readers in India should prioritize guidance from relevant Indian credit bureaus and financial institutions.

How Do I Raise My Credit Score Immediately?

Raising your credit score immediately is possible in some cases, but there is no guaranteed instant fix. The fastest gains usually come from correcting inaccurate information or reducing reported credit card balances. For practical guidance on handling card balances and borrowing responsibly, see credit card tips you need to know. Credit scoring models consider payment history, balances, account age, credit mix, and recent applications.

Start by checking your latest credit report. Look for incorrect late payments, unfamiliar accounts, outdated balances, or other reporting errors. If you find an error, dispute it with the bureau and the lender that supplied the information. A correction can improve your score after the report updates.

If your revolving balances are high, pay them down before the lender reports the next balance. Keeping utilization below 30% is a useful target, while lower utilization can be better. Paying off debt and clearing balances quickly can also help you manage high-interest obligations more effectively. However, no utilization percentage guarantees a specific score increase.

Avoid unnecessary new credit applications while trying to improve your score. Most importantly, continue making every payment on time.

Requesting Rapid Rescoring Through Your Lenders

Rapid rescoring can help when you are applying for a mortgage and need an updated credit profile quickly. Consumers generally cannot order it directly. Instead, the mortgage lender requests the expedited update from the credit bureau. If you are preparing for a home purchase, mindful tips for buying your first home can also help you think through the broader financial planning involved.

The process usually involves paying down a balance or resolving another issue affecting your application. You then provide documentation, such as payment confirmation, to the lender. The lender submits the information for an expedited update.

Rapid rescoring is mainly useful when a small score change could affect mortgage approval or loan terms. It does not guarantee a higher score because results depend on the information changed and the scoring model.

If you are not applying for a mortgage, focus on normal reporting cycles. Ask your lender when it reports updated balances. Paying a balance does not always mean your credit report changes the same day.

For most borrowers, reducing debt and correcting genuine errors remain the practical priorities.


How to Get a 900 CIBIL Score?

A 900 CIBIL score is the top of TransUnion CIBIL’s current scoring range, which runs from 300 to 900. Reaching 900 is possible, but it is not a practical target for most borrowers.

The foundation is a long record of on-time payments. Pay every credit card bill and loan EMI by the due date. Keep credit card balances low compared with their limits. Lower utilization can support a healthier profile.

You should also avoid unnecessary loan and credit card applications. Multiple enquiries within a short period can affect your CIBIL score. Maintain a sensible mix of secured and unsecured credit when it naturally fits your needs.

Most importantly, give your credit history time. There is no legitimate shortcut that guarantees a 900 score. Focus on habits that reduce risk and build a reliable record.

Maintaining Old Credit Accounts for Maximum History

Older accounts can support your credit profile because they contribute to the age and depth of your credit history. However, keeping every old account open is not always necessary. Consider the account’s fees, terms, usefulness, and effect on your finances.

If an older credit card has no meaningful annual fee and you can manage it responsibly, keeping it open may preserve useful history. Use it occasionally if needed, then pay the balance on time. Avoid carrying debt just to keep an account active.

Closing an account can also change your available credit and affect utilization. The effect varies by credit report and scoring model. Therefore, do not close an old card solely because you rarely use it.

The better strategy is to maintain suitable long-standing accounts while avoiding unnecessary fees and debt. A strong credit history comes from consistent repayment behavior over time, not simply from keeping the oldest account open.


How to Raise Your Credit Score 100 Points in 30 Days?

A 100-point credit score increase in 30 days is possible for some people, but it is not guaranteed. Large changes are more plausible when your score was recently hurt by high balances or inaccurate information. A clean report with low utilization usually offers fewer opportunities for rapid growth.

First, check your credit reports and identify the reason for your current score. If credit card balances are high, reduce them before the lender reports the next statement balance. This can lower reported utilization and may improve the score after an update.

Next, dispute genuine errors, such as accounts you do not recognize or payments reported incorrectly. Do not dispute accurate negative information simply because it hurts your score.

Avoid unnecessary credit applications during the month. New enquiries and accounts can affect your profile. If your score does not rise by 100 points, your actions may still have improved your financial position.

Becoming an Authorized User for Quick Points

Becoming an authorized user can sometimes help build or strengthen a credit profile, but it is not a guaranteed way to gain points quickly. The effect depends on whether the account is reported to the relevant credit bureau and how the scoring model treats the information.

If you use this strategy, choose a trusted person with a long-standing account, strong payment history, and low utilization. Avoid joining an account with missed payments, high balances, or other negative information. Those details could work against you if they appear on your report.

Ask the card issuer whether authorized-user activity is reported to the bureaus before relying on the strategy. Being an authorized user also does not necessarily make you responsible for the account’s debt.

Do not pay someone simply for access to their credit history. It works best as a supplement to your own positive payment history.


How to Get a 700 Credit Score in 3 Months?

Reaching a 700 credit score within three months can be realistic for some borrowers, but it depends heavily on your starting score and history. Someone with high card balances may improve faster than someone with serious recent defaults. No method can guarantee a 700 score within 90 days.

Start by putting every account on automatic payment or calendar reminders. Your goal is to avoid new late payments. Then reduce high credit card utilization as quickly as your budget allows. Arranging your budget effectively can make it easier to prioritize debt payments while keeping essential expenses covered. Check when your lenders typically report balances because the reported balance can differ from the amount due.

If you have little or no credit history, a secured credit card may help establish reported payment activity. Use it lightly and pay on time. Do not open several accounts at once.

Review your credit report for genuine errors and dispute them through the appropriate process. Avoid unnecessary applications while improving your profile.

Utilizing Secured Credit Cards for Fast Recovery

A secured credit card can help when you have limited or damaged credit history. It usually requires a refundable security deposit, which often determines the card’s credit limit. The issuer may then report your account activity to credit bureaus.

Use the card for small, planned purchases rather than treating it as extra spending money. Pay the bill on time and keep the balance low. Paying the statement balance in full can help you avoid interest while building a positive payment record.

Before applying, confirm that the issuer reports activity to the credit bureaus. Compare fees, interest rates, deposit requirements, and upgrade policies. A secured card is not automatically beneficial if fees are excessive or activity is not reported.

A secured card will not create an instant score jump. Its value comes from adding positive information to your credit history over time. Combine it with low utilization, timely payments, and limited new applications.


Improving Your Credit Score Fast in India

Improving your credit score quickly in India starts with understanding what appears on your credit report. TransUnion CIBIL calculates its score on a 300-to-900 scale using information in your credit history. Other bureaus may produce different scores.

Begin by reviewing your CIBIL report for missed payments, incorrect balances, unfamiliar accounts, and inaccurate enquiries. CIBIL states that lenders submit account data periodically, so a recent payment may take time to appear. If you find an error, raise a dispute and provide supporting documents.

If an account is marked settled, contact the lender about clearing the remaining amount. CIBIL advises paying the full outstanding balance and asking the lender to update the status where appropriate. Do not assume the bureau can independently change accurate lender data.

Avoid multiple credit applications within a short period. Maintain timely EMI and card payments, keep balances controlled, and borrow only when necessary. Managing your finances wisely can help you maintain these habits and make more informed borrowing decisions.

Clearing Settled Accounts to Restore Trust

A settled account can make your credit profile less attractive because it shows that the lender accepted less than the originally agreed repayment amount. TransUnion CIBIL advises consumers with settled accounts to pay the remaining balance and contact the lender about removing the settled status where appropriate.

If you have a settled account, ask the lender for the exact outstanding amount and the steps required to close the account. Keep payment receipts and written confirmation. After the lender updates its records, check your CIBIL report again.

Do not assume that paying the balance instantly erases the account’s historical information. Credit reports contain account history, and updates depend on lender reporting. CIBIL also notes that it cannot directly change lender-supplied data without authorization from the credit institution.

Once the account is correctly updated, focus on building positive history. Pay current dues on time, keep card utilization manageable, and avoid unnecessary applications. If you are working through multiple balances, paying off your debt and tracking your progress can help you stay focused on reducing what you owe.


How to Increase CIBIL Score From 750 to 800?

Moving a CIBIL score from 750 to 800 is possible, but no action guarantees a 50-point increase. A score of 750 is already strong, so further gains may take more time. The best approach is to protect your existing record while reducing factors that may hold it back.

Keep credit card balances low relative to your limits. CIBIL recommends controlling credit utilization, but no universal percentage guarantees a particular score. Paying balances before reporting dates may help if high reported balances are the issue.

Continue making every EMI and card payment on time. Avoid unnecessary loan or credit card applications because repeated enquiries can affect your score. Review your report regularly for incorrect information or enquiries you did not authorize.

Scoring models consider multiple factors, and the ideal profile varies by person. Focus on steady improvement rather than chasing a perfect score.

Monitoring Credit Health and Preventing Hard Inquiries

Once your CIBIL score is around 750 or higher, preventing unnecessary damage becomes as important as seeking further gains. Start by checking your credit report regularly and confirming that balances, payment history, and enquiries are accurate. Personal finance apps can also help you monitor spending, budgets, and other aspects of your financial activity.

Avoid applying for several loans or credit cards in a short period. CIBIL records lender enquiries, and multiple applications close together can affect your score. Apply only when the credit is genuinely useful.

Keep existing credit card balances under control. A temporary increase in spending can raise reported utilization even when you pay the bill later. If needed, make payments earlier so the reported balance remains manageable.

Watch for unfamiliar enquiries or accounts. If something does not belong to you, contact the lender and raise a dispute with the relevant bureau. Keep records of your requests and documents.

A stable payment record matters more than small score fluctuations.


FAQ SECTION

What Happens to My Credit Score When I Close an Old Credit Card?

Closing an old credit card can affect your credit profile, especially if the card has a high credit limit or a long history. Once closed, you lose that available credit, which can increase your overall credit utilization ratio if you have balances on other cards. The effect on account age can also vary by credit bureau and scoring model. Before closing an old card, consider its annual fee, credit limit, and usefulness. If it has no fee and remains manageable, keeping it open may support your credit profile. However, you should never keep an unnecessary card solely to improve your score.

Do Checking and Savings Account Balances Affect My Credit Score?

Checking and savings account balances generally do not directly affect your credit score. Credit bureaus primarily use information about your borrowing and repayment behavior, such as credit cards, loans, payment history, and credit utilization. However, bank balances can still matter when you apply for certain loans. Lenders may review your income, savings, account statements, and cash flow during their underwriting process. Therefore, having healthy savings can strengthen your overall financial position even though it does not directly raise your credit score. If your goal is Improving Your Credit Score Fast, focus first on timely payments, manageable debt, and accurate credit-report information.

How Long Do Negative Marks Stay on My Credit Report?

There is no single universal rule that says every negative credit entry remains for exactly seven years. Reporting periods depend on the country, credit bureau, type of information, and applicable rules. In India, lenders and credit bureaus maintain credit information according to applicable reporting requirements and their records. A missed payment, default, or settlement can continue to appear in your credit history after the underlying issue is resolved. However, its effect on your credit profile can change as newer positive information is added. If you notice inaccurate or outdated negative information, contact the lender and raise a dispute with the relevant credit bureau. Accurate information generally cannot simply be removed because it is unfavorable.

Does Checking My Own Credit Score Lower It?

Checking your own credit score does not normally lower your credit score. When you access your own credit report or score through a credit bureau or consumer service, it is generally treated as a soft inquiry rather than a lender’s credit application inquiry. Lenders may perform a hard inquiry when you apply for a new loan or credit card, and multiple applications can affect your credit profile. Therefore, regularly monitoring your own report is a useful part of Improving Your Credit Score Fast. It can also help you identify unfamiliar accounts, incorrect payment information, or unauthorized enquiries before they create bigger problems.


Conclusion

Improving Your Credit Score Fast requires targeted actions rather than shortcuts. The fastest improvements usually come from correcting genuine reporting errors and reducing high credit card balances. However, your payment history remains one of the most important parts of a healthy credit profile.

Throughout this guide, we covered practical ways to improve your credit score, increase your CIBIL score, and build stronger credit habits in India. We also examined strategies involving credit utilization, old accounts, secured credit cards, credit enquiries, and settled accounts.

Start by checking your credit report for inaccurate information. Then, make every EMI and credit card payment on time. Keep your revolving balances manageable and avoid unnecessary loan applications.

Remember that Improving Your Credit Score Fast does not always mean seeing a dramatic increase within days. Some changes require several reporting cycles. Focus on consistent financial behavior rather than chasing a specific score.

Over time, these habits can strengthen your credit profile and improve your chances of receiving better borrowing terms.

How to Pay Off Debt Faster and Clear Balances Quickly

How to Pay Off Debt Faster: Your Ultimate Guide to Financial Freedom

Managing financial obligations can feel overwhelming, but learning how to pay off debt faster changes everything. When balances linger, interest charges drain your hard-earned money and delay your long-term goals. Taking control of your financial health reduces stress and opens doors to true stability. According to the Consumer Financial Protection Bureau, proactive planning is crucial for tackling high-interest balances effectively. Whether you are dealing with credit cards or personal loans, this guide answers critical questions about the quickest way to pay off debt, how much debt is normal, handling $30,000 balances in a year, and managing repayments with bad credit or low income. Let us dive into the proven methods that make financial freedom possible.

How to Pay Off Debt Fast: Practical Strategies for Becoming Debt-Free

What is the quickest way to pay off debt?

The quickest way to pay off debt is to combine aggressive repayment, controlled spending, and consistent payments. Start by listing every balance, interest rate, minimum payment, and due date. This gives you a clear view of your financial obligations. For a broader look at repayment strategies, see our guide to simple ways to overcome your debt.

Next, choose a repayment strategy. The debt avalanche method focuses on the highest interest rate first. The debt snowball method targets the smallest balance first. Both can work, but the avalanche usually reduces total interest costs.

Pay more than the minimum whenever possible. Extra payments reduce your principal balance and can lower future interest charges. Automating minimum payments also helps prevent missed deadlines and late fees.

Look for temporary ways to increase your monthly payment. Cutting unnecessary subscriptions, reducing dining expenses, or directing bonuses toward debt can accelerate progress. A structured budget can make it easier to identify where those savings can come from.

Avoid adding new debt during repayment. Your goal should be to create a consistent gap between your income and expenses. Then direct that surplus toward your balances every month.

The Power of the Debt Avalanche Method

The debt avalanche method prioritizes debts with the highest interest rates. You continue making minimum payments on every other account. Any extra money goes toward the balance charging the most interest.

This approach is mathematically efficient because expensive interest receives attention first. Once that balance disappears, you redirect its payment toward the next-highest interest debt. The process continues until every balance is cleared.

For example, suppose you have a credit card at 24% interest and a loan at 8%. The avalanche method attacks the credit card first. This can reduce the amount of interest paid over the entire repayment period.

The strategy may feel slower at first if the highest-rate balance is large. However, it can save more money than focusing only on small balances.

For people who prefer quick psychological wins, the debt snowball can still be useful. The best method is the one you can follow consistently without adding new debt.

Is $20,000 in debt a lot?

Having $20,000 in debt is not automatically excessive or manageable. The real impact depends on your income, interest rates, monthly payments, and type of debt. A $20,000 student loan can have a very different effect from $20,000 in high-interest credit card debt.

High-interest credit card balances deserve particular attention. Interest can accumulate quickly when you carry a balance from month to month. Paying only minimum amounts can also extend the repayment period significantly. Following credit card tips can help you avoid making the balance harder to repay.

Your income matters just as much. Someone earning $8,000 per month may handle $20,000 differently from someone earning $2,500. Monthly living costs also determine how much money remains for repayment.

Instead of comparing your balance with someone else’s, examine your debt-to-income ratio and monthly cash flow. List your required payments and compare them with your gross monthly income.

Then determine how much you can realistically pay beyond the minimum. A clear budget will show whether your debt is manageable or requires immediate spending cuts and income increases.

Evaluating Your Debt-to-Income Ratio

Your debt-to-income ratio (DTI) compares your monthly debt payments with your gross monthly income. Lenders commonly use this measurement when evaluating applications for loans and credit. It can also help you understand your own repayment capacity.

To calculate DTI, add your required monthly debt payments. Then divide that amount by your gross monthly income and multiply by 100.

For example, suppose your monthly debt payments total $600 and your gross monthly income is $3,000. Your DTI would be 20%.

A lower ratio generally leaves more income available for housing, food, savings, emergencies, and additional debt payments. A higher ratio can make your budget less flexible.

However, DTI does not tell the entire story. It does not account for every household expense or your interest rates. Someone with a lower DTI but expensive credit card debt may still face serious repayment problems.

Use DTI alongside your budget, interest rates, emergency savings, and total balances. Together, these figures provide a more useful picture of your financial situation.

What is the quickest way to clear debt?

The quickest way to clear debt is usually to increase the amount you pay each month while reducing the interest charged on your balances. Start with a detailed budget that shows exactly where your money goes.

Cut expenses that are not essential and redirect those savings toward your debt. At the same time, look for realistic ways to increase income. Temporary freelance work, overtime, or selling unused items can create additional repayment money.

Consider whether debt consolidation or refinancing could reduce your interest costs. A lower rate can help more of each payment reach the principal. However, consolidation is not automatically cheaper. Check the interest rate, fees, repayment period, and total cost before agreeing.

You can also contact creditors to ask whether they offer lower rates or hardship programs. Results vary, so do not assume every lender will approve a reduction.

Use windfalls carefully. Tax refunds, bonuses, or other unexpected money can make a meaningful debt payment. Keep enough cash for essential emergencies, then direct the remaining amount toward your priority balance.

Debt Consolidation and Refinancing Options

Debt consolidation combines multiple debts into one account. Instead of managing several balances and payment dates, you make one payment under the new arrangement. This can simplify budgeting and may reduce interest if the new rate is lower.

Refinancing works differently depending on the type of debt. You replace an existing loan with new financing that ideally offers better terms. The goal is usually to reduce the interest rate, monthly payment, or total borrowing cost.

However, a lower monthly payment does not necessarily mean you are saving money. A longer repayment term can reduce monthly costs while increasing total interest.

Before consolidating or refinancing, compare:

  • Interest rates and annual percentage rates
  • Origination or transfer fees
  • Repayment periods
  • Early repayment penalties
  • Total interest paid
  • Whether the new payment fits your budget

Avoid using consolidation as permission to keep spending. If the original spending problem continues, new balances can appear while the consolidated debt remains.

Choose refinancing only when the overall terms genuinely improve your financial position.

How to pay $30,000 debt in one year?

Paying off $30,000 of debt in one year requires substantial cash flow. Dividing $30,000 by 12 months gives $2,500 per month before accounting for interest. Therefore, your actual monthly target may need to be higher.

Start by calculating your current income and essential expenses. The difference shows how much money is available for debt repayment. If that amount falls well below your target, you need either higher income, lower expenses, or more time.

A zero-based budget can help assign every dollar a specific purpose. Prioritize housing, food, utilities, transportation, insurance, and other essential costs first.

Then direct as much surplus as possible toward your highest-priority debt. Additional income can make a major difference. Consider freelance work, overtime, temporary weekend work, or selling valuable items you no longer need.

Break the annual target into smaller milestones. A monthly goal of $2,500 can become weekly targets that are easier to track.

Do not sacrifice essential expenses or eliminate emergency savings completely. A small financial buffer can prevent an unexpected expense from forcing you back into debt. Learn more about how to build an emergency fund while balancing risk, returns, and liquidity.

Maximizing Income Through Side Hustles

Increasing income can make a major difference when your debt repayment target is aggressive. A side hustle can provide additional cash without requiring permanent lifestyle changes. The best option depends on your skills, available time, and local opportunities.

Freelancing, tutoring, delivery work, online services, weekend shifts, and selling unused items are common options. Focus on work that produces reliable income rather than chasing unrealistic promises of quick money.

Set a specific monthly income target. For example, earning an additional $500 per month creates $6,000 in potential annual repayment money. Directing that entire amount toward debt can significantly shorten your timeline.

Keep side-hustle costs under control. Buying expensive equipment or paying large upfront fees can reduce the amount available for repayment.

Also consider taxes and other costs associated with additional income. Your gross earnings are not necessarily the amount available for debt payments.

Most importantly, treat extra income as temporary repayment fuel. Avoid increasing your lifestyle as your earnings rise. Once the debt is gone, you can redirect the same income toward emergency savings, investments, or other financial goals.

How to pay off debt faster with bad credit

Paying off debt with bad credit can be harder, but a low credit score does not prevent you from making progress. Start by identifying every account, balance, interest rate, and payment status. Separate current debts from accounts already in collections. If student debt is part of the picture, review the latest student loan guidelines for 2026 as well.

Make all required payments on time whenever possible. Payment history can affect your credit profile, while missed payments can create additional fees and financial pressure.

Avoid taking on unnecessary new credit while focusing on repayment. Multiple applications can create additional inquiries and may encourage more borrowing.

Be cautious with debt-relief companies that promise guaranteed results. Some charge substantial fees or make claims that are too good to be true. Research any organization carefully before sharing financial information or signing an agreement.

A nonprofit credit counseling agency may provide budgeting help and explain debt management options. A debt management plan can sometimes reduce interest rates or fees, depending on the creditors involved.

Do not confuse debt settlement with credit counseling. Settlement can have different financial and credit consequences.

Your immediate goal should be stability. Stop balances from growing, maintain required payments, and create a realistic repayment plan that fits your actual income.

Utilizing Credit Counseling Services

Credit counseling can help people who struggle to organize payments or create a workable debt-repayment plan. Reputable nonprofit counselors typically review your income, expenses, debts, and financial goals before suggesting options.

Some agencies offer debt management plans (DMPs). Under a DMP, you may make one payment to the counseling organization, which distributes funds to participating creditors. Depending on the program, creditors may offer reduced interest rates or waived fees.

These plans are not suitable for everyone. You should understand the fees, participating creditors, payment schedule, and total repayment cost before enrolling.

Credit counseling is also different from debt settlement. Settlement companies may negotiate to reduce what you owe, but the process can involve significant risks and potential credit consequences.

Before choosing an agency, verify its reputation and understand exactly how it gets paid. Avoid organizations that demand large upfront fees or guarantee that they can eliminate your debt.

A good counselor should help you understand your choices rather than pressure you into a specific financial product.

The goal is not simply to lower one payment. It is to create a sustainable plan that prevents the debt from growing again.

How to pay off debt fast with low income

Paying off debt on a low income requires realistic expectations and careful prioritization. You cannot cut essential expenses indefinitely, so focus first on creating enough monthly cash flow to make consistent payments.

Begin by reviewing every expense. Cancel unused subscriptions, reduce unnecessary purchases, and identify spending that provides little value. Even small monthly savings can become meaningful when maintained for several months.

Protect essential expenses first. Housing, food, utilities, transportation, insurance, and basic healthcare should remain priorities. Falling behind on necessities can create problems that are more serious than the original debt.

After covering essentials and minimum debt payments, direct available extra money toward your chosen repayment target. The debt snowball may provide motivation by eliminating smaller balances quickly. The avalanche can reduce interest costs by targeting expensive debt.

Look for ways to increase income without creating additional expenses. Overtime, freelance work, temporary jobs, or selling unused possessions may help.

If your income barely covers necessities, seek appropriate community or government assistance where available. Reducing essential costs can free money for debt repayment.

Progress may be slow. Consistency matters more than making unsustainable payments for a few months.

Prioritizing Essential Expenses First

When money is limited, essential expenses must come before aggressive debt repayment. Paying extra toward debt while falling behind on rent, utilities, food, transportation, or insurance can create a more serious financial problem.

Start by calculating the minimum amount required for basic living costs. Then make the required minimum payments on your debts to keep accounts current when possible.

After essentials and minimum payments are covered, use remaining money for additional debt repayment. If your budget has no surplus, focus first on increasing income or reducing unavoidable expenses.

A practical priority order may look like this:

  • Housing and basic utilities
  • Food and necessary household expenses
  • Transportation needed for work
  • Insurance and essential healthcare
  • Minimum debt payments
  • Small emergency savings
  • Additional debt payments

The exact order can change based on your circumstances. For example, an urgent overdue bill may require immediate attention.

Avoid using every available dollar for debt if it leaves you unable to handle a small emergency. Even a modest cash buffer can reduce the risk of borrowing again.

The objective is sustainable progress. A repayment plan only works when you can maintain it month after month without creating new financial problems.

FAQ SECTION

Can I negotiate a lower payoff amount with my creditors?

Yes, creditors are often willing to negotiate a settlement for less than you owe if you are facing severe financial hardship. They prefer recovering a portion of the funds rather than risking total default. You can attempt to negotiate a lump-sum settlement on your own or hire a professional debt settlement company to handle the discussions for you. Be aware that settlements can temporarily impact your credit score and may carry tax implications for forgiven amounts.

Does closing old credit card accounts hurt my credit score?

Closing old credit card accounts can negatively impact your credit score by shortening your credit history length and reducing your overall available credit limit. A lower total credit limit can instantly spike your credit utilization ratio if you still carry balances on other cards. It is generally wise to keep older accounts open and active with small, recurring purchases that you pay off immediately, rather than closing them after paying them off.

What is the difference between debt consolidation and debt settlement?

Debt consolidation involves taking out a new loan to pay off multiple existing balances, leaving you with a single monthly payment and ideally a lower interest rate. Debt settlement, conversely, involves negotiating with creditors to accept a fraction of your total balance as full payment, usually after stopping payments and letting accounts fall delinquent. Consolidation protects your credit score and pays creditors in full, whereas settlement can significantly damage your credit rating.

Should I use my emergency savings to pay off debt?

Using your emergency savings to clear your balances is rarely recommended unless you are facing extreme financial crisis or bankruptcy. Depleting your cash cushion leaves you completely vulnerable to unexpected expenses like medical emergencies or car repairs, which often forces people right back into borrowing. Instead, pause your contributions to savings temporarily and direct your current income toward your balances while maintaining a small starter emergency fund.

Conclusion

Taking control of your finances and learning how to pay off debt faster requires commitment, strategic planning, and consistent execution. Whether you are managing twenty thousand dollars or tackling a larger thirty thousand dollar balance within a year, the right methods make all the difference. By utilizing approaches like the debt avalanche, exploring consolidation, and maximizing your income, financial freedom is completely attainable. Once your debt is under control, starting early to build wealth before 30 can help you work toward longer-term financial goals. Stay focused on your goals, celebrate small milestones along the way, and apply these proven strategies today to secure a brighter, debt-free future.

Good Financial Habits That Build Wealth for a Secure Future

Good Financial Habits That Build Wealth for a Secure Future

Building lasting financial security often feels overwhelming, but developing good financial habits that build wealth changes everything. Small daily actions accumulate over time to create remarkable financial freedom and stability. People often wonder how to transform their bank accounts without winning the lottery or earning a massive six-figure salary. According to research from the Consumer Financial Protection Bureau, consistent budgeting and savings routines form the bedrock of long-term economic resilience. This article explores essential concepts to help you master your finances, including what is the 7 7 7 rule for money, what are some good habits for building wealth, what are the 7 pillars of wealth, what are 10 ways to build wealth, how to build wealth from nothing, and key principles of wealth building.

What Is the 7 7 7 Rule for Money?

The 7 7 7 rule for money is a popular financial framework. It is designed to help people divide their financial priorities into clear categories. However, there is no single universally accepted version of this rule. Different sources use the “7 7 7” concept in different ways. Some versions focus on savings, investing, and spending. Others use percentages or time-based goals.

Because the rule is not standardized, treat it as a planning framework rather than a strict financial formula. Your income, debt, expenses, and financial goals should determine your actual allocation.

The broader idea is useful. A structured approach can prevent lifestyle inflation from consuming every pay raise. It can also reduce impulse spending and encourage consistent saving.

The most important goal is to create a system that balances short-term financial security, long-term investing, and responsible spending. Adjust the numbers as your circumstances change.

Emergency Fund and Savings Allocation Strategy

An emergency fund is one of the most important parts of a strong financial plan. It protects you when unexpected costs interrupt your normal cash flow. Building this reserve is also easier when you understand short-term vs long-term savings goals.

Aim to build enough savings to cover several months of essential expenses. The right amount depends on your income stability, household responsibilities, and job security. Someone with irregular income may need a larger reserve than someone with highly stable earnings.

Keep emergency savings somewhere safe and accessible. A suitable savings account can help you earn some interest while keeping the money available when needed.

An emergency fund can reduce the need for high-interest debt after events such as job loss, major repairs, or unexpected bills. It also protects long-term investments from being sold at an inconvenient time.

Once your emergency reserve is established, you can direct more surplus cash toward retirement savings, investments, and other long-term goals.

What Are Some Good Habits for Building Wealth?

Building wealth depends more on consistent behavior than occasional financial decisions. The good financial habits that build wealth usually focus on spending less than you earn and investing the difference.

Start by creating a realistic budget based on your actual income and expenses. Tracking spending can reveal recurring costs that quietly reduce your savings rate. Budgeting apps for students can also make it easier to monitor spending and stay within your financial limits.

Another useful habit is paying yourself first. Set aside money for savings and investments before spending on non-essential items. Automation makes this easier because transfers happen without requiring a new decision each month.

Review your financial progress regularly. Checking your savings, debt, investments, and net worth can show whether your current habits are working.

Avoid increasing your lifestyle every time your income rises. Instead, direct part of each raise toward financial goals.

You should also prioritize high-interest debt. Credit card balances and similar debt can grow faster than many investments, so learning how to pay off debt and track your progress can help keep your wealth-building plan on course.

Over time, these habits create a repeatable financial system. The goal is not perfection. It is consistent progress over many years.

The Power of Automated Wealth Accumulation

Automation can make saving and investing easier because it removes many decisions from the process. Set up recurring transfers after payday to move money into appropriate savings or investment accounts. Personal finance apps can also help you monitor these habits and keep your financial goals organized.

For example, you might automatically fund an emergency savings account before directing additional money toward retirement or other investments. The exact allocation should reflect your financial situation.

Automation also reduces the temptation to spend money simply because it remains in your checking account. You can build your financial priorities into your monthly cash flow instead.

However, automation should not replace regular reviews. Your income, expenses, debt, and financial goals can change over time. Check your transfers periodically and adjust them when necessary.

Market volatility also should not automatically cause you to stop long-term contributions. Your investment choices should match your risk tolerance, time horizon, and financial goals.

The key advantage is consistency. When saving and investing happen automatically, wealth building becomes a routine rather than something you must remember every month.

What Are the 7 Pillars of Wealth?

The seven pillars of wealth are commonly described as the major areas that support long-term financial stability. There is no universally recognized list, so different financial educators may define the pillars differently.

A practical framework can include income, saving, investing, debt management, insurance, tax planning, and financial education. These areas work together rather than operating independently.

Increasing your income can create more money for saving and investing. Controlling expenses then helps preserve that additional income. Investing allows your capital to potentially grow over time.

Debt management is also important because expensive debt can consume cash that could otherwise support your financial goals. Managing your finances wisely can help you balance debt repayment, saving, investing, and other priorities. Insurance can help protect your assets from certain major risks.

Tax planning may improve the amount you keep from your earnings and investments, depending on your situation and local rules.

Finally, financial education helps you make better decisions as your circumstances change. Reviewing these seven areas can reveal weaknesses in your financial plan.

The goal is not to perfect every pillar immediately. Focus first on the areas that create the largest improvement in your financial stability.

Maximizing Income and Protecting Assets

Increasing your income can accelerate wealth building because it may increase the amount available for saving and investing. You can pursue higher earnings through career development, professional skills, additional responsibilities, or carefully chosen side income.

However, higher income does not automatically create wealth. Lifestyle inflation can absorb much of the additional money if spending rises at the same rate.

Asset protection is another important consideration. Insurance can help protect you against specific financial risks, such as property damage, liability, or certain health-related costs. The appropriate coverage depends on your circumstances and local regulations.

You should also avoid taking unnecessary risks with money you cannot afford to lose. A diversified financial plan can reduce dependence on a single asset or income source.

Review your insurance and financial risks periodically. Your needs may change after major events such as purchasing property, changing jobs, or taking on new responsibilities.

The broader principle is simple: increase what you earn while protecting what you already have. Both sides matter for sustainable wealth building.

What Are 10 Ways to Build Wealth?

There is no guaranteed formula for building wealth, but several strategies can support long-term financial growth. The right combination depends on your income, goals, risk tolerance, and time horizon.

Ten commonly used approaches include:

  1. Invest in diversified index funds that match your investment strategy.
  2. Consider real estate when the costs and risks make sense for your situation.
  3. Develop a side income through skills, services, or a business.
  4. Use employer retirement matches when available.
  5. Live below your means and invest part of the difference.
  6. Pay down high-interest debt before taking unnecessary investment risks.
  7. Invest in valuable skills that can increase your earning potential.
  8. Consider dividend-paying investments as part of a diversified portfolio.
  9. Create digital products or other income-producing assets when appropriate.
  10. Keep suitable cash reserves for emergencies and planned expenses.

These approaches are not equally suitable for everyone. Real estate can require substantial capital and ongoing management. Stocks can lose value, while business income can be unpredictable.

Focus on strategies you understand and can maintain for the long term.

Leveraging Real Estate and Index Funds

Real estate and broad-market index funds can provide different ways to participate in long-term asset growth. However, neither option is guaranteed to produce profits.

Broad-market index funds can provide diversification across many companies through a single investment. They can also require less active management than selecting individual stocks. Investment fees, taxes, market risk, and the specific fund still matter.

Real estate can generate rental income and may appreciate over time. However, property owners may face vacancies, maintenance costs, taxes, insurance, financing costs, and changing property values.

Using both asset classes may provide diversification, but your overall portfolio should reflect your financial goals and risk tolerance.

You should also consider liquidity. Selling a diversified fund may be easier than selling a property. Real estate usually requires more capital and active management.

Before investing, understand the risks and expected costs. Avoid assuming that either asset class will always rise.

The objective is to build a diversified portfolio that you can hold through different market conditions, rather than chasing whichever asset performed best recently.

How to Build Wealth From Nothing

Building wealth from zero requires patience and a clear sequence of priorities. If you have little savings or a negative net worth, managing your money when you don’t have any should focus first on financial stability before aggressive investing.

Start by establishing a reliable income source. Then create a basic budget that covers essential living costs. Knowing where your money goes makes it easier to identify unnecessary spending.

Next, avoid adding expensive new debt. If you already have high-interest debt, prioritize paying it down while maintaining a reasonable emergency reserve.

Your first savings goal does not need to be large. A starter emergency fund can provide some protection against unexpected expenses. Increase it gradually as your income and financial stability improve.

After addressing immediate financial risks, direct additional money toward long-term investments. At the same time, work on increasing your earning potential through education, certifications, or valuable professional skills.

Progress may feel slow at first. That does not mean the strategy is failing.

The foundation is earning more, controlling expenses, reducing costly debt, saving consistently, and investing for the long term.

Mastering the Art of Extreme Frugality

Frugality can help when you are starting with limited resources, but extreme frugality is not always sustainable. Cutting every possible expense can reduce your quality of life and make your financial plan difficult to maintain.

Instead, focus on expenses that provide limited value. Review subscriptions, frequent restaurant meals, unnecessary purchases, and expensive recurring services. Learning to avoid common saving mistakes can also help you cut costs without undermining your broader financial goals.

Housing and transportation often have a larger impact than small daily purchases. If practical, reducing these major costs can create more financial flexibility than eliminating every occasional coffee.

The money you save should have a purpose. You can use it to build an emergency fund, pay down high-interest debt, or invest for long-term goals.

Frugality also works best when combined with income growth. There is a limit to how much you can reduce expenses, but your earning potential may continue to increase.

Avoid turning saving into deprivation. The goal is to create a sustainable gap between income and expenses.

That gap gives you money to deploy toward financial priorities. Over time, consistent saving and investing can help move you from financial instability toward greater independence.

Principles of Wealth Building

The principles of wealth building are more important than any single financial trend. One of the most important is compound growth. When returns remain invested, future growth can build on previous gains.

Another principle is delayed gratification. Spending every increase in income can prevent your savings and investments from growing. Keeping part of your additional income can improve your long-term financial position.

Diversification is also important. Concentrating your money in one company, property, or investment can expose you to unnecessary risk.

Time matters as well. Long-term investing gives your portfolio more opportunity to experience market cycles and compound growth. However, investing still involves risk, and past performance does not guarantee future results.

Emotional discipline can also protect your strategy. Selling investments during market declines may turn temporary losses into permanent ones. Your decisions should reflect your financial plan rather than short-term market fear.

Finally, avoid get-rich-quick promises. Wealth generally requires time, consistent saving, sensible investing, risk management, and increasing earning power.

These principles provide a stronger foundation than chasing trends or trying to predict every market movement.

Harnessing the Magic of Compound Interest

Compound growth can become powerful when investment returns remain invested and generate potential future returns. The effect becomes more significant over longer periods.

For example, regular investing can give your contributions more time to grow. Starting earlier can also provide more years for potential compounding. However, investment returns are never guaranteed, and actual results vary.

Albert Einstein is often credited with calling compound interest the “eighth wonder of the world.” That attribution is widely repeated, but it is not reliably documented. It is better to focus on the mathematical principle rather than the quotation.

The most important lesson is consistency. You do not need a large investment portfolio to begin learning disciplined financial habits. Even modest contributions can become meaningful when maintained over many years.

Avoid focusing only on short-term returns. Market values can rise and fall, sometimes sharply.

Instead, choose investments that fit your risk tolerance, time horizon, and financial objectives. Keep contributing when your financial plan allows it.

Over time, consistent contributions and potential investment growth can work together. That combination is one of the central ideas behind long-term wealth building.

Frequently Asked Questions

How Much Money Should I Save Before I Start Investing?

One of the most important Good Financial Habits That Build Wealth is building an emergency fund before taking significant investment risks. Aim to save enough to cover three to six months of essential living expenses. This reserve can protect you from unexpected bills or income loss. Once your basic safety net is ready, Good Financial Habits That Build Wealth also include investing surplus money consistently for long-term goals.

Is Real Estate Better Than Stocks for Building Wealth?

Neither real estate nor stocks is automatically better for everyone. Your choice should depend on your capital, risk tolerance, goals, and investment timeframe. Stocks can provide diversification with relatively low starting capital and easy liquidity. Real estate can offer rental income and potential appreciation but requires more management and capital. Comparing these options carefully is among the Good Financial Habits That Build Wealth that can support better investment decisions.

How Can I Stop Impulse Spending Habits?

Controlling impulse spending starts with creating a delay between wanting something and buying it. Try using a 24- or 48-hour waiting period for non-essential purchases. Unsubscribe from promotional emails and remove saved payment details from shopping apps. You can also set a monthly limit for discretionary spending. These simple changes make Good Financial Habits That Build Wealth easier to maintain because they reduce unnecessary spending without requiring extreme restrictions.

Can I Build Wealth on a Low Salary?

Building wealth on a low salary is possible, but your income still matters. Start by controlling essential expenses, avoiding high-interest debt, and saving consistently. Automating even small monthly contributions can help you develop discipline and benefit from long-term investment growth. At the same time, focus on improving your skills and earning potential. Good Financial Habits That Build Wealth become more powerful when combined with steady income growth over time.

Conclusion

Building wealth rarely comes from one financial trick. It usually develops through consistent saving, sensible investing, debt management, controlled spending, and increasing your earning potential. The Good Financial Habits That Build Wealth discussed in this article can help create a stronger financial foundation over time. Start with one practical change, such as building an emergency fund or automating savings. Then keep improving your system as your income, goals, and circumstances change.

Side Hustle Taxes in India: Rules, Filing & Common Mistakes

Side Hustle Taxes in India: Rules, Filing & Common Mistakes

Managing side hustle taxes can feel overwhelming when you are balancing a regular job and extra freelance work. Navigating these financial obligations requires understanding how Indian tax laws treat secondary streams of income. Whether you are coding on weekends, writing content, or consulting, your extra earnings are rarely tax-free. Every taxpayer must properly report these additional revenue channels to stay compliant with the Income Tax Department. You can review official updates directly through the Income Tax Department of India portal. This comprehensive guide answers critical questions about how much tax you will pay, what mistakes to avoid, freelance tax rules, the 42% tax bracket, the 12 lakh income limit, and exact reporting methods for your side hustle taxes in india.

How much tax will I pay on a side hustle?

Your side hustle tax liability depends entirely on your total annual taxable income across all sources. The government does not tax a side hustle as a separate entity. Instead, your freelance earnings or secondary income club with your primary salary or business income. Tax rates follow the standard individual income tax slabs applicable under either the old or new tax regime. If your total combined income falls within the lowest slab, you pay minimal tax. Higher overall earnings push you into higher slab rates, reaching up to 30 percent plus applicable surcharges and cesses. Calculating your net profit correctly helps reduce your overall burden. You deduct eligible business expenses like internet bills, software subscriptions, and hardware depreciation before calculating final taxes. Strategic financial planning ensures you do not overpay on your side hustle earnings.

Calculating Net Profits for Accurate Tax Assessment

Determining your exact taxable side hustle profit involves subtracting legitimate business expenses from your gross earnings. Keeping separate bank accounts for your side business simplifies tracking operational costs. You can claim deductions for home office utility bills, professional tools, and marketing expenses incurred exclusively for generating side income. Proper record-keeping protects you during audits and prevents unnecessary tax penalties.

What are common side hustle mistakes to avoid?

Many side hustle beginners make costly errors that trigger tax notices and unwanted financial stress. Failing to separate personal and business finances remains one of the most frequent missteps. Mixing funds makes tracking deductible expenses difficult and complicates your annual tax filing process. Another major error involves neglecting quarterly advance tax payments when your total tax liability exceeds specific thresholds. Ignoring record-keeping for small business expenses also leads to inflated tax payments because you miss out on legitimate deductions. Furthermore, many earners mistakenly believe cash payments escape reporting requirements. The Indian tax system tracks high-value transactions and digital footprints closely. Staying proactive prevents these common pitfalls and keeps your financial record clean.

The Importance of Tracking Every Business Expense

Failing to document minor operational costs can significantly increase your annual tax liability over time. Every software subscription, domain registration fee, and client-meeting expense adds up to reduce your taxable profit margin. Utilizing digital accounting software ensures you never miss a deductible receipt. Consistent tracking transforms tax season from a chaotic scramble into a streamlined, stress-free administrative task.

Do I pay tax if I freelance?

Freelance income is fully taxable under Indian income tax laws, regardless of whether it serves as your primary career or a side gig. The Income Tax Department classifies freelance earnings under profits and gains from business or profession. You must report these earnings during your annual tax return filing process. Even if your clients do not deduct Tax Deducted at Source, you remain personally responsible for calculating and paying the correct tax amount. If your total gross receipts from freelancing remain below specific limits, you might explore presumptive taxation schemes. These schemes simplify compliance by allowing you to declare a fixed percentage of gross receipts as net income. Understanding your obligations ensures complete legal compliance without unnecessary financial surprises.

Understanding Presumptive Taxation for Freelancers

Presumptive taxation under Section 44ADA offers eligible professionals a simplified way to file taxes. Instead of maintaining complex detailed accounting books, you declare a flat fifty percent of your gross receipts as taxable profit. This streamlined approach saves time and reduces accounting costs for eligible small-scale service providers and independent digital freelancers.

Who pays 42% tax in India?

The peak tax rate in India can reach approximately thirty-nine to forty-two percent when including all surcharges and cesses. This maximum marginal rate applies exclusively to ultra-high-net-worth individuals earning extremely high annual incomes. Specifically, individuals with taxable incomes exceeding five crore rupees face the highest surcharge rate of twenty-five percent under the old tax regime, pushing the effective tax rate past forty percent. Regular side hustlers and middle-income earners do not fall into this bracket. Your side hustle income simply adds to your existing slab. Understanding high-end tax brackets reassures typical freelancers who worry about extreme taxation on modest secondary earnings. Progressive tax slabs ensure that tax burdens scale appropriately with actual financial capacity.

Surcharges and Cesses on Ultra-High Incomes

Understanding how surcharges function at higher income levels clarifies why top marginal rates reach elevated percentages. Surcharges act as a tax on tax, scaling upward as annual income crosses specific multi-crore thresholds. Additionally, a standard health and education cess applies to all tax amounts. These cumulative additions account for the maximum peak rates reported in tax discussions.

Is 12 lakh income tax free for self-employed?

An annual income of 12 lakh rupees is not entirely tax-free for self-employed individuals under standard slab rules. While recent budget proposals introduced attractive rebate limits and tax-free thresholds under the new tax regime, an income of 12 lakh exceeds the basic exemption limit. Under the current tax structure, tax slabs apply progressively to income earned above the basic tax-free exemption threshold. However, self-employed professionals can significantly reduce their taxable base using legitimate business deductions and expense write-offs. By deducting operational costs, equipment depreciation, and eligible allowances, you can lower your net taxable income closer to lower slabs. Strategic planning remains essential to optimize your tax liability legally.

Utilizing Deductions to Lower Taxable Income

Self-employed earners can leverage various deductions to minimize the impact of progressive tax slabs on a 12 lakh income. Contributing to public provident funds, health insurance policies, and eligible retirement schemes helps reduce taxable totals. Combining personal deductions with legitimate business expense write-offs ensures you retain more hard-earned money from your secondary ventures.

How to report side hustle income

Reporting your side hustle income accurately requires filing the correct Income Tax Return form based on your specific professional profile. Most freelancers and side hustlers use ITR-3 or ITR-4 forms to declare business or professional profits. You must summarize your total gross receipts and itemize your business expenses in the profit and loss section of the form. If you maintain regular employment, your primary salary details go into the salary schedule, while side hustle earnings integrate into the business income schedule. Ensure you reconcile your Form 26AS and Annual Information Statement before submission. These official government documents reflect all tax deducted at source and reported financial transactions linked to your PAN card.

Reconciling Form 26AS and Annual Information Statement

Reviewing your Form 26AS and Annual Information Statement before filing prevents costly discrepancies in your tax return. These documents compile all financial transactions, bank interests, and client tax deductions reported against your permanent account number. Matching your side hustle records with government data ensures seamless processing and avoids automated mismatch notices from tax authorities.

Side hustle taxes in india

Navigating side hustle taxes in india requires a clear understanding of domestic tax regulations, GST thresholds, and filing procedures. If your aggregate turnover from digital services or goods crosses specific turnover limits, mandatory Goods and Services Tax registration applies. Most small-scale side hustlers start below these turnover thresholds, exempting them from complex GST filings initially. However, keeping close tabs on your annual revenue growth prevents sudden compliance violations. Proper tax planning involves setting aside a fixed percentage of every side hustle payout into a dedicated tax savings account. This disciplined habit ensures you always have adequate funds ready when advance tax deadlines or annual filing dates arrive.

Monitoring GST Thresholds for Digital Services

Keeping track of your gross annual turnover helps determine when you must register for Goods and Services Tax. Digital service providers and goods sellers have distinct turnover limits that trigger mandatory GST registration requirements. Exceeding these limits without proper registration can attract heavy penalties, making continuous revenue monitoring an essential business practice.

Frequently Asked Questions

Do I need to pay advance tax on my side hustle earnings?

You must pay advance tax if your total tax liability exceeds ten thousand rupees in a financial year after accounting for TDS. Splitting your tax payments into quarterly installments helps avoid penal interest charges. Proactive calculation prevents large, unmanageable tax bills at the end of the financial year.

Can I deduct home office expenses for my side hustle?

You can deduct a proportionate amount of your rent, electricity, and internet bills if you use a dedicated space exclusively for your side business. Maintaining proper logs and utility bills is essential to justify these claims during tax assessments. Clear documentation ensures full compliance with standard tax regulations.

What happens if I fail to report my side hustle income?

Failing to report side hustle income can lead to severe penalties, interest charges, and scrutiny from the Income Tax Department. Tax authorities match digital transaction histories with filed returns to catch discrepancies. Voluntary disclosure and prompt rectification of past errors minimize potential legal complications and financial penalties.

Do I need a separate bank account for my side hustle?

Opening a separate bank account for your side hustle is not legally mandatory, but it is highly recommended by financial experts. A dedicated account simplifies expense tracking, separates personal spending from business revenue, and makes tax filing significantly easier. Clean financial separation protects you during audits and financial reviews.

Conclusion

Mastering side hustle taxes ensures your secondary income remains a profitable and stress-free endeavor. By understanding how your extra earnings combine with your primary salary, you can plan your finances effectively and avoid unexpected penalties. Proper record-keeping, timely advance tax payments, and accurate reporting on forms like ITR-3 or ITR-4 protect your financial standing. Navigating side hustle taxes successfully requires discipline, continuous tracking of business expenses, and adherence to Indian tax regulations. Just as maintaining accurate tax records is essential, keeping important financial and ownership documents organized is equally valuable. For example, understanding the importance of vehicle sale lien records can help you manage other financial transactions with greater confidence. Apply these insights to organize your finances today and secure your financial future.

Short-Term vs Long-Term Savings: Mastering Your Goals

Short-Term vs Long-Term Savings: Master Your Goals

Initially, setting financial targets forms the absolute cornerstone of building lasting wealth. However, many people struggle deeply to balance their immediate cash needs. Consequently, understanding the differences between short-term vs long-term savings is essential. Ultimately, your financial approach must completely change based on your specific timeline.

Specifically, the U.S. Securities and Exchange Commission (SEC) heavily emphasizes defining clear financial objectives. Furthermore, this represents the very first step toward successful investing and responsible management. Therefore, you simply cannot treat all your hard-earned money the exact same way. In fact, a standard checking account loses purchasing power due to inflation over time.

Conversely, locking all your cash in a volatile retirement account remains highly risky. Thus, it leaves you totally vulnerable to sudden, unexpected daily expenses. As a result, you absolutely need a comprehensive dual strategy that safely covers both bases. Essentially, this article explores how to clearly separate your immediate cash requirements.

Additionally, you will learn the absolute best types of accounts to actively use. Moreover, we will comprehensively cover the specific risks inherently involved in different financial strategies. By the end, you will firmly master short-term vs long-term savings effectively. Ultimately, you will know exactly how to fund your vacations without sacrificing your retirement.

What Is the Difference Between Short-Term vs Long-Term Savings?

Understanding short-term vs long-term savings helps you choose the right place for your money and achieve your financial goals. While both are important, they serve different purposes based on when you expect to use your funds. Knowing the differences between short-term vs long-term savings makes it easier to create a balanced savings strategy that supports both immediate needs and future milestones.

Short-term savings are designed for expenses you expect within the next three years. These goals often include building an emergency fund, paying for a vacation, covering car repairs, or handling unexpected medical bills. Because you may need the money at any time, it should remain in highly liquid and low-risk accounts where your principal is protected.

In contrast, long-term savings focus on goals that are several years or even decades away. These may include retirement, buying a home, or funding a child’s higher education. Since you have more time before using the money, you can accept moderate investment risk in exchange for higher growth potential. Investments such as mutual funds, equities, or other growth-oriented assets can help your savings outpace inflation and build greater wealth over time.

Understanding short-term vs long-term savings allows you to match your savings strategy to your financial timeline. Choosing the right balance between short-term vs long-term savings helps you stay prepared for unexpected expenses while steadily building wealth for the future. A well-planned approach to short-term vs long-term savings provides both financial security today and long-term financial confidence.

The Role of Liquidity in Savings Goals

Liquidity refers to how quickly you can access your money without losing value. It is one of the most important factors when choosing where to keep your savings. Short-term financial goals require high liquidity because emergencies and planned expenses can happen without much notice. Keeping these funds in an easily accessible account ensures you can withdraw money quickly without penalties or market losses.

Long-term savings have a different purpose. Since the money is not needed immediately, you can focus more on growth than instant access. This allows investments to benefit from compound returns while riding out short-term market fluctuations. Choosing the right balance between liquidity and growth helps you stay prepared for unexpected expenses without sacrificing future financial goals.

What Is the 70/20/10 Rule for Money?

The 70/20/10 rule is a simple budgeting method that helps you manage your monthly income without creating a complicated financial plan. Under this approach, you spend 70% of your income on essential living expenses, including housing, groceries, transportation, utilities, and other daily necessities. The next 20% goes toward financial priorities such as building savings, investing, paying off high-interest debt, or contributing to retirement accounts.

The remaining 10% is reserved for charitable giving, personal development, or discretionary savings. This flexible category allows you to spend intentionally without affecting your long-term financial security. The 70/20/10 rule encourages consistent saving while ensuring your essential expenses remain covered. Because it is easy to follow, it works well for beginners who want to improve budgeting habits and develop better financial discipline.

Simplifying Monthly Budgets With Percentages

Percentage-based budgeting removes much of the guesswork from managing money. Instead of assigning fixed dollar amounts, you divide your income into percentages that automatically adjust when your earnings change. This makes the system practical for people with fluctuating monthly income or variable freelance earnings.

As your income rises or falls, your spending and savings adjust naturally while maintaining the same financial priorities. This flexibility helps prevent overspending and supports consistent progress toward savings goals. Over time, percentage-based budgeting creates healthier financial habits and makes long-term money management much easier.

What Is the 70-10-10-10 Rule for Money?

The 70-10-10-10 rule expands on traditional budgeting by assigning every portion of your income a specific purpose. Under this framework, 70% of your net income covers essential living expenses such as rent, food, utilities, insurance, and transportation. The first 10% is directed toward long-term investments or retirement savings to build wealth over time.

The second 10% is allocated to short-term savings goals, including vacations, annual insurance premiums, home improvements, or planned purchases. The final 10% goes toward debt repayment or charitable donations, depending on your financial priorities. This structured approach reduces unnecessary spending and ensures every dollar supports a meaningful financial objective. It also makes budgeting easier by creating clear boundaries for spending, saving, and investing.

Structuring Savings Into Distinct Buckets

Dividing your money into separate savings buckets improves organization and financial clarity. Each category serves a specific purpose, making it easier to track progress toward both short-term and long-term goals. This method also reduces the temptation to spend money intended for future needs.

Separate savings buckets provide better visibility into your financial health and help you prioritize expenses with confidence. Whether you are saving for emergencies, retirement, or a major purchase, assigning every dollar a defined role creates stronger financial discipline and reduces uncertainty over time.

Which FD Is Better: Short-Term or Long-Term?

Choosing between a short-term fixed deposit (FD) and a long-term fixed deposit depends on your financial goals, expected cash needs, and interest rate outlook. Short-term FDs generally range from seven days to one year. They provide better liquidity and flexibility if you expect to use your money soon or believe interest rates may increase in the near future.

Long-term FDs typically have tenures ranging from two to ten years. They allow you to lock in a fixed interest rate for an extended period, which can be beneficial when interest rates are expected to decline. While long-term FDs offer predictable returns, they reduce flexibility because withdrawing funds early may result in penalties. Selecting the right tenure depends on balancing stability, returns, and access to your money.

Evaluating Interest Rates and Tenure

Interest rate trends play a major role when choosing an FD tenure. If rates are likely to rise, shorter-term deposits allow you to reinvest later at higher returns. If rates are expected to fall, locking in a long-term FD can secure favorable returns for several years.

Many investors also diversify by splitting money across multiple FD durations. This strategy improves liquidity while reducing the risk of committing all funds during an unfavorable interest rate cycle. Combining short-term and long-term FDs can provide greater flexibility and more stable overall returns.

Frequently Asked Questions

How much money should I keep in my short-term savings account?

A good target is three to six months of essential living expenses in a liquid savings account. This emergency fund helps cover unexpected events such as job loss, medical expenses, or urgent home and vehicle repairs. Keeping these funds separate from long-term investments prevents you from selling investments at unfavorable times.

Can I use long-term savings for short-term emergencies?

Using long-term savings for emergencies should be a last resort. Withdrawing investments early may interrupt compound growth and could result in taxes, penalties, or lower long-term returns. A dedicated emergency fund is a better solution because it provides immediate access to cash without affecting your future financial goals.

Is the 70/20/10 rule suitable for low-income earners?

The 70/20/10 rule may be difficult if essential expenses consume more than 70% of your income. In that situation, adjust the percentages temporarily to meet basic living costs first. As your income increases, gradually shift more money toward savings and investments until you reach your desired allocation.

Do fixed deposits beat inflation over the long term?

Fixed deposits provide capital protection and predictable returns, but they do not always outperform inflation over long periods. As inflation rises, the real value of FD returns may decline. For long-term wealth creation, many investors combine fixed deposits with growth-focused investments such as mutual funds or equities, while using FDs for stability and lower risk.

Conclusion

First, actively managing your personal finances successfully strictly requires a highly disciplined, completely split overarching approach. Specifically, you simply cannot logically treat all your hard-earned, highly valuable money the exact same way. Therefore, completely understanding short-term vs long-term savings gives you a massive, undeniable advantage in lasting wealth creation. Consequently, you actively protect yourself from sudden, immediate disasters by keeping emergency cash highly liquid.

Furthermore, simultaneously, you perfectly guarantee an immensely wealthy, deeply secure future by aggressively investing heavily over decades. Ultimately, the absolutely most crucial, totally vital step in this entire complex process remains taking immediate action. Thus, proactively open a highly competitive, entirely secure high-yield savings account this very afternoon immediately. Additionally, incredibly carefully review your employer’s standard matching program deeply and entirely optimize your contributions today.

Moreover, strict technological banking automation will incredibly quickly serve as your absolute, undeniably best friend. For instance, carefully comparing FD vs mutual fund returns perfectly illustrates how completely different accounts essentially serve fundamentally distinct timelines. Consequently, set up totally automated monthly bank transfers so your money moves instantly and completely perfectly. Finally, clearly define your targets, rigorously pick the entirely correct accounts, and consistently execute your ultimate strategy.

Student Loan Guidelines 2026: Everything You Need to Know

A Complete Guide to Student Loan Guidelines in 2026

Figuring out how to pay for college can feel overwhelming. With rising tuition costs, most families eventually need to explore borrowing options. If you are preparing for higher education, understanding the latest student loan guidelines is absolutely essential. These rules dictate everything from how much money you can borrow to how you will eventually pay it back. By familiarizing yourself with the official Federal Student Aid requirements provided by the U.S. Department of Education, you can make smarter financial decisions that protect your future.

Education debt is a serious commitment, but it does not have to be a lifelong burden. Knowing the right steps to take before you sign a promissory note gives you total control over your finances. Today, borrowing parameters frequently change. New repayment plans emerge, interest rates fluctuate, and forgiveness programs face legislative updates. Therefore, you need accurate, up-to-date information to navigate this complex landscape.

In this comprehensive article, we will explore the core rules you must know before borrowing. We will break down current borrowing limits, explain the crucial differences between federal and private lenders, and highlight the best repayment strategies available today. Whether you are an incoming freshman, a graduate student, or a parent supporting your child, this guide will provide the absolute clarity you need to succeed.

Understanding Basic Student Loan Guidelines

Before you borrow a single dollar, you must grasp the foundational rules of college financing. The government sets specific parameters to protect both the borrower and the lender. These foundational student loan guidelines determine who qualifies for aid, how interest accrues, and what responsibilities you hold after graduation.

You must complete the Free Application for Federal Student Aid (FAFSA) every year to access government funding. The information you provide dictates your financial need. Consequently, your school uses this data to build a custom financial aid package.

Federal vs. Private Education Funding

Borrowers generally choose between two main types of debt: federal and private.

  • Federal funding: The government funds these options. They offer fixed interest rates, income-driven repayment plans, and forgiveness programs. Federal loans almost never require a credit check or a cosigner.

  • Private funding: Banks, credit unions, and online lenders provide these options. They require a credit check and usually demand a cosigner. Private lenders set their own rules, which means they rarely offer flexible repayment options.

Always exhaust your federal options before turning to private lenders. Federal loans offer built-in safety nets that private lenders simply do not match.

What Is the New Student Loan Plan for 2026?

The new student loan plan for 2026 introduces streamlined income-driven repayment (IDR) options designed to reduce monthly payments for many undergraduate borrowers. Under the updated framework, the government aims to cap discretionary income at more affordable levels, helping low- and middle-income graduates manage repayment without excessive financial strain. The application process has also become simpler through integrated digital portals, reducing paperwork and administrative delays. In addition, revised interest subsidy rules help prevent qualifying borrowers from seeing their balances grow because of unpaid interest. These changes are intended to make repayment more predictable and financially sustainable. Financial experts recommend reviewing the updated repayment options before selecting a plan. Comparing your expected income, career path, and long-term financial goals can help you choose the repayment strategy that offers the greatest savings over the life of your student loan.

Impact on Monthly Discretionary Income Caps

One of the most significant changes in the 2026 student loan plan is the adjustment to monthly discretionary income caps. The updated formula lowers the percentage of discretionary income used to calculate monthly payments for many eligible borrowers. As a result, recent graduates can keep more of their income during the early stages of their careers, when salaries are often lower and living expenses can be challenging. Lower monthly payments improve cash flow and make it easier to cover essentials such as housing, transportation, and savings. These changes also reduce the likelihood of missed payments caused by financial pressure. Borrowers should review their income annually and update their repayment information when required. Staying enrolled in the appropriate income-driven repayment plan ensures they continue receiving the maximum benefit while keeping their student loan payments affordable over time.

What Is the Minimum Student Loan for 2026–2027?

The minimum student loan amount for the 2026–2027 academic year depends primarily on your school’s Cost of Attendance (COA), federal borrowing limits, and lender requirements. Federal Direct Loans generally do not impose a nationwide minimum borrowing amount. However, colleges and private lenders may require students to borrow a minimum amount, often around $1,000, before approving a loan. This flexibility allows students to borrow only what they truly need for tuition, mandatory fees, books, and essential living expenses. Borrowing responsibly helps reduce future repayment costs and minimizes unnecessary interest charges. Before accepting a loan offer, calculate your education expenses carefully and explore scholarships, grants, and savings first. Your school’s financial aid office can explain any institution-specific borrowing requirements and help you determine the most appropriate loan amount.

Navigating Private Lender Minimums Successfully

Private lenders often establish minimum loan amounts to offset administrative and processing costs. These requirements vary by lender, making it important to compare multiple loan providers before applying. Some lenders may require higher minimum borrowing amounts than others, while eligibility criteria can also differ based on credit history or a co-signer. Planning your semester budget in advance helps you borrow only what you need while still meeting lender requirements. Avoid taking extra funds simply because they are available. Every additional dollar borrowed may increase the total interest paid over the life of the loan. Comparing interest rates, repayment terms, fees, and borrower benefits can help you select the most cost-effective financing option while keeping future debt manageable.

What Are the New Guidelines for Student Loans?

The new student loan guidelines for 2026 focus on greater transparency, stronger borrower protections, and increased accountability across federal and private lending programs. Lenders must provide clearer disclosures showing the estimated total repayment cost before borrowers sign loan agreements. Updated policies also strengthen default prevention by requiring loan servicers to offer counseling and alternative repayment solutions before accounts enter serious delinquency. These measures help students make informed financial decisions while reducing the risk of unexpected repayment challenges. Educational institutions are also expected to provide more comprehensive financial literacy resources before students accept federal or private loans. Together, these improvements encourage responsible borrowing and help students better understand their financial obligations throughout the borrowing and repayment process.

Enhanced Consumer Protection and Fee Transparency

Recent policy updates place a stronger emphasis on consumer protection and transparent loan terms. Borrowers now receive clearer explanations of interest calculations, repayment schedules, and any applicable fees before accepting a loan. Many updated regulations also reduce or eliminate hidden charges that previously increased borrowing costs unexpectedly. Simple, easy-to-understand loan documentation allows students to make informed decisions without navigating complex financial language. Better transparency also helps borrowers understand when interest begins accruing, how repayment options work, and what happens if payments are missed. These protections support more responsible borrowing and reduce the likelihood of unpleasant financial surprises. Reading all loan documents carefully remains essential, even with stronger disclosure requirements.

What Is the Education Loan in 2026?

An education loan in 2026 reflects a more modern approach to financing higher education. Today’s loan products are designed to match rising tuition costs while offering greater convenience through digital banking technology. Many lenders now provide flexible disbursement schedules that align with semester or quarterly billing cycles, ensuring students receive funds when they are needed most. Borrowers can also manage their accounts through secure online dashboards that allow them to monitor balances, submit documents, request deferments, and review repayment progress. Education loans now support a wider range of academic pathways, including university degrees, vocational programs, technical certifications, and online learning. These innovations make student financing more accessible and improve the overall borrowing experience for students pursuing traditional and non-traditional educational opportunities.

Digital Integration and Smart Repayment Tracking

Modern student loan platforms include advanced digital tools that simplify account management throughout the repayment journey. Mobile apps and online dashboards allow borrowers to monitor balances, receive payment reminders, download statements, and update personal information from anywhere. Many lenders also encourage automatic payments by offering small interest rate discounts to eligible borrowers. Automated billing helps reduce missed payments while supporting consistent repayment habits. Digital account management also makes it easier to request deferment, review repayment history, or switch eligible repayment plans when financial circumstances change. These technology-driven features improve convenience, increase payment accuracy, and encourage long-term financial responsibility, making student loan management significantly easier than in previous years.

How much student loan can I get in 2026?

Determining your borrowing capacity depends on several vital factors governed by lenders and institutional policies. Under current guidelines, the exact amount you can secure varies based on your chosen course, university reputation, and total cost of attendance. Undergraduate students typically face different borrowing limits compared to graduate or professional degree seekers. Private lenders and financial institutions evaluate your credit history, co-signer strength, and future earning potential before approving large sums. Furthermore, universities calculate your financial need by subtracting your expected family contribution from the total cost. This ensures that you only borrow what is necessary to cover tuition, housing, and essential study materials. Proper budget planning keeps your post-graduation debt manageable and prevents unnecessary financial strain.

Assessing Your Total Cost of Attendance

Lenders carefully evaluate the complete cost of attendance provided by your academic institution. This calculation encompasses tuition fees, accommodation, textbooks, transportation, and daily living expenses. Providing accurate estimates ensures your approved loan amount closely matches your actual financial requirements during the academic year.

Can I get a 100% student loan?

Securing full coverage for your academic expenses is a common goal for many aspiring scholars worldwide. While 100 percent financing is possible, it largely depends on the lender, your academic profile, and collateral availability. Public lenders often impose caps that cover a significant portion of tuition, leaving students to arrange margin money for living costs. However, specialized financial institutions and premium banks sometimes offer complete coverage for top-tier universities or high-demand professional programs. Achieving full funding usually requires a strong co-signer with an excellent credit score or valuable tangible collateral like property. Students must carefully weigh the long-term interest implications of borrowing the entire cost upfront before committing to a massive debt burden.

Role of Collateral in Full Financing

Providing secure collateral significantly increases your chances of obtaining complete educational funding from traditional lenders. Real estate, fixed deposits, or government bonds act as strong security guarantees for banks. This security minimizes lender risk, allowing them to disburse the entire cost of your education smoothly.

Education loan by Government

Government-backed financial assistance remains one of the most reliable and affordable ways to fund higher studies. These programs are designed to support deserving students by offering lower interest rates and flexible moratorium periods. Most government schemes do not require immediate repayment while you are studying, giving you peace of mind. Additionally, many nationalized initiatives waive processing fees and provide special subsidies for economically weaker sections or female students. Applicants must complete thorough verification processes and submit academic admission proofs to qualify for these beneficial public funds. Checking official state or federal education portals ensures you never miss crucial deadlines for application submissions.

Benefits of Moratorium Periods

Government loans typically feature a helpful moratorium period that lasts throughout your course duration plus a grace period. During this window, you are not obligated to make principal or interest repayments. This crucial breather allows you to focus entirely on your academics without immediate financial pressure.

Education loan debt calculator

Managing your future finances effectively requires a clear understanding of your monthly repayment obligations before signing any agreement. An education loan EMI calculator is a digital tool that instantly computes your Equated Monthly Installments based on specific variables. By inputting your desired loan amount, applicable interest rate, and repayment tenure, you instantly see your monthly breakdown. This transparency helps you choose a tenure that aligns with your projected post-graduation salary expectations. Experimenting with different numbers allows you to find a comfortable balance between affordable monthly payments and total interest outgo. Utilizing this tool prevents unpleasant surprises and builds financial discipline long before your repayment phase officially begins.

Impact of Tenure on Total Interest

Choosing a longer repayment tenure reduces your monthly EMI amount, making payments feel manageable right after graduation. However, extending the timeline significantly increases the total cumulative interest paid over the life of the loan. Shorter tenures save money overall but demand higher monthly installments from your starting salary.


Frequently Asked Questions

How do I apply for the updated federal student loan programs?

Applying for updated federal student loan programs begins with completing the Free Application for Federal Student Aid (FAFSA) through the official government website. Review the latest student loan guidelines before submitting your application so you understand the current eligibility requirements and repayment options. Submit your FAFSA as early as possible to meet your school’s priority deadlines and maximize your financial aid eligibility. After processing, your college or university will provide a financial aid offer outlining available grants, scholarships, work-study opportunities, and federal student loans. Carefully review the award letter before accepting any loan. Compare repayment plans, estimated monthly payments, and long-term borrowing costs. If you have questions, contact your institution’s financial aid office for guidance before finalizing your borrowing decisions.

Can I refinance my existing loans under the 2026 guidelines?

Refinancing existing student loans remains an option in 2026, but borrowers should evaluate the benefits and potential drawbacks carefully. The latest student loan guidelines continue to encourage borrowers to compare all available options before refinancing federal loans with a private lender. While refinancing may reduce your interest rate if you have strong credit and stable income, it often means giving up federal benefits such as income-driven repayment, deferment, and certain loan forgiveness programs. Compare offers from multiple lenders, including interest rates, repayment terms, fees, and borrower protections. Calculate your long-term savings instead of focusing only on a lower monthly payment. A careful comparison helps determine whether refinancing supports your financial goals.

What happens if I miss a student loan payment under the new rules?

Missing a student loan payment does not automatically place your loan in default. Under the updated student loan guidelines, your loan servicer typically sends reminders and contacts you to discuss available assistance before the situation becomes more serious. Depending on your eligibility, you may qualify for forbearance, deferment, or an alternative income-driven repayment plan. Responding quickly to your loan servicer is essential because early communication often prevents additional fees and protects your credit history. Ignoring missed payments can eventually lead to delinquency and more severe financial consequences. Staying proactive and seeking assistance at the first sign of financial hardship gives you the best opportunity to keep your student loans in good standing.

Are graduate students eligible for the new 2026 repayment structures?

Graduate and professional students may qualify for portions of the updated 2026 repayment framework, although eligibility rules differ from those for undergraduate borrowers. The latest student loan guidelines outline separate borrowing limits, repayment options, and eligibility requirements for many graduate-level federal loan programs. Many graduate students rely on specialized borrowing options, such as Grad PLUS Loans, which have unique repayment terms. Before borrowing, review available repayment plans, projected monthly payments, and long-term borrowing costs. Graduate students with higher loan balances may benefit from selecting an income-driven repayment strategy that matches their expected earnings. Consulting financial aid professionals or trusted financial advisors can help determine the most suitable repayment approach.


Conclusion

Managing your education debt successfully comes down to preparation, organization, and knowledge. The world of college financing often seems complicated, but you can master it by paying close attention to the rules. Understanding the specific student loan guidelines that govern your borrowing gives you a significant advantage. You will know exactly how much you can safely borrow, how to secure the lowest interest rates, and which repayment plans fit your future budget.

Always remember to prioritize federal funding over private options. Federal programs offer unmatched flexibility, including income-driven repayment and powerful forgiveness options like PSLF. Keep your loan servicer informed of any changes to your address or income. If you ever face financial hardship, contact them immediately instead of ignoring your payments. They provide deferment and forbearance options designed to help you avoid default.

If you’re also exploring ways to reduce your overall education costs, consider applying for financial aid programs alongside student loans. You can discover several funding opportunities in our guide on Top Scholarships for Indian Students, which can help minimize borrowing and lower your long-term debt burden.

Ultimately, your education is a valuable investment in your future earning potential. Treat your debt responsibly, review your loan documents carefully, and stay informed about policy changes. By applying the strategies outlined in this guide while taking advantage of scholarship opportunities, you can confidently manage your finances and pay off your student loans faster.

Common Saving Mistakes to Avoid for Financial Freedom

Common Saving Mistakes to Avoid: 7 Pitfalls to Financial Freedom

Building a robust financial foundation is essential for a stress-free life, yet many people struggle to grow their wealth effectively because they do not know which common saving mistakes to avoid. Even if you earn a substantial income, poor money management habits can severely limit your long-term economic security. Understanding the nuances of personal finance helps you protect your hard-earned cash from inflation and unexpected expenses.

If you want to achieve true independence, you must learn which common saving mistakes to avoid at all costs. According to the Consumer Financial Protection Bureau (CFPB), establishing a dedicated, consistent savings habit is a critical component of lifelong economic well-being and stability. However, simply placing cash in a standard bank account is no longer enough to build real wealth.

You need a comprehensive, proactive strategy that maximizes your returns and minimizes unnecessary losses. Without a definitive plan, you risk falling behind your retirement targets and struggling during unforeseen emergencies. By recognizing these widespread financial errors, you can immediately shift your approach, optimize your budgeting techniques, and put your money to work for your future. Let us explore the fundamental rules of effective wealth generation.

What Are the Biggest Savings Mistakes?

Many people struggle to save money because they start without a clear financial goal. Saving becomes much easier when you know exactly what you are working toward, whether it is an emergency fund, a home down payment, or retirement. Without a specific target, it is tempting to dip into your savings for impulse purchases or lifestyle upgrades that provide only short-term satisfaction.

Another common mistake is keeping all your emergency savings in a low-interest checking account. Over time, inflation reduces your money’s purchasing power, meaning your savings lose value even if the balance stays the same. A high-yield savings account is often a better choice because it provides easy access while earning more interest.

Many people also overlook their monthly spending habits. Small subscription fees, daily coffee purchases, and forgotten recurring charges can quietly consume hundreds of dollars each year. Reviewing your expenses regularly helps you identify unnecessary costs before they become long-term financial drains.

Avoiding these common savings mistakes creates a stronger financial foundation. Setting measurable goals, choosing the right savings account, and tracking your spending consistently will help you build a reliable financial safety net for unexpected expenses and long-term financial success.

Failing to Automate Your Monthly Savings Transfers

One of the easiest ways to build savings is through automation. Scheduling an automatic transfer on payday ensures you save before you have the opportunity to spend. This simple strategy removes emotion from the process and keeps your financial goals on track.

Automatic savings also create consistency. Even small monthly contributions add up over time through regular deposits and compound growth. Because the transfers happen automatically, you rely less on motivation or willpower.

Treat your savings transfer like any other recurring bill. Prioritizing your future first makes it easier to build wealth steadily while reducing the temptation to spend money on unnecessary purchases.


What Is the 7 7 7 Rule for Money?

The 7 7 7 rule for money is a simple decision-making strategy that encourages thoughtful spending instead of impulse buying. Although different versions exist, the most common approach asks you to consider how a purchase will affect your finances over seven days, seven months, and seven years. Looking at expenses through multiple time horizons helps separate temporary wants from meaningful long-term needs.

This pause gives you time to evaluate whether a purchase truly adds value to your life or simply satisfies a short-lived desire. Many impulse purchases lose their appeal after a few days, making it easier to avoid unnecessary spending.

The money you choose not to spend can instead support more important financial goals. Redirecting those funds toward an emergency fund, retirement savings, debt repayment, or a high-yield savings account strengthens your long-term financial position. Consistently applying the 7 7 7 rule encourages mindful spending habits that improve both financial discipline and overall savings.

Applying the Time Horizon Strategy to Major Purchases

Before making a major purchase, pause and evaluate its value across different timeframes. Ask yourself whether the item will still matter in seven days, seven months, or seven years. If the answer is no, reconsider the purchase.

This simple habit reduces buyer’s remorse and prevents emotional spending. Instead of buying something with little lasting value, transfer that money directly into your savings account or investment fund.

Using a time horizon strategy consistently helps you make smarter financial decisions while keeping your long-term goals on track.


How to Avoid Common Financial Mistakes

Avoiding common financial mistakes starts with creating a realistic monthly budget and tracking every expense. Knowing exactly where your money goes helps you identify unnecessary spending before it becomes a habit. Even small recurring purchases can have a significant impact on your long-term financial health.

Another effective strategy is to automate your savings. Set up automatic transfers that move money into a separate savings account as soon as you receive your paycheck. Paying yourself first reduces the temptation to spend money on impulse purchases and helps you build wealth consistently.

Finally, establish an emergency fund that covers three to six months of living expenses. This financial cushion helps you handle unexpected events, such as medical bills or job loss, without relying on high-interest credit cards or personal loans. Developing these habits creates a stronger financial foundation and supports long-term financial stability.

Automating Your Savings for Long-Term Success

Automating your savings is one of the simplest ways to improve your financial future. Instead of relying on willpower each month, let technology handle the process automatically. Scheduling transfers on payday ensures saving becomes a regular habit rather than an occasional decision.

Direct deposits into a dedicated savings account help you live comfortably on the income that remains. Over time, this approach reduces overspending and limits the effects of lifestyle inflation. As your income grows, you can increase your automatic contributions without changing your daily routine.

Automation also keeps your financial goals moving forward during busy periods. Whether you’re saving for a home, vacation, education, or retirement, consistent contributions create steady progress. Even modest deposits can grow significantly over time through discipline and consistency.


What Are the Five Biggest Financial Mistakes?

Many people struggle financially because they repeat the same avoidable mistakes. Recognizing these habits early allows you to make better decisions and improve your long-term financial health.

The five biggest financial mistakes include:

  • Not following a monthly budget
  • Failing to build an emergency fund
  • Carrying high-interest credit card debt
  • Allowing lifestyle inflation to consume income increases
  • Delaying retirement planning and investing

Each of these mistakes can reduce your ability to save and build wealth. Poor budgeting limits financial awareness, while credit card debt adds expensive interest charges. Ignoring retirement planning also means losing valuable years of compound growth. Addressing these issues early improves cash flow, strengthens financial security, and makes it easier to reach future financial goals.

The Hidden Danger of Lifestyle Inflation

Lifestyle inflation happens when your spending rises every time your income increases. Instead of saving or investing extra earnings, you gradually spend more on housing, vehicles, dining, entertainment, or luxury purchases.

While occasional upgrades are reasonable, constantly matching spending to income leaves little room for saving. Many people earn more over time but still struggle financially because their expenses grow at the same pace.

A practical solution is to direct part of every raise into savings or investments before adjusting your lifestyle. This strategy lets you enjoy higher earnings while steadily building long-term wealth. Small decisions made consistently often produce better financial results than dramatic changes.


What Should You Avoid When Saving Money?

Understanding the common saving mistakes to avoid is just as important as developing good financial habits. Saving money is about more than setting cash aside. It also requires avoiding decisions that can slow your financial progress over time. One of the most common saving mistakes to avoid is keeping all your money in a standard checking account that earns little or no interest. As inflation rises, your purchasing power gradually declines.

Another of the common saving mistakes to avoid is withdrawing money from your savings for non-essential purchases such as luxury items, entertainment, or spontaneous vacations. Treat your savings as money reserved for genuine emergencies or carefully planned financial goals. Staying disciplined helps your savings grow consistently.

Finally, one of the most costly common saving mistakes to avoid is chasing unrealistic investment opportunities that promise guaranteed high returns. These schemes often carry significant risk and can lead to major financial losses. By recognizing these common saving mistakes to avoid and practicing consistent saving, careful investing, and patience, you can build stronger long-term financial security.

Choosing the Right Accounts for Growth

Selecting the right savings account helps your money work harder without increasing risk. High-yield savings accounts generally offer much better interest rates than traditional checking accounts, making them a suitable place for emergency funds and short-term savings.

Although inflation still affects purchasing power, earning competitive interest helps reduce its impact. Compare interest rates, account fees, withdrawal limits, and accessibility before opening an account. Choosing the right financial institution can improve your overall savings strategy.

For longer-term goals, consider combining a high-yield savings account with diversified investment options that match your risk tolerance and financial objectives. Using the right mix of accounts allows your savings to remain accessible while supporting steady financial growth over time.


What Are 7 Ways to Save Money?

Saving money does not require a high income. It requires consistent habits and smart financial decisions. Small changes made regularly can have a significant impact over time. By reducing unnecessary spending and prioritizing savings, you can steadily build financial security without feeling deprived.

Here are seven practical ways to save money:

  • Review recurring subscriptions and cancel services you rarely use.
  • Plan meals and shop with a grocery list to reduce food waste and restaurant spending.
  • Use the 24-hour rule before making non-essential purchases to prevent impulse buying.
  • Negotiate recurring bills, including insurance, internet, and utility services, each year.
  • Reduce energy consumption by turning off unused electronics and using energy-efficient appliances.
  • Deposit unexpected income, such as tax refunds or work bonuses, directly into savings.
  • Handle simple DIY home and vehicle maintenance when it is safe and practical instead of paying for minor repairs.

These strategies become even more effective when practiced consistently. Over time, small savings accumulate into meaningful financial progress and help you achieve both short-term and long-term financial goals.

Implementing Automated Budgeting and Expense Tracking Tools

Budgeting apps make managing your money easier by automatically tracking income and expenses. They categorize purchases, identify spending patterns, and highlight areas where you can save more.

Regularly reviewing your financial data helps you catch unnecessary expenses before they become recurring habits. Many apps also allow you to set savings goals and monitor your progress in real time.

Combining automated budgeting with automatic savings transfers creates a simple system that supports consistent financial growth while reducing the effort required to manage your money.


Frequently Asked Questions

What is the ideal amount to keep in an emergency fund?

Most financial experts recommend saving three to six months of essential living expenses. This emergency fund provides financial protection during job loss, medical emergencies, or unexpected home and vehicle repairs.

Keep these funds in a high-yield savings account where the money remains accessible while earning competitive interest. Review your emergency fund regularly and adjust it as your monthly expenses change.

How can I stop spending money impulsively?

Reducing impulse spending starts by creating small barriers before making purchases. Remove saved payment information from shopping websites, avoid one-click checkout, and follow a mandatory waiting period before buying non-essential items.

Shopping with a list and setting spending limits also helps reduce unnecessary purchases. If emotional spending is a challenge, find healthier alternatives for managing stress, such as exercise, reading, or spending time with friends.

Is it better to save money or pay off debt first?

For most people, the best approach is to build a small emergency fund first, then focus on paying off high-interest debt, especially credit card balances. This strategy protects you from unexpected expenses while reducing costly interest payments.

After eliminating expensive debt, increase your emergency savings to cover three to six months of living expenses. The right balance depends on your interest rates, financial goals, and overall financial situation.

How often should I review my monthly budget?

Review your budget at least once each month. Monthly check-ins allow you to compare your actual spending with your planned budget, identify unnecessary expenses, and adjust savings goals as needed.

Regular reviews also help you catch subscription price increases, monitor progress toward financial goals, and maintain healthy financial habits. Consistent budgeting is one of the most effective ways to achieve long-term financial stability.


Conclusion: Avoiding Common Saving Mistakes to Avoid for Good

Securing your ultimate financial future is a completely attainable goal that remains entirely within your personal, day-to-day control. Building massive, lasting wealth absolutely does not require a highly lucrative executive salary or a sudden, incredibly lucky lottery win. Instead, it relies heavily on unwavering consistency, intense daily discipline, and knowing exactly which common saving mistakes to avoid. By properly identifying and proactively correcting these extremely frequent money mistakes to avoid today, you immediately set yourself up for lifelong economic success.

We comprehensively explored exactly why establishing a robust, fully funded emergency reserve actively protects you from life’s unexpected, expensive turns. We also deeply discussed the absolute vital importance of setting clear, highly actionable monetary goals to keep your daily motivation consistently elevated. You must always remember to heavily leverage the significantly better interest rates of modern online high-yield banking accounts. Furthermore, you must never allow toxic, high-interest consumer debt to silently destroy your hard-earned financial progress over the coming decades.

Most importantly, you must confidently start right now, regardless of how incredibly small your initial monthly financial contributions might currently seem. Time and the mathematical magic of compound interest are unequivocally your absolute greatest allies in this lifelong wealth-building journey. Take highly intentional, immediate action today by deeply reviewing your current digital bank statements and your household monthly budget. Automate your financial systems comprehensively so you never have to actively think about transferring your money ever again.

Best Budgeting Apps for Students: Track & Save Money

Best Budgeting Apps for Students: Ultimate Guide to Managing College Finances

Finding the best budgeting apps for students is essential for managing money during college. Managing money during college can feel overwhelming. Balancing tuition, textbooks, rent, and social activities on a tight income is difficult. According to financial literacy guidelines from the Consumer Financial Protection Bureau, building early money management habits sets the foundation for lifelong economic stability. However, traditional spreadsheets and manual notebook tracking often fall short for busy students who are constantly on the move. Fortunately, modern financial technology offers a smarter solution. Choosing the right digital tools can transform how you handle cash, eliminate overspending, and reduce financial stress. This article explores top-rated tools, key features to look for, and actionable strategies to help you pick the right mobile tool for your unique lifestyle.

What is the best budgeting app for students?

Choosing the ideal financial tool depends heavily on your specific spending habits and comfort level with technology. PocketGuard often emerges as a top recommendation because it calculates your precise spendable cash after accounting for bills.

As a result, this eliminates guesswork by showing a single, clear number on your screen every single day. Students frequently struggle with accidental overspending on non-essentials like dining out or streaming services. By linking directly to bank accounts, this tool automatically categorizes transactions and flags recurring subscription charges. Thus, you gain instant clarity without needing a degree in finance or spending hours updating spreadsheets manually. Financial experts recommend selecting tools that reduce friction rather than adding complex hurdles to your daily routine. Ultimately, the right platform keeps your financial goals front and center while fitting seamlessly into a busy academic schedule, meaning you can easily find the best budgeting apps for students for your daily needs.

Understanding Automated Bank Syncing Features

Automated bank syncing takes the manual labor out of tracking daily purchases by pulling transaction data directly into your phone. Therefore, this feature ensures you never miss a hidden fee or an unexpected subscription renewal. However, you must always prioritize security by using platforms with robust, bank-level encryption.

What are the top 5 budgeting apps?

Navigating the crowded digital marketplace can feel overwhelming when you need reliable financial software. The top five choices dominating the market include PocketGuard, You Need a Budget (YNAB), Goodbudget, Spendee, and Fudget. Each platform offers a unique philosophy tailored to different user preferences. PocketGuard excels at preventing overspending, while YNAB uses a zero-based approach where every dollar gets assigned a specific job. Goodbudget revives the classic envelope method digitally, making it ideal for sharing expenses with roommates. Spendee provides gorgeous visual analytics and multi-wallet tracking, and Fudget offers minimalist lists for absolute simplicity. Reviewing these distinct options helps you match your personal workflow to the software that keeps your college bank account secure, which ultimately highlights why these platforms rank among the best budgeting apps for students today.

Comparing Automated Tracking Versus Manual Entry

Deciding between automated bank syncing and manual entry depends on your desire for active engagement. Automated apps save time by recording every swipe instantly. Conversely, manual apps require you to type in purchases, which builds psychological awareness and mindfulness around every single dollar spent.

How do I budget as a student?

Building a reliable financial plan starts with mapping out your exact monthly income sources. This baseline includes financial aid disbursements, campus job earnings, parental support, and occasional freelance money. Next, subtract your fixed monthly expenses like rent, utilities, insurance, and mandatory textbook fees. Whatever money remains becomes your flexible spending pool for groceries, entertainment, and personal items. Sticking to this structure requires regular check-ins using your chosen app to monitor category limits. Consistency matters far more than perfection during your college years. Therefore, you should adjust your allocations slightly each month as your academic schedule or work hours shift to keep your financial foundation stable and secure while using the best budgeting apps for students.

Setting Realistic Spending Limits by Category

Breaking your flexible income into distinct categories prevents accidental overspending in high-risk areas like dining out. Experts recommend allocating conservative limits for non-essentials so you always protect enough funds for absolute necessities like nutritious food and transport.

What is the best budget friendly app?

The best budget friendly app depends on your personal financial style, but options like YNAB and PocketGuard stand out for college users. These platforms sync securely with your bank accounts to automatically categorize daily coffee runs, textbook purchases, and grocery bills. They provide clear visual charts that show exactly where your money goes each month without requiring advanced accounting skills. Furthermore, many of these tools offer specialized student discounts or extended trial periods, making them much easier to afford on a tight income. Choosing the right software transforms confusing bank statements into clear, actionable spending insights instantly.

Automated Expense Tracking for Busy College Students

Automated syncing saves precious time for students juggling heavy course loads and part-time jobs. Instead of logging every single receipt manually, the software categorizes transactions in real time as you swipe your card. This seamless automation ensures your budget remains accurate without demanding hours of tedious weekly data entry.

Which budgeting app is truly free?

When searching for a platform that will not drain your pockets, apps like EveryDollar and Mint alternatives offer robust zero-cost tiers. EveryDollar provides a free version built around zero-based budgeting principles, allowing you to assign every dollar of income manually. While premium features like automatic bank syncing usually require paid subscriptions, the manual entry tier costs nothing and teaches disciplined tracking habits. Other open-source tools and spreadsheet-based apps also provide completely free experiences without hidden upgrade walls. These zero-cost solutions give students full control over their finances without adding another monthly subscription fee to their budget.

Leveraging Zero-Based Budgeting Without Paying Extra

Zero-based budgeting ensures your income minus your expenses equals zero before the month even begins. Using a free tier to assign every dollar manually forces you to become deeply mindful of your spending choices. This active engagement builds lifelong financial discipline without costing a single cent in software fees.


Frequently Asked Questions

Can I budget effectively without linking my bank account?

Yes, you can manage your finances manually using envelope systems or simple list-based apps. Manual entry forces you to confront every purchase directly, which often builds stronger psychological spending habits and improves financial mindfulness over time.

Do budgeting apps work with student loans and financial aid?

Many comprehensive finance apps allow you to add loan accounts to track your net worth and monitor total debt. This visibility helps you understand your long-term financial picture long before graduation day arrives.

Are financial apps safe to connect with my bank?

Reputable financial applications use advanced, read-only bank-level encryption to protect your sensitive login data. They never store your actual banking credentials, ensuring your money remains secure against external digital threats.

How often should I check my student budget app?

Checking your app for a few minutes two or three times a week keeps your spending goals fresh in your mind. Frequent check-ins prevent unpleasant surprises at the end of the month when bills come due.


Conclusion

Mastering your finances during college is one of the best investments you can make for your future. Using the best budgeting apps for students helps you track expenses, control spending, and build healthy financial habits. Whether you prefer automatic bank syncing or manual expense tracking, managing your money consistently can reduce stress and improve financial confidence.

Budgeting is only one part of a successful college experience. For more practical advice on academics, finances, and campus life, explore our college survival guide for freshers. It offers valuable tips to help you adjust to college and make smarter decisions from day one.

Start by choosing a budgeting app that matches your needs and commit to reviewing your finances each week. Small, consistent actions today can lead to greater financial independence and long-term success after graduation.

SIP vs FD Calculator: Which Helps You Plan Better?

SIP vs FD Calculator: Which Helps You Plan Better?

Choosing the right investment tool shapes your financial future. Consequently, you must compare a SIP vs FD Calculator early on. This comparison helps you see which tool provides clearer insights. Mutual funds and bank deposits serve very distinct financial goals. Therefore, calculating potential returns accurately is essential before investing. Furthermore, you must protect your hard-earned capital. The Securities and Exchange Board of India (SEBI) provides guidelines for this purpose.

Understanding risk-return profiles helps retail investors make smart decisions. Both online tools simplify your daily financial planning. However, they rely on entirely different formulas and market assumptions. Equity market movements affect mutual funds in unique ways. In contrast, fixed bank interest rates work completely differently. Understanding these underlying mechanics prevents costly planning errors. As a result, it ensures your expectations match actual real-world outcomes. This guide breaks down how both options work. Ultimately, we will help you choose the right financial calculator today.

Which Is More Profitable, SIP or FD?

Choosing between a Systematic Investment Plan (SIP) and a Fixed Deposit (FD) depends on your financial goals, investment horizon, and risk tolerance. Fixed Deposits offer guaranteed returns backed by banks, making them a preferred option for conservative investors who prioritize safety over growth. However, FD returns often struggle to outperform inflation over long periods, which can reduce your purchasing power.

In contrast, SIPs invest in mutual funds that are linked to the financial markets. Although they carry market risk, they have historically delivered higher long-term returns through the power of compounding. Market fluctuations may affect short-term performance, but disciplined investing over several years has often rewarded patient investors.

If your goal is capital preservation, an FD is generally the safer choice. However, if you aim to build long-term wealth and can tolerate short-term volatility, an equity SIP is usually the more profitable investment option.

Understanding Long-Term Wealth Creation Potential

Long-term wealth creation relies on two powerful factors: compounding and consistent investing. SIPs help investors benefit from both by investing a fixed amount regularly, regardless of market conditions. This approach also uses rupee cost averaging, which reduces the impact of market volatility by purchasing more units when prices are low and fewer when prices are high.

Fixed Deposits, on the other hand, provide predictable returns and protect your principal. While this stability is attractive, the returns are generally lower than those of equity investments over longer periods. As inflation rises, the real value of FD earnings may gradually decline.

For long-term goals such as retirement, children’s education, or wealth creation, equity mutual funds have historically delivered stronger inflation-adjusted returns. Fixed Deposits remain useful for preserving capital and meeting short-term financial needs, but they are less effective for aggressive wealth growth.

What Is the 7 5 3 1 Rule in SIP?

The 7 5 3 1 rule is a simple planning framework that helps investors align their investments with different financial goals and time horizons. It is not an official rule issued by regulators or mutual fund companies. Instead, it serves as a practical guideline that encourages disciplined financial planning and smarter asset allocation.

The concept reminds investors that different goals require different investment strategies. Short-term objectives should focus on capital protection, while long-term goals can benefit from market-linked investments with higher growth potential. This structured approach also helps reduce emotional investment decisions during market volatility.

Rather than chasing short-term market movements, investors following this framework stay focused on their financial milestones. As a result, they can maintain discipline, improve portfolio balance, and maximize the long-term benefits of consistent investing.

Breaking Down the Milestone Timelines

The framework recommends matching investments with specific time horizons instead of using the same investment for every financial goal. This approach allows investors to manage risk more effectively while improving the chances of achieving their objectives.

Typically, the strategy includes:

  • Short-term goals: Use safer options like Fixed Deposits or liquid funds.
  • Medium-term goals: Consider balanced or hybrid mutual funds.
  • Long-term goals: Invest primarily in equity mutual funds through SIPs.

Following this structured allocation reduces the likelihood of withdrawing long-term investments too early. It also allows compounding to work effectively while helping investors remain calm during temporary market declines.

Is a Single SIP of ₹10,000 Better Than Two SIPs of ₹5,000 Each?

From a mathematical perspective, investing ₹10,000 every month produces the same overall investment amount whether it is placed into one SIP or divided into two SIPs of ₹5,000 each. If both investments are made in the same mutual fund with identical returns, the final corpus will also be the same.

The real difference lies in diversification rather than investment size. Splitting your monthly contribution across two different mutual funds can reduce concentration risk if the funds belong to different categories, such as large-cap and mid-cap funds. This diversification may improve portfolio balance without changing your total monthly investment.

Therefore, the decision should depend on your investment strategy instead of the number of SIPs. A well-diversified portfolio can offer better risk management, while a single carefully selected fund may be easier to monitor.

Diversification Versus Portfolio Simplification Benefits

Investing in multiple mutual funds spreads your money across different sectors, investment styles, and fund managers. This diversification reduces dependence on the performance of a single fund and may improve portfolio stability over time.

However, maintaining several SIPs also increases the effort required to monitor your investments. A single high-quality fund is easier to track, review, and rebalance when necessary.

Before splitting your investment, consider the following:

  • Choose multiple funds if you want broader diversification.
  • Choose one fund if you prefer simple portfolio management.
  • Avoid investing in several funds with highly similar portfolios.
  • Review your investment strategy periodically instead of adding funds unnecessarily.

How Much Is a ₹50,000 Monthly SIP for 5 Years?

Investing ₹50,000 every month through a Systematic Investment Plan (SIP) can help you build substantial wealth over a five-year period. A SIP encourages disciplined investing while reducing the impact of short-term market volatility through rupee cost averaging. Instead of trying to time the market, you invest a fixed amount each month and accumulate more units when prices fall.

Assuming an estimated 12% annual return, your total investment over 60 months will be ₹30,00,000. Based on this return, your estimated maturity value can exceed ₹41 lakh, depending on market performance and the exact timing of your investments. Since mutual fund returns are market-linked, the final amount may be higher or lower. This example highlights how compounding and consistent investing can generate significantly better long-term results than keeping money in a traditional savings account.

Projecting Wealth Accumulation Over Medium Terms

A five-year SIP offers a practical balance between investment growth and manageable commitment. Although equity markets fluctuate, investing consistently allows you to benefit from rupee cost averaging. During market declines, your fixed monthly investment purchases more mutual fund units, which can improve long-term returns when markets recover.

Instead of reacting to short-term price movements, focus on staying invested throughout the investment period. Regular contributions and patience are often more rewarding than attempting to predict market highs and lows. Reviewing your portfolio once a year is also important. It helps ensure your asset allocation, risk level, and investment objectives remain aligned with your financial goals. If your income or goals change, you can adjust your SIP amount or rebalance your portfolio accordingly without interrupting your long-term investment strategy.

What Is the 15 × 15 × 15 Rule?

The 15 × 15 × 15 Rule is a popular concept that demonstrates the power of long-term SIP investing and compound growth. The rule assumes that you invest ₹15,000 every month for 15 years while earning an estimated 15% annual return. Under these assumptions, your investment has the potential to grow to more than ₹1 crore.

This rule is not a guaranteed outcome but a simple illustration of how consistent investing, time, and compounding work together. The longer your money stays invested, the greater the effect of compounding becomes. Rather than chasing quick profits or trying to time the stock market, the rule encourages investors to remain disciplined and focused on long-term wealth creation. While actual returns vary, the underlying principle remains valuable for anyone planning future financial goals.

Maximizing Long-Term Wealth Through Consistency

Building wealth through a SIP depends more on consistency than on finding the perfect time to invest. Equity-oriented mutual funds have historically delivered attractive long-term returns, although past performance does not guarantee future results. Staying invested through different market cycles gives your portfolio a better chance to benefit from long-term economic growth.

You can strengthen your investment strategy by following a few simple practices:

  • Automate your SIP to avoid missing monthly contributions.
  • Increase your SIP amount whenever your income rises.
  • Review your portfolio annually and rebalance if necessary.
  • Stay invested during market corrections instead of stopping your SIP.
  • Align your investments with your financial goals and risk tolerance.

Maintaining a disciplined investment approach can significantly improve your chances of achieving long-term financial success. Over time, regular contributions, compounding, and patience work together to create a larger investment corpus. With a well-planned SIP strategy, you can steadily move closer to major goals such as buying a home, funding education, or building a comfortable retirement fund.


FAQ

How Does a SIP vs FD Calculator Work?

A SIP vs FD calculator helps you compare the estimated returns of a Systematic Investment Plan (SIP) with the guaranteed returns of a Fixed Deposit (FD). A SIP vs FD calculator uses your investment amount, tenure, expected SIP return, and FD interest rate to estimate the maturity value of both options. By using a SIP vs FD calculator, you can easily compare potential returns, understand the impact of compounding, and choose the investment option that best matches your financial goals and risk tolerance.

Are SIP returns guaranteed by the government?

No. SIP returns are not guaranteed because they invest in market-linked mutual funds. Their performance depends on the movement of equity or debt markets, so returns can vary over time.

Unlike Fixed Deposits, which provide predetermined interest rates and deposit insurance within applicable limits, SIPs carry investment risk. However, historical data shows that equity mutual funds have generally delivered higher long-term returns than traditional fixed-income investments. Investors should understand the associated risks and invest with a long-term perspective instead of expecting guaranteed returns.

Can I stop or pause my SIP anytime?

Yes. Most mutual fund companies allow investors to pause, stop, restart, or modify their SIPs without charging a penalty. This flexibility makes SIPs suitable for individuals whose income or financial commitments may change over time.

If you face a financial emergency or wish to adjust your monthly investment amount, you can usually update your SIP instructions through your fund house or investment platform. Although pausing a SIP is easy, maintaining regular investments whenever possible helps maximize the benefits of long-term compounding and disciplined investing.

Which Is Better for Short-Term Financial Goals?

For financial goals that are less than three years away, Fixed Deposits are generally the better choice. They offer capital protection, predictable returns, and lower risk, making them suitable for emergency funds, planned purchases, or other short-term requirements.

Equity SIPs are designed for long-term wealth creation and can experience market volatility over shorter periods. Investing money that you may need soon in equity funds increases the risk of short-term losses. Choosing secure fixed-income options for near-term goals helps protect your capital while ensuring your funds remain available when required.


Conclusion

Choosing between a SIP vs FD Calculator ultimately comes down to strategy. Your personal investment goals and market risk comfort dictate the choice. For instance, your primary goal might center on long-term wealth accumulation and retirement. If so, a SIP estimation tool clearly illustrates compound equity growth. It shows how regular investments can expand your net worth over time. Consequently, evaluating SIP vs FD options helps you choose the right financial instrument for your roadmap.

On the other hand, you might require absolute capital safety today. Specifically, you might need complete return predictability and short-term financial liquidity. In that case, a fixed deposit estimator provides precise, guaranteed figures. Understanding these distinct mathematical models ensures you select the right tool.

Successful wealth builders rarely rely on just a single asset class. Instead, utilizing both digital calculation tools allows you to structure resilient roadmaps. You can seamlessly pair high-growth systematic equity investments with fixed-yield assets. Test both calculators today using your actual target numbers and timeframes. Ultimately, you will establish a realistic blueprint that balances growth with absolute security.

What Is Budgeting? A Beginner’s Guide to Managing Money

What Is Budgeting? A Beginner’s Guide to Managing Money

Many people feel anxiety when checking their bank accounts at the end of the month. Consequently, you might find yourself constantly asking what is budgeting. You are certainly not alone in this financial journey. At its core, determining what is budgeting means creating a proactive plan. Furthermore, you decide exactly how you will spend, save, and invest your money. This allows you to track incoming revenue accurately against outgoing expenses. As a result, this daily habit ensures you always have enough cash available for your needs.

The Consumer Financial Protection Bureau (CFPB) offers excellent financial guidance. Specifically, they explain that establishing a solid financial plan reduces stress. Additionally, it helps you achieve incredible long-term stability. A common misconception is that tracking money requires giving up fun. However, managing money does not mean restricting your entire lifestyle. Similarly, it does not mean cutting out all your favorite activities entirely.

Instead, understanding what is budgeting gives you the ultimate freedom to spend purposefully. Therefore, you clearly understand exactly where your cash goes every single week. Because of this, you can make highly informed, confident financial decisions. This comprehensive guide will walk you through effective money management. Moreover, we will explore practical strategies and popular financial frameworks. Ultimately, these proven methods will help you build a healthy financial relationship today.

How to Budget as a Beginner?

Learning how to budget as a beginner may seem overwhelming at first, but it becomes much easier once you build a simple routine. A budget is simply a plan for your money. It helps you understand where your income goes and ensures your essential expenses are covered before you spend on non-essential items.

Start by listing all your monthly income sources. Then subtract your fixed expenses, such as rent, utilities, insurance, and groceries. Once you know your essential costs, assign the remaining money to savings, debt repayment, and discretionary spending. This simple approach helps you stay in control of your finances instead of wondering where your money disappeared.

You do not need expensive software or complex spreadsheets to create your first budget. A notebook, spreadsheet, or free budgeting app is enough. The key is consistency. Tracking your money every month helps you recognize spending patterns, reduce unnecessary expenses, and make better financial decisions over time.

Start With Tracking Expenses

Tracking every purchase for one month gives you a realistic picture of your spending habits. Many beginners discover they spend far more on dining out, online shopping, or unused subscriptions than expected. Recording each expense creates awareness and helps reduce impulse purchases without feeling restrictive.

Write down every transaction as soon as it happens. Small daily purchases may seem insignificant, but they quickly add up over a month. Reviewing your expenses weekly also makes it easier to spot problem areas before they become major financial issues.

As you build this habit, you will naturally begin making smarter spending decisions. Over time, tracking expenses becomes less of a chore and more of a valuable financial routine that supports long-term stability.

What Are the 7 Steps of Budgeting?

The 7 steps of budgeting provide a simple framework for organizing your finances and creating a sustainable money management system. Following these steps makes budgeting less stressful and helps you stay focused on your financial goals. Whether you are creating your first budget or improving an existing one, this structured approach keeps you on track.

The seven budgeting steps include:

  1. Calculate your total monthly net income.
  2. List all fixed monthly expenses.
  3. Estimate variable expenses, such as groceries and entertainment.
  4. Set realistic financial goals.
  5. Choose a budgeting method that suits your lifestyle.
  6. Allocate money to needs, wants, savings, and debt.
  7. Review your budget weekly and adjust it as your circumstances change.

Following these steps consistently creates better spending habits and helps you make informed financial decisions throughout the year.

Choosing Your Budget Method

Choosing the right budgeting method increases your chances of sticking with your financial plan. The best system is one you can maintain consistently without feeling overwhelmed. A complicated budget that you abandon is far less effective than a simple one you follow every month.

Popular budgeting methods include the 50/30/20 rule, zero-based budgeting, and envelope budgeting. Try one method for at least a month before deciding whether it fits your lifestyle. If it feels too restrictive or difficult, switch to another approach rather than giving up on budgeting altogether.

Remember that your budgeting method should support your financial goals, not create unnecessary stress. Flexibility often leads to better long-term success.

What Are the 4 Pillars of Budgeting?

The 4 pillars of budgeting create the foundation for effective money management. Each pillar plays a different role, but together they help you build financial stability and prepare for future goals. Understanding these core elements allows you to create a balanced budget that supports both your current needs and long-term financial health.

The four pillars are:

  • Income – Every source of money you earn.
  • Expenses – All money spent on essentials and lifestyle choices.
  • Savings – Funds reserved for emergencies and future goals.
  • Debt Management – A strategy for reducing loans and credit balances.

When these four pillars work together, your budget becomes a practical financial plan instead of a simple list of numbers. Reviewing them regularly helps you stay in control as your income or expenses change over time.

Balancing Income and Outflow

A healthy balance between income and expenses is essential for financial success. If your spending consistently exceeds your income, your savings will shrink and debt will continue to grow. Monitoring both sides of your budget helps you identify problems early.

Review your budget every week or month to ensure your financial priorities remain aligned. Small adjustments, such as reducing unnecessary spending or increasing savings, can significantly improve your financial health over time.

Keeping your income, expenses, savings, and debt in balance creates a sustainable budgeting system that adapts as your financial situation changes.

What Is Budgeting in Simple Words?

Budgeting is simply creating a spending plan before the month begins. Instead of wondering where your money went, you decide in advance how every dollar will be used. This proactive approach gives you greater confidence and reduces financial stress.

Think of a budget as a roadmap for your money. It ensures your essential bills are paid, your savings continue growing, and you still have money available for entertainment and personal interests. Planning ahead removes uncertainty and helps you make smarter financial decisions throughout the month.

Budgeting is not about restricting yourself from enjoying life. It is about spending intentionally so your money supports your priorities and long-term goals. Even a simple budget can provide greater financial stability and peace of mind.

Taking Control of Money

Taking control of your money means making financial decisions with purpose instead of reacting to unexpected expenses. A well-planned budget allows you to pay your bills confidently while steadily building savings for future goals.

As your budgeting habits improve, you become more aware of where your money goes each month. This awareness makes it easier to reduce unnecessary spending without feeling deprived. Over time, budgeting shifts from feeling restrictive to becoming a practical tool that gives you greater financial freedom and confidence.

What Is the 50/30/20 Budgeting Rule?

The 50/30/20 budgeting rule is a simple and effective money management method that helps you divide your after-tax income into three spending categories. Popularized by financial expert Elizabeth Warren, this budgeting strategy recommends allocating 50% of your income to essential needs, 30% to personal wants, and 20% to savings or debt repayment. It provides a balanced approach that supports both your current lifestyle and long-term financial goals.

Under this rule, essential expenses include housing, groceries, utilities, insurance, transportation, and minimum loan payments. The wants category covers discretionary spending, such as dining out, entertainment, shopping, and travel. The remaining 20% should be directed toward building an emergency fund, investing, retirement planning, or paying off high-interest debt. The 50/30/20 budgeting rule is especially useful for beginners because it simplifies budgeting, encourages consistent saving, and promotes healthier financial habits without requiring detailed expense tracking.

Breaking Down the Needs and Wants Categories

Successfully following the 50/30/20 budgeting rule starts with correctly separating needs from wants. Needs are essential expenses that support your daily life, while wants are optional purchases that improve your lifestyle but are not necessary for survival. Understanding this difference helps prevent overspending and keeps your budget aligned with your financial goals.

Examples of needs include rent or mortgage payments, groceries, electricity, transportation, insurance, and minimum debt payments. Wants may include streaming subscriptions, dining at restaurants, vacations, premium shopping, and other leisure activities. Reviewing your monthly expenses regularly helps you identify unnecessary spending and redirect more money toward savings, investments, or debt repayment. Maintaining this balance creates a stronger financial foundation and supports long-term financial stability.

What Is the 7-7-7 Rule for Money?

The 7-7-7 rule for money is a flexible financial planning strategy designed to help individuals balance short-term security with long-term wealth creation. Although it is not an official financial guideline, the concept encourages you to organize your financial priorities into three manageable stages, each represented by the number seven. The exact interpretation may vary, but the goal is to create a structured approach to saving, debt management, and investing.

Many people use the 7-7-7 rule for money to focus on building an emergency fund, reducing high-interest debt, and investing consistently for future financial goals. Breaking financial objectives into smaller, organized phases makes money management less overwhelming. This approach encourages steady progress while helping you maintain a balance between present financial responsibilities and future wealth-building opportunities.

Applying the Multi-Tiered Approach Effectively

Following the 7-7-7 rule for money begins with evaluating your current financial situation. Review your monthly income, spending habits, savings, and outstanding debts to determine where your money can be used more effectively. Creating a realistic budget helps identify opportunities to increase savings without affecting essential expenses.

Focus on one financial priority at a time while continuing to make consistent progress toward the others. Automating savings and investment contributions can help you stay disciplined throughout the process. Reviewing your financial plan every few months allows you to adjust your goals as your income, expenses, or life circumstances change. Consistency, rather than perfection, is the key to making any structured financial strategy successful over the long term.


Frequently Asked Questions

Why do most beginner budgets fail?

Most beginner budgets fail because they are too restrictive. Many people eliminate all entertainment or discretionary spending, making the budget difficult to maintain. A successful budget includes realistic allowances for both essential expenses and occasional enjoyment, making it easier to stick with long term.

How often should I check my budget?

Review your budget at least once a week. Frequent reviews help you identify overspending early, monitor progress toward your financial goals, and adjust your spending if unexpected expenses arise during the month.

Do I need a fancy app to budget?

No. You can successfully manage your money using a notebook, spreadsheet, or free budgeting app. The most effective budgeting tool is the one you use consistently. Building the habit of tracking your finances matters far more than choosing expensive software.


Conclusion: Take Charge of Your Financial Future

Understanding exactly what is budgeting represents your first critical step. Indeed, it is non-negotiable for permanently securing your long-term financial future. It actively removes the terrifying mystery from your bank accounts. Furthermore, it swiftly replaces overwhelming anxiety with actionable, supreme confidence. Carefully tracking your daily income grants you immense power.

Strategically planning your monthly expenses gives you immediate control. Consequently, you permanently stop reacting in panic to surprise bills. You finally start proactively building generational wealth for your family. If you are managing household finances with multiple dependents, exploring specific budgeting ideas for large families provides incredibly beneficial strategies. Achieving successful money management requires consistent, dedicated practice over time. Your first few planning attempts will absolutely feel clumsy. Similarly, you will find the process frustrating and awkward initially.

You will likely need to adjust your strict spending categories frequently. Therefore, you must find the perfect mathematical balance for your life. This is a completely normal part of the educational process. Remain highly patient with yourself and forgive inevitable mistakes. Finally, actively celebrate your small daily financial victories along the way. Grab a piece of paper or download a highly-rated mobile app today. Establish clear goals and track your spending with brutal honesty. Ultimately, watch as your new budgeting habits beautifully transform your entire life.

Managing Education Expenses Wisely: A Complete Guide

Managing Education Expenses Wisely: A Complete Guide

College costs continue to rise every single year. For many families, paying for tuition, housing, and textbooks feels completely overwhelming. Fortunately, managing education expenses wisely can help you avoid massive, lifelong debt. You just need a solid financial strategy right from the start.

When you plan ahead, you actively protect your financial future. Learning how to navigate financial aid, scholarships, and daily budgeting makes a huge difference. Exploring options through Federal Student Aid provides a fantastic starting point for finding official government grants and subsidized loans.

Why does this specific topic matter so much? Education remains one of the biggest financial investments you will ever make. However, borrowing too much money can seriously delay your other major life goals. High student loan payments can stop you from buying a house for decades.

Therefore, you must proactively control your costs from the very beginning. By reviewing official resources, you build a remarkably strong foundation for your entire college journey.

In this complete guide, we will break down the absolute best ways to handle college costs today. You will learn exactly how to create a realistic budget that actually works. We will help you find hidden scholarships and institutional grants. Keep reading to discover how to fund your higher education without sacrificing your long-term financial freedom.

What Is the 70/20/10 Rule of Money?

The 70/20/10 rule of money is a simple budgeting method that helps you divide your income into three clear categories. It is especially useful for students who want to manage education expenses wisely without creating a complicated financial plan. Under this approach, you allocate 70% of your income to essential living expenses, 20% to savings or debt repayment, and 10% to investments, charitable giving, or personal development. This percentage-based system reduces the risk of overspending while encouraging consistent saving habits. Whether your income comes from a part-time job, scholarship, or monthly allowance, this framework provides a practical way to stay financially organized. It also helps you prepare for unexpected costs while ensuring essential expenses remain your top priority. Over time, following this budgeting strategy can improve financial discipline and reduce money-related stress during your academic journey.

Applying the 70/20/10 Rule to Student Life

Students can easily adapt the 70/20/10 budgeting rule to their everyday finances. Keep your living expenses within the 70% limit by covering necessities such as rent, groceries, transportation, and utility bills. Allocate 20% toward building an emergency fund or paying down student loans if applicable.

Use the remaining 10% for investments, educational resources, professional certifications, or charitable contributions. This balanced approach helps you meet current needs while preparing for future financial goals. By following these spending limits consistently, you can avoid unnecessary debt and maintain better control over your education expenses.

What Is the 3 6 9 Rule of Money?

The 3 6 9 rule of money is a financial planning method that organizes goals into short-, medium-, and long-term milestones. For students, this approach makes managing education expenses wisely more structured and less overwhelming.

The number 3 represents goals you want to achieve within three months, such as purchasing textbooks or paying course-related fees. Meanwhile, 6 focuses on medium-term objectives over the next six months, including saving for your next tuition payment. Finally, 9 represents longer-term financial goals, typically nine months or more, such as covering housing costs or preparing for future academic expenses.

Dividing large financial responsibilities into smaller milestones helps students stay motivated and track progress more effectively. Instead of worrying about an entire academic year’s expenses at once, you can focus on one achievable target at a time while maintaining better financial stability.

Achieving Financial Milestones Through Better Planning

Breaking financial goals into three, six, and nine-month periods makes large education costs easier to manage. Three-month goals can include textbooks, study materials, or exam fees. Six-month targets may cover tuition installments or technology upgrades needed for classes.

Nine-month planning helps prepare for housing deposits, internship expenses, or the next academic year. This phased strategy improves budgeting discipline and reduces the chance of facing unexpected financial shortages during your studies.

How to Reduce Expenses in School?

Reducing school expenses starts with identifying unnecessary costs and making smarter spending decisions. One of the easiest ways to save money is by buying used textbooks, renting digital versions, or borrowing books from the school or public library. Students can also reduce daily expenses by preparing meals at home, carrying a reusable water bottle, and using public transportation, cycling, or carpooling whenever possible. Small savings made throughout the academic year can add up significantly.

Managing education expenses also means taking advantage of student discounts on software, electronics, clothing, and entertainment. Avoid impulse purchases and focus on spending only on items that support your education. Creating a monthly budget helps you monitor where your money goes and identify areas for improvement. By adopting simple money-saving habits and controlling lifestyle expenses, students can reduce financial stress while staying focused on their academic goals.

Smart Textbook and Study Material Strategies

Textbooks and study materials often represent a significant portion of education expenses, but there are many ways to reduce these costs. Purchasing second-hand books, renting textbooks, or using digital editions can save a substantial amount each semester. Many schools and public libraries also provide free access to required learning materials.

Students can further reduce costs by exchanging books with classmates or using open educational resources (OERs) available online. Printing only essential documents and using digital notes instead of paper notebooks also helps lower expenses. These practical strategies allow students to access quality learning resources without exceeding their academic budget.

How Are You Planning to Manage Your Education Expenses?

Managing education expenses begins with creating a realistic financial plan before each academic term. List all expected costs, including tuition fees, books, transportation, accommodation, supplies, and personal expenses. Then compare these expenses with your available income from family support, scholarships, part-time work, or educational loans.

A well-planned budget helps you avoid unnecessary spending and ensures essential expenses receive priority. Keeping a separate bank account for education-related funds can also reduce the temptation to spend money on non-essential purchases. Regularly reviewing your budget allows you to adjust your spending as circumstances change. Careful financial planning helps students stay organized, minimize debt, and complete their education with greater financial confidence.

Creating a Realistic Monthly Spending Plan

A monthly student budget helps you control spending and stay financially organized throughout the academic year. Begin by separating fixed expenses, such as tuition, rent, and transportation, from variable expenses like entertainment, shopping, and dining out. Prioritizing essential costs reduces the risk of financial shortfalls.

Track your spending every week using a budgeting app or a simple spreadsheet. Reviewing your expenses regularly helps identify unnecessary purchases and creates opportunities to save more. Updating your budget whenever your income or expenses change keeps your financial plan accurate and supports better long-term money management.

What Is the 7-7-7 Rule for Money?

The 7-7-7 rule for money is a flexible financial planning strategy that helps individuals balance short-term savings, debt management, and long-term financial goals. Although there is no single official definition, the concept encourages organizing your finances into three structured stages to make money management simpler and more consistent.

For students managing education expenses, the 7-7-7 rule for money can encourage building an emergency fund, controlling debt, and saving for future goals at the same time. Dividing financial priorities into manageable stages makes budgeting less overwhelming and promotes steady progress. This structured approach helps students develop healthy financial habits that remain valuable long after graduation.

Applying Structured Multi-Tiered Savings

A multi-tiered savings strategy helps students prepare for both current and future financial needs. Instead of saving for only one goal, divide your savings into separate categories, such as emergency expenses, upcoming education costs, and long-term financial goals. This approach provides greater flexibility when unexpected expenses arise.

Automating small monthly savings contributions makes the process easier and more consistent. Even modest deposits can grow over time and reduce financial pressure during your studies. Following a structured savings plan builds stronger financial discipline and creates a solid foundation for long-term financial stability.

What Is the 50/30/20 Rule of Money?

The 50/30/20 rule of money is one of the most popular budgeting methods for balancing essential expenses, personal spending, and long-term financial goals. When managing education expenses wisely, this framework helps students prioritize their finances effectively. Under this rule, 50% of your income covers essential needs such as tuition, rent, groceries, transportation, and utility bills. The remaining 30% is reserved for discretionary spending, including entertainment, dining out, or hobbies. Finally, 20% goes toward savings, emergency funds, or debt repayment. This budgeting strategy encourages responsible spending without eliminating enjoyable activities. It also helps students avoid financial pressure by ensuring essential academic costs receive priority. Following this method consistently can improve money management skills while building healthy financial habits that remain valuable long after graduation.

Balancing Needs and Wants as a Student

Understanding the difference between needs and wants is essential for effective budgeting. Tuition, textbooks, groceries, rent, and transportation are necessary expenses that should always come first.

Entertainment, online shopping, and dining out belong in the discretionary category. Limiting these purchases allows you to save more and stay financially stable throughout the academic year without sacrificing your overall well-being.


Frequently Asked Questions

How can students reduce the cost of textbooks?

Students can reduce textbook expenses by renting digital editions, purchasing used books, borrowing from campus libraries, or sharing copies with classmates. Comparing prices before the semester begins often results in significant savings compared to buying new books from campus bookstores.

Is it wise to take on part-time work while studying?

Working part-time can help cover education expenses while providing valuable work experience. However, students should balance work hours carefully to ensure employment does not negatively affect academic performance, physical health, or overall well-being.

What is the best way to track daily student spending?

Using a budgeting app or maintaining a simple spreadsheet is an effective way to monitor daily expenses. Reviewing your transactions regularly helps identify unnecessary spending and keeps you accountable to your monthly budget.

How do I build an emergency fund on a student budget?

Start by saving a small amount from every paycheck, scholarship, or monthly allowance. Even modest contributions grow over time. Keep your emergency savings in a separate account so the money remains available for unexpected expenses such as medical bills, urgent travel, or essential academic costs.


Conclusion: Mastering the Art of Managing Education Expenses Wisely

Navigating continuously rising college costs certainly does not have to be a highly stressful, debt-inducing experience for you. Managing education expenses wisely simply requires deliberate early preparation, continuous financial research, and incredibly careful daily spending discipline. When you actively take the necessary time to fully understand your diverse financial options, you permanently secure a much brighter financial future.

You successfully and permanently protect yourself from the heavy, suffocating, lifelong burden of excessive student loan debt. This ultimate, hard-earned financial freedom subsequently allows you to actively pursue your absolute dream career without any lingering financial worry. You can confidently and easily buy a home, start a beautiful family, or travel the entire world immediately after your college graduation.

Throughout this highly comprehensive and detailed guide, we extensively explored several highly practical, proven strategies to actively save your money. We deeply discussed the highly critical importance of building a realistic budget that actively tracks every single dollar you spend daily. Additionally, exploring funding options such as these top scholarships for Indian students can drastically lower your overall tuition burden.

Actively use this crucial financial knowledge to fund your degree smartly, safely, and highly confidently. Your successful future self will certainly thank you for your incredibly diligent financial planning today.