
Joint Bank Accounts vs. Power of Attorney: What You Must Know
Managing money for an aging parent or loved one often leads families to compare Joint Account vs POA arrangements. Both can provide financial access, but they create very different legal relationships. A joint account can give another person ownership rights. A power of attorney generally gives an agent authority to act for the account owner without transferring ownership.
Many families choose joint ownership because it seems simple and convenient. However, that convenience can create problems involving inheritance, creditors, taxes, Medicaid eligibility, and family disputes. The right arrangement depends on the account holder’s goals and applicable state law. The Consumer Financial Protection Bureau also explains that people managing another person’s money should understand their legal responsibilities.
Before choosing either option, consider what happens during the owner’s lifetime and after death. You should also understand who can access the money, who owns it, and what happens when an account holder dies. These differences can affect the entire estate.

If one person dies on a joint bank account, who gets the money?
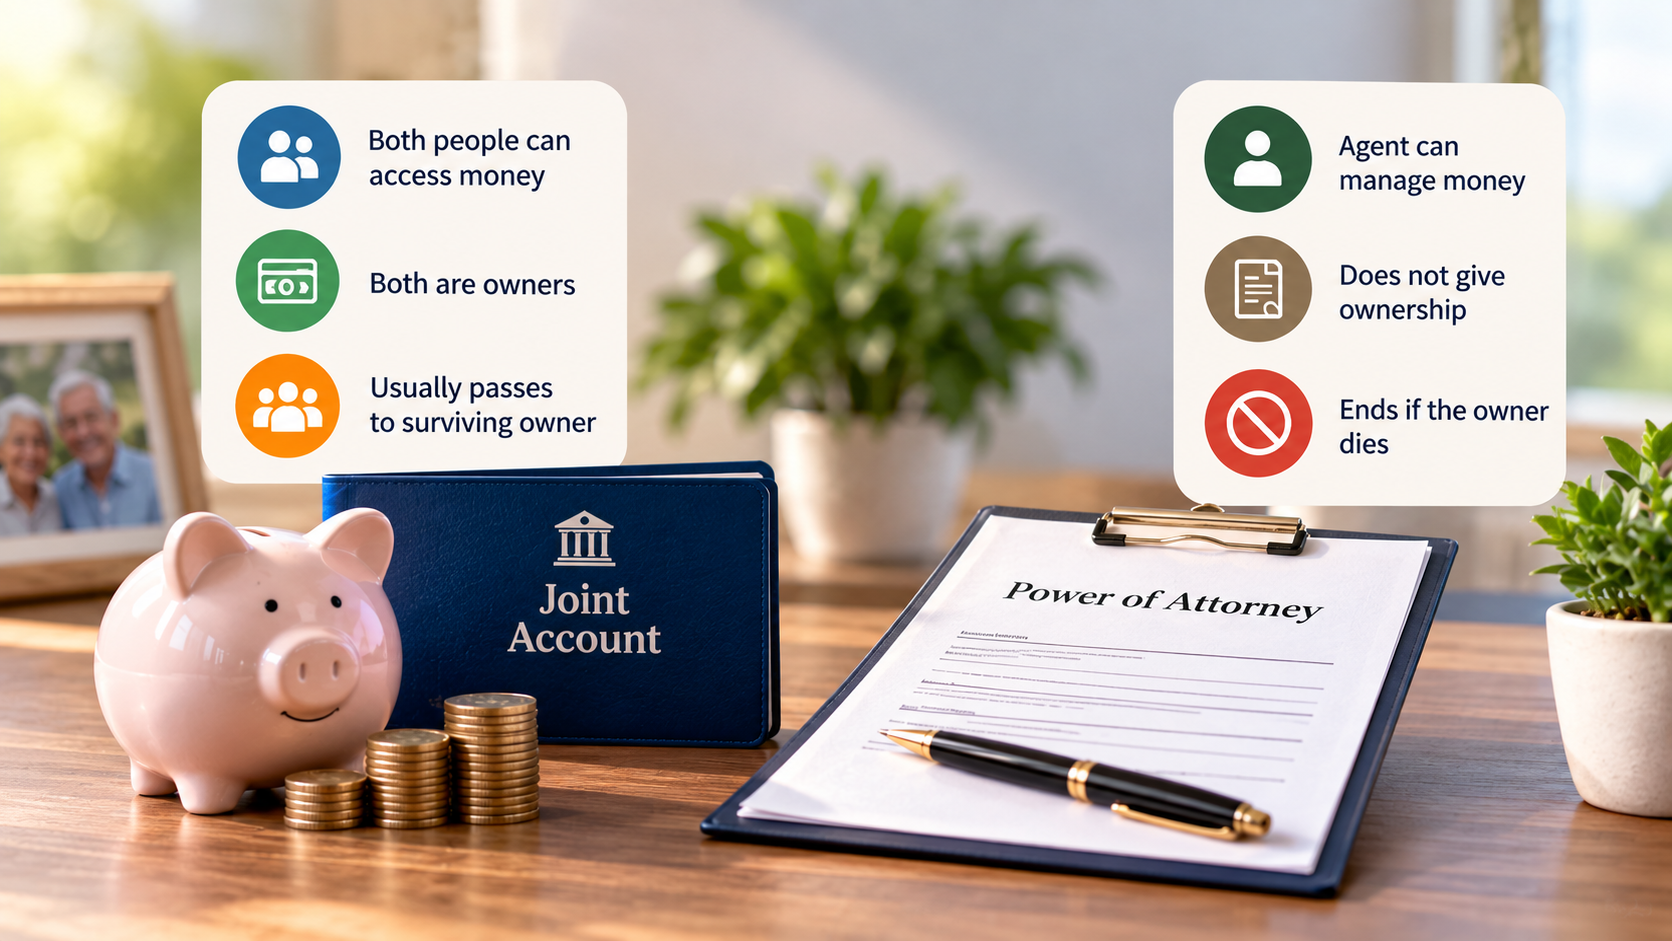
When one person dies, the surviving owner of a joint account may receive the remaining balance automatically if the account includes rights of survivorship. The exact result depends on the account agreement and state law. Not every joint account uses the same ownership arrangement, so families should check the account documents before assuming the money automatically belongs to the survivor.
With a survivorship account, the deceased owner’s interest generally passes to the surviving co-owner outside probate. This can make the process faster than transferring assets through a will. The survivor typically provides the bank with a certified death certificate and completes any required paperwork.
However, disputes can still arise. For example, heirs may argue that the deceased added someone to the account only for convenience. Courts may examine evidence about the account holder’s intent and applicable state law.
Understanding these rules is essential when comparing Joint Account vs POA, because a joint owner generally has ownership rights that a POA agent does not.
Bypassing the Probate Process
A joint account with rights of survivorship can usually pass directly to the surviving owner rather than becoming part of the deceased owner’s probate estate. This feature can simplify access to the money after death. The survivor normally works with the bank to provide a death certificate and update the account records.
However, a will does not necessarily control a jointly owned account with valid survivorship rights. The account agreement and applicable state law can determine who receives the balance. This distinction matters when someone expects their will to divide all financial assets equally among several heirs.
For example, a parent may leave instructions in a will dividing assets among three children. If the parent also holds a survivorship account with only one child, that account may pass to the surviving child instead. Families should also consider whether they have enough emergency savings to handle unexpected financial needs without disrupting other assets.
Disputes can still occur if another heir claims the joint ownership arrangement did not reflect the parent’s true intentions. Courts may consider the circumstances surrounding the account and relevant evidence.
Therefore, families should review account ownership, beneficiary designations, and estate documents together instead of relying on the will alone.
Who legally owns the money in a joint account?
A joint account generally gives each named owner significant rights over the account. The exact ownership rules depend on the account agreement and state law. In many joint accounts, each co-owner can access the funds without getting permission from the other owner.
This differs from a power of attorney arrangement. A person acting under a POA normally serves as an agent for the account owner, known as the principal. The agent can perform financial transactions within the authority granted by the document. However, the agent does not automatically become the owner of the principal’s money.
This distinction is one of the most important differences in a Joint Account vs POA comparison. A joint owner may have personal rights to the funds, while a POA agent generally must use the money for the principal’s benefit.
Families should also avoid assuming that contributing most of the money automatically determines legal ownership. Ownership disputes can depend on state law, account terms, and the circumstances surrounding the deposits. Understanding banking tips and tricks for managing your finances can help account holders review these arrangements more carefully.
Equal Withdrawal Rights Under Law
Joint account holders often have broad withdrawal rights. In many standard joint accounts, either owner can make withdrawals without obtaining approval from the other owner. The bank typically follows the account agreement rather than investigating how much money each person originally deposited.
This creates an important risk. One co-owner may withdraw a substantial portion or even the entire available balance. The other owner may then need to pursue legal remedies if they believe the withdrawal violated their rights. These risks make it important to maintain short-term and long-term savings goals that reflect your financial needs and circumstances.
However, withdrawal authority does not always settle ultimate ownership disputes. A court may examine evidence about who contributed the money, why the account was created, and what the parties intended. State law can also affect the result.
A POA agent operates under a different legal framework. The agent generally must act according to the principal’s instructions and in the principal’s interests. Misusing the principal’s money can expose the agent to civil liability and other legal consequences.
Because of these differences, families should understand the account agreement before adding another person as a joint owner.
What are the disadvantages of a joint account?
Joint accounts can provide convenience, but they also create several financial and legal risks. Adding another person as a co-owner may expose the account to that person’s financial problems. Depending on state law and the circumstances, creditors, legal judgments, bankruptcy proceedings, or other claims may affect jointly held funds. Learning about good financial habits that build wealth can also help families make more deliberate decisions about managing and protecting their money.
Joint ownership can also complicate estate planning. A surviving co-owner may receive the balance even when the deceased person intended other heirs to share the money. That difference can create disagreements among family members and potentially lead to litigation.
Tax and government-benefit consequences also require attention. Adding someone to an account or transferring money may have consequences under applicable tax or benefits rules. Medicaid eligibility, in particular, can involve detailed state-specific rules.
Another concern is control. A joint owner generally has broader access than a POA agent. If the relationship breaks down, removing or restricting the other person may become difficult.
Before creating a joint account, consider whether the goal is shared ownership or simply financial assistance. If the goal is only assistance with managing money, a properly drafted POA may better match that purpose. You can also review the best places to keep your savings safely when deciding how and where to hold important funds.
Risk of Misappropriation and Conflict
Joint ownership can create family conflicts because both owners may have substantial access to the account. A person who adds a relative for convenience may not realize that the relative can obtain broader rights than expected.
This becomes particularly important when the account contains an older person’s retirement savings or other substantial assets. If one co-owner withdraws money for personal expenses, the other family members may challenge those transactions later.
A POA creates a different relationship. The agent generally manages the principal’s money on the principal’s behalf rather than receiving ownership simply because they have access. Agents may also have recordkeeping and fiduciary responsibilities under applicable law.
However, a POA does not eliminate every risk. An agent can still misuse authority, and families may need legal action to recover funds. The document’s scope also matters. A limited POA may authorize specific transactions, while a broader document can provide wider financial authority.
For these reasons, families should consider who needs access, why they need it, and whether ownership should actually change before choosing a joint account.
Can you withdraw money from a joint account if one person dies?
A surviving joint owner can generally continue accessing a joint account after another owner dies when the account provides valid survivorship rights. The surviving owner may usually continue making withdrawals, payments, and other authorized transactions according to the account agreement.
However, families should not assume that every joint account automatically works this way. Some accounts may use different ownership arrangements, and state law can affect the result. Checking the account agreement is therefore important before making significant withdrawals.
The situation is different for a power of attorney. A POA generally ends when the principal dies. After death, the former agent no longer has authority to use the principal’s account under that POA. The estate’s authorized representative must handle the deceased person’s assets instead.
Using a deceased person’s account after POA authority has ended can create serious legal problems. The consequences depend on the transaction, applicable law, and circumstances.
If you are unsure about ownership or withdrawal rights, avoid moving substantial funds until the bank, estate representative, or qualified attorney confirms the proper procedure. Maintaining good financial habits that build wealth can also help reduce the need for rushed financial decisions during unexpected events.
Essential Paperwork and Timing
After a joint account holder dies, the surviving owner should contact the bank and provide the required documentation. A certified death certificate is commonly requested so the financial institution can update its records and remove the deceased owner when appropriate.
The exact process varies by bank and account structure. Some institutions may require additional forms, identification, or updated tax information. The survivor should ask the bank what documents it needs before visiting a branch or submitting paperwork.
It is also important to keep accurate records of transactions made after the death. Although the surviving owner may have access to the funds, significant withdrawals can become relevant if heirs later challenge the ownership arrangement.
A former POA agent faces a different situation. Once the principal dies, the agent’s authority under the POA generally ends. The agent should not continue using the account simply because their name appears on the POA document.
When an estate representative becomes responsible for the deceased person’s assets, that representative should follow the applicable probate and estate procedures. State law and the account agreement determine the specific requirements.
Why do you not tell the bank when someone dies?
Some families delay notifying a bank because they worry that the account will be frozen immediately. This concern can arise when the deceased person had an individual account and the family relies on that money for household bills or other expenses.
However, delaying notification can create additional problems. Financial institutions need accurate information about an account holder’s death so they can follow the correct estate procedures. Access to an individual account may change once the bank receives notice, depending on the account structure and applicable law.
Joint accounts are different. If the account provides valid rights of survivorship, the surviving owner may generally continue accessing the funds. Even then, notifying the bank allows the institution to update its records and confirm the account’s status.
A former POA agent should be especially careful. A power of attorney generally terminates when the principal dies. The former agent should not continue making transactions under that authority after death.
Families should therefore avoid hiding a death to preserve access to funds. Instead, they should identify the account type, contact the financial institution, and determine who has legal authority to manage the assets. Reviewing banking tips and tricks for managing your finances can also help families better understand everyday account management.
Frequently Asked Questions
Does a power of attorney override a joint bank account?
No, a power of attorney generally does not override a joint bank account. In Joint Account vs POA, the agent manages funds for the principal but does not automatically change ownership or survivorship rights.
Does a joint account protect assets from Medicaid look-back rules?
No, a joint account does not automatically protect assets from Medicaid look-back rules. Joint Account vs POA arrangements may still face scrutiny, and ownership depends on applicable state rules and documented contributions.
What is a convenience account compared to a joint account?
A convenience account lets another person help manage an owner’s money without giving that person ownership rights. Unlike a joint account, the helper generally does not receive ownership or survivorship rights.
Conclusion
Choosing between a joint account vs POA requires balancing daily convenience with long-term asset protection. While adding a family member as a joint owner offers immediate access, it exposes your funds to third-party debts, legal judgments, and inheritance disputes. Conversely, a durable power of attorney provides essential bill-paying authority during incapacity while ensuring your money remains protected for your estate and designated heirs. A clear approach to managing money through budgeting can further support long-term financial planning.
Understanding who owns the funds, how survivor rights work upon death, and why banks must be properly notified prevents costly legal entanglements. Instead of relying on joint ownership as a quick estate planning shortcut, consider establishing a formal power of attorney or a convenience account. Review your financial arrangements today, talk openly with your family, and consult an experienced estate planning attorney to ensure your accounts support your long-term goals without compromising your family’s financial security.