
Best Savings Accounts for Kids and Teens
Teaching children financial responsibility early can provide lifelong benefits. Finding the best savings accounts for kids and teens helps families turn allowances, birthday gifts, and first paychecks into healthy financial habits.
According to the Federal Deposit Insurance Corporation (FDIC), introducing children to banking helps establish important financial foundations. Eligible bank deposits receive FDIC insurance, generally up to $250,000 per depositor, per insured bank, for each ownership category.
Without practical financial tools, children may miss important lessons about compound interest, budgeting, and digital banking security.
Modern banking platforms offer youth accounts with parental controls, competitive interest rates, and convenient debit card access. Parents often wonder how these accounts work and which banks provide suitable options.
This guide explores the best savings accounts for kids and teens, including their features, eligibility requirements, ATM access, and benefits. It also explains which accounts help children develop responsible money management skills before adulthood.
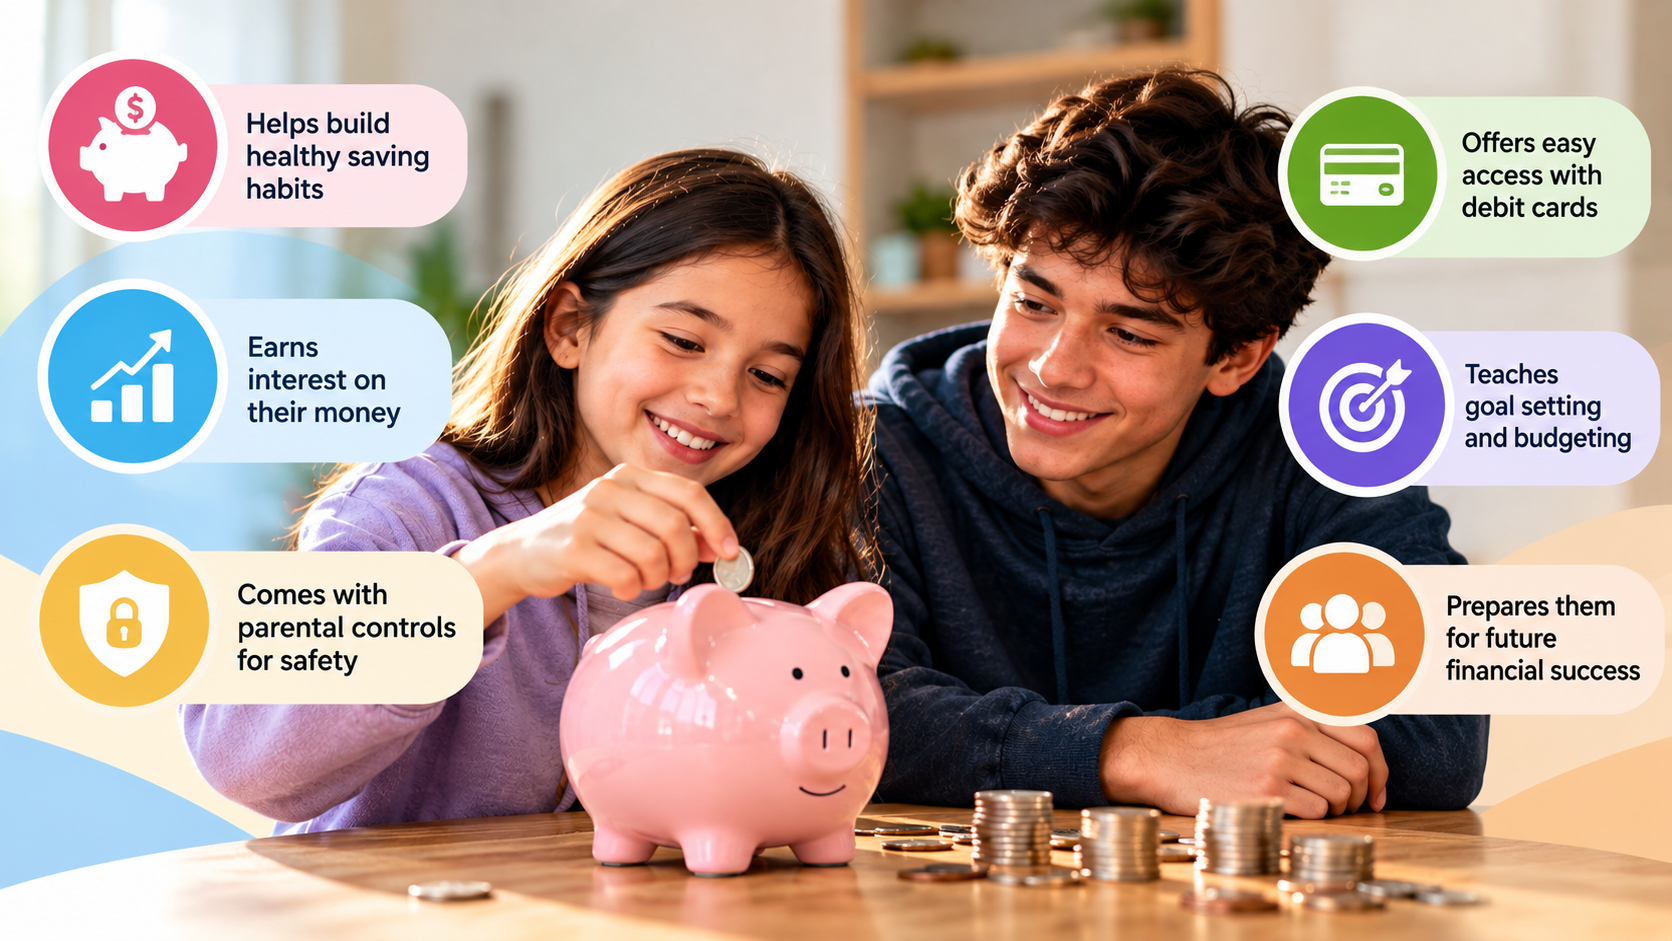

What is the best savings account for a teenager?
The Capital One Kids Savings Account is a strong option for teenagers who want a straightforward way to save money. It charges no monthly maintenance fees and requires no minimum opening or ongoing balance. Its advertised 2.50% APY, effective October 23, 2026, applies to all account balances. However, interest rates are variable and can change.
Parents can connect eligible external accounts to manage deposits and establish recurring savings contributions. The account also supports mobile check deposits, making it convenient for teenagers receiving birthday money or other gifts. Families looking for additional spending flexibility can consider Capital One MONEY Teen Checking alongside the savings account. This combination separates everyday spending from long-term savings. Developing good financial habits that build wealth early can help teenagers make responsible financial decisions. It also introduces teenagers to practical digital banking habits without unnecessary account maintenance costs.
Digital Money Tracking and Growth
Capital One provides digital banking tools that help families monitor savings activity. Parents can schedule recurring deposits and review account transactions through the mobile application. These features make it easier to establish consistent saving habits.
Teenagers can observe their balances and understand how regular contributions increase their savings over time. Monthly interest payments also provide an opportunity to introduce the concept of compound interest.
Parents can use these features to establish practical financial goals. For example, teenagers might save for a new smartphone, college expenses, or an emergency fund. Understanding short-term and long-term savings goals can help teenagers organize their priorities. Regular deposits make these goals easier to achieve.
The account also supports mobile check deposits, helping families deposit birthday checks without visiting a branch. However, parents should review account access and supervision arrangements before opening an account. These digital tools work best when families discuss spending decisions and savings progress regularly.
Which is the best savings account for a child?
The Alliant Credit Union Kids Savings Account is a strong choice for younger children aged twelve and under. It offers a competitive 3.01% APY when the account maintains an average daily balance of at least $100. This requirement makes it important to understand the account’s interest conditions before opening one.
Alliant also provides the initial $5 deposit required to establish the account. There are no monthly maintenance fees, helping children retain their savings. A parent or legal guardian must participate as a joint owner and meet Alliant’s membership requirements.
The account supports online banking, mobile access, and transfers from a parent’s account. These features make it convenient to manage birthday money, holiday gifts, and regular allowances. Parents can introduce children to basic financial concepts while monitoring their account activity. For families prioritizing savings growth and simple account management, Alliant offers a useful starting point.
Building Lifelong Credit Union Benefits
Alliant provides a convenient banking progression as children become teenagers. Children can become eligible for an Alliant Teen Checking account at age thirteen. Their existing Kids Savings Account remains open, so previously accumulated savings do not automatically disappear or transfer.
The Teen Checking account provides a debit card and additional spending flexibility. This allows teenagers to practise managing everyday purchases while maintaining their savings separately.
Parents can also use Alliant’s digital banking features to transfer allowances and monitor account activity. Mobile check deposits make it easier to deposit birthday and holiday checks from home.
Another useful feature is the ability to create supplemental savings accounts for individual goals. Children can save separately for school supplies, electronics, or future expenses.
These features help families introduce increasingly advanced money management skills. However, Alliant’s membership requirements and account eligibility conditions should be reviewed before applying.
Which account is best for teenagers?
The Fidelity Youth Account is worth considering for teenagers who want to learn about saving, spending, and investing. Available to teenagers aged thirteen to seventeen, it combines brokerage features with a debit card option. Unlike a traditional savings account, it allows eligible teenagers to invest in supported securities. Families comparing investment options can also explore cash management accounts versus brokerage accounts to understand their key differences.
The account has no subscription fees, account fees, or minimum opening balance. Teenagers can request a debit card to make everyday purchases using available cash balances.
Parents or guardians must open the account for their teenagers and maintain an eligible Fidelity relationship. However, the teenager owns the account and makes the investment decisions. Parents can monitor activity and provide financial guidance.
The account is particularly useful for families interested in introducing teenagers to investing alongside everyday money management. However, investments carry market risks and do not receive FDIC insurance. Families seeking guaranteed savings interest should consider a separate insured savings account.
Which bank gives ATM under 18?
Chase Bank provides debit card and ATM access to minors through its Chase First Banking account. Available to children aged six to seventeen, this account introduces young users to everyday banking under parental supervision. It includes a Visa debit card that children can use for eligible purchases and cash withdrawals.
Parents can manage spending limits, assign allowances, and monitor transactions through the Chase Mobile app. They can also control where children use their debit cards and how much they withdraw.
Children can withdraw cash from Chase ATMs without a Chase ATM fee. Participating non-Chase ATMs may also provide access, although fees from Chase and the ATM owner can apply.
Chase First Banking has no monthly service fee. However, parents must already hold a qualifying Chase checking account to open one. Other banks, including Bank of America and Wells Fargo, also offer debit card options for eligible minors through youth or joint accounts. Always check age requirements and account-specific ATM charges.
Which bank is best for teenage accounts?
Capital One is a strong choice for families seeking an accessible, fee-free banking platform for children and teenagers. Its Kids Savings Account and MONEY Teen Checking account provide separate options for saving and everyday spending. Together, these products help families introduce responsible money management.
MONEY Teen Checking is available to children aged six and older with parental involvement. It includes a debit card, individual account access, and parental monitoring features. Families can also use savings goals and allowance tools to encourage responsible financial habits.
The account has no monthly maintenance fees or minimum balance requirements. Capital One also provides access to more than 70,000 fee-free ATMs through its network and participating partners.
Another advantage is its integration with Capital One’s broader banking platform. Parents can connect eligible accounts and manage money transfers more conveniently.
However, families should compare savings interest rates, ATM availability, and parental controls before choosing an account. Families can also explore safe places to keep their savings when evaluating different banking options. Capital One works particularly well for families seeking simple digital banking. Its combination of spending and savings options makes it a useful option when comparing the best savings accounts for kids and teens and teaching children practical financial skills before adulthood.
FAQ SECTION
At what age can a child open their own savings account?
In most jurisdictions, a minor cannot legally execute binding financial contracts until age eighteen. Consequently, children and teens under eighteen must open a joint savings account or a custodial account (such as an UTMA or UGMA) alongside a parent or legal guardian. Some institutions permit teenagers aged sixteen or seventeen to open specialized independent accounts with restricted transaction privileges.
Are interest earnings from a child’s savings account taxable?
Yes, interest generated in a child’s bank account is treated as taxable income. Under IRS rules, if a child’s unearned income exceeds the annual statutory threshold, it must be reported on a tax return. Amounts above this limit may be subject to the child’s tax rate or the parents’ marginal rate under federal “kiddie tax” regulations.
What documentation is required to open a minor savings account?
Opening an account for a minor requires identity verification for both the adult and the child. The parent or guardian must provide a government-issued photo ID, Social Security number, and home address. For the minor, banks typically request a Social Security card, birth certificate, or state-issued identification card to confirm dates of birth and legal custody.
What happens to a youth savings account when the teen turns 18?
When a teenager turns eighteen, the financial institution typically transitions the youth account into a standard adult account. For joint accounts, the parent can often remove themselves, granting the young adult sole ownership. For custodial accounts, legal ownership automatically transfers to the beneficiary once they reach the state’s age of majority.
CONCLUSION
Selecting the ideal banking platform establishes the groundwork for your child’s lifetime financial success. Whether you want to open a first account for an elementary schooler or equip an active teenager with a debit card, matching their financial maturity to the proper bank features is essential. Focus on institutions that eliminate recurring monthly maintenance fees, provide accessible customer support, and reward consistency with competitive annual yields.
The best savings accounts for kids and teens do more than merely stash away allowance funds; they serve as living classrooms for compound interest, budgeting, and sensible spending. Involve your child in regular balance reviews, discuss monthly savings goals, and let them experience financial decision-making firsthand. Take the initiative today by comparing fee structures and opening an account that prepares your child for independent financial stability.